Paragraphs with nothing like them in last year's 10-K
Quoted exactly
3 paragraphs in Risk Factors of the 10-K filed Feb 20, 2026
with nothing like them in the 10-K filed Feb 26, 2025. Quoted exactly.
Paragraphs that were only edited are under 10-K change.
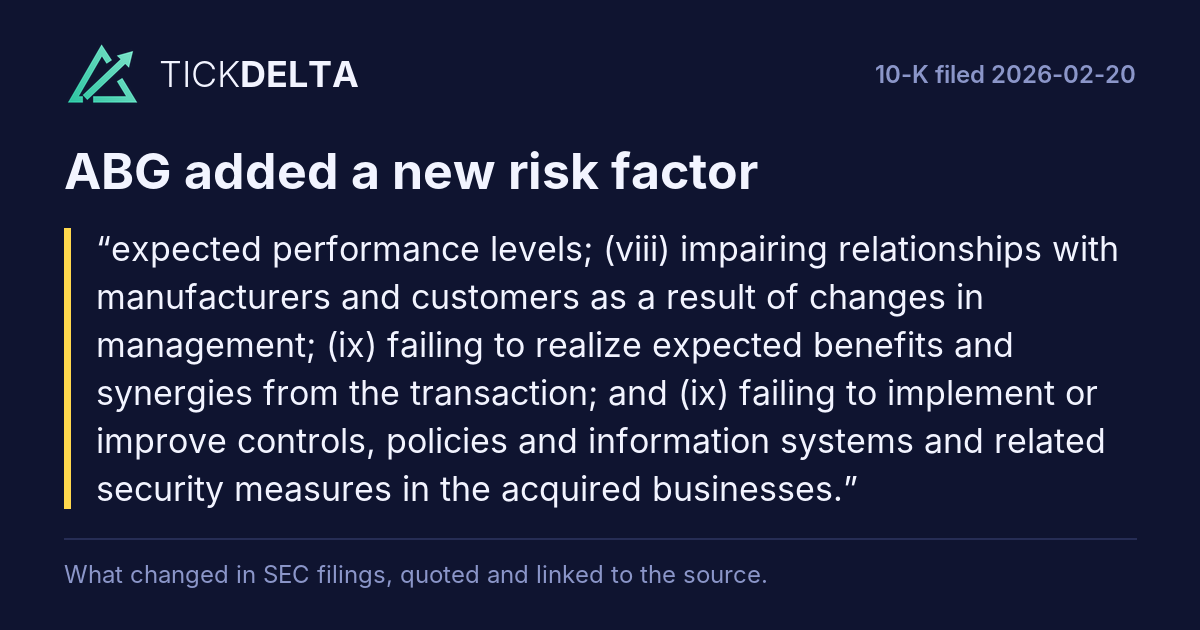
expected performance levels; (viii) impairing relationships with manufacturers and customers as a result of changes in management; (ix) failing to realize expected benefits and synergies from the transaction; and (ix) failing to implement or improve controls, policies and information systems and related security measures in the acquired businesses.
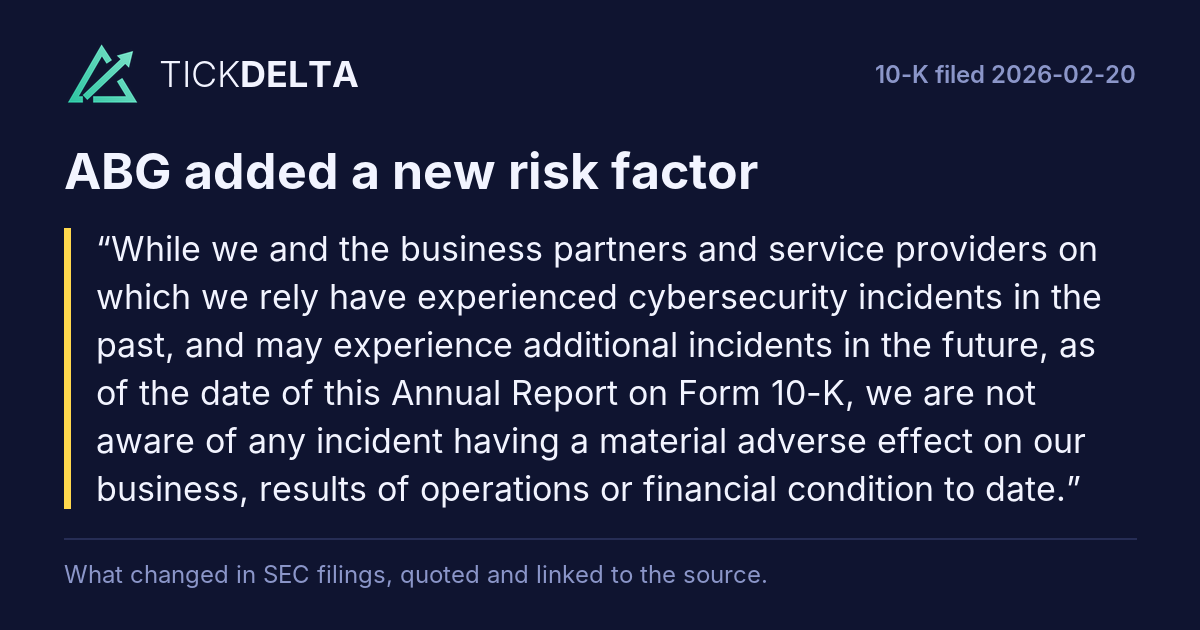
While we and the business partners and service providers on which we rely have experienced cybersecurity incidents in the past, and may experience additional incidents in the future, as of the date of this Annual Report on Form 10-K, we are not aware of any incident having a material adverse effect on our business, results of operations or financial condition to date.
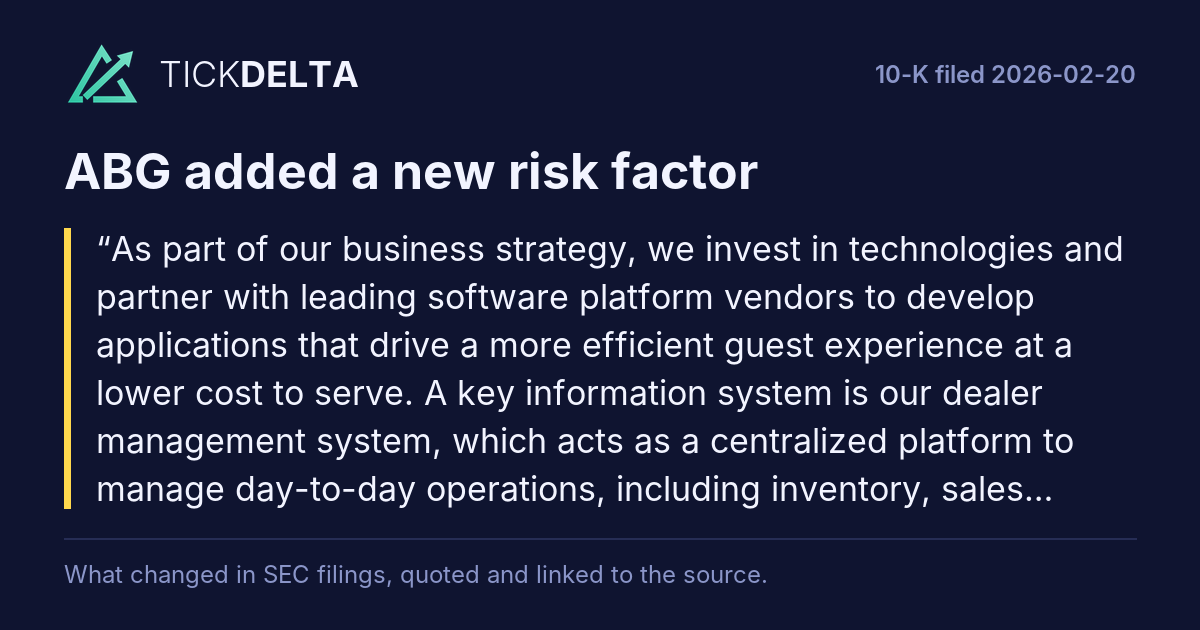
As part of our business strategy, we invest in technologies and partner with leading software platform vendors to develop applications that drive a more efficient guest experience at a lower cost to serve. A key information system is our dealer management system, which acts as a centralized platform to manage day-to-day operations, including inventory, sales, service, finance, and customer relations. The management of our day-to-day business activities could be significantly disrupted if the DMS fails or fails to integrate with other third-party information systems, customer relations management tools or other software, or to the extent that any of these systems become unavailable to us or fail to perform as designed for an extended period of time for any reason, which failure could have a material adverse effect on our business, results of operations, financial condition and cash flows.
Paragraphs in the 10-Q filed Oct 30, 2026 that were not in the one before
New in the latest 10-Q
8 paragraphs in the 10-Q filed Oct 30, 2026 with nothing like
them in the 10-Q filed Jul 31, 2026 (at least half the words must differ; new numbers alone do not count).
Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.
Financial statements and notes
Vehicle Repair and Maintenance Services Finance and Insurance, net Deferred Sales Commissions Total (In millions) Contract assets (long-term), December 31, 2025 $ — $ — $ 82.1 $ 82.1 ───────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────── Contract assets (current), December 31, 2025 $ 22.9 $ 11.8 $ 30.7 $ 65.4 Contract assets, January 1, 2026 $ 22.9 $ 11.8 $ 112.8 $ 147.5 Transferred to receivables from contract assets recognized at the beginning of the period (22.9) (2.1) — (25.1) Amortization of costs incurred to obtain a contract with a customer — — (8.6) (8.6) Costs incurred to obtain a contract with a customer — — 13.1 13.1 Increases related to revenue recognized, inclusive of adjustments to constraint, during the period 23.4 1.9 — 25.3 Contract assets, March 31, 2026 $ 23.4 $ 11.5 $ 117.3 $ 152.2 Transferred to receivables from contract assets recognized at the beginning of the period (23.4) (0.9) — (24.4) Amortization of costs to obtain a contract with a customer — — (13.0) (13.0) Costs incurred to obtain a contract with a customer — — 13.9 13.9 Increases related to revenue recognized, inclusive of adjustments to constraint, during the period 23.1 0.4 — 23.5 Contract assets, June 30, 2026 $ 23.1 $ 11.0 $ 118.2 $ 152.3 Transferred to receivables from contract assets recognized at the beginning of the period (23.1) (1.0) — (24.1) Amortization of costs to obtain a contract with a customer — — (9.7) (9.7) Costs incurred to obtain a contract with a customer — — 13.4 13.4 Increases related to revenue recognized, inclusive of adjustments to constraint, during the period 24.6 0.5 — 25.1 Contract assets, September 30, 2026 $ 24.6 $ 10.5 $ 121.9 $ 157.0 Contract assets (current), September 30, 2026 $ 24.6 $ 10.5 $ 33.9 $ 68.9 Contract assets (long-term), September 30, 2026 $ — $ — $ 88.0 $ 88.0
Read in the 10-Qopen_in_new
The following represents the unaudited pro forma information as if the Herb Chambers acquisition occurred on January 1, 2024:
Read in the 10-Qopen_in_new
The above pro forma financial information adjusts the revenue and net income related to the Herb Chambers acquisition primarily for depreciation, rent and interest expense, assuming that the fair value adjustments and indebtedness incurred in connection with the Herb Chambers acquisition had occurred on January 1, 2024. They have also been adjusted to reflect the $ 14.7 million of acquisition related costs incurred during the nine months ended September 30, 2025, as having occurred on January 1, 2024. The pro forma information also assumes that the July 2025 divestiture of two Lexus and two General Motors dealerships occurred on January 1, 2024. The pro forma net income for the nine months ended September 30, 2025 includes $ 26.0 million of asset impairments recorded by the Company.
Read in the 10-Qopen_in_new
• shifts in consumer preferences among vehicle types, segments and powertrains, including in response to fuel prices, vehicle affordability, and the availability of government incentives for electric and hybrid vehicles;
Read in the 10-Qopen_in_new
During 2026, conflicts between the United States and Iran and between Ukraine and Russia have contributed to volatility in energy markets and higher fuel prices. Elevated fuel prices may influence the types of vehicles consumers choose to purchase, including demand for larger, less fuel-efficient vehicles relative to smaller, hybrid or electric vehicles, and may affect the mix of vehicles we sell and the related gross profit. Changes in federal incentives and emissions regulations may also affect manufacturers’ production and allocation of electric and hybrid vehicles. We cannot predict the duration of these conditions.
Read in the 10-Qopen_in_new
Show the other 3
activities, results in significantly different operating cash flow than if all the cash flows of floor plan notes payable were classified together in operating activities.
Read in the 10-Qopen_in_new
• $26.1 million increase related to other long term assets and liabilities, net.
Read in the 10-Qopen_in_new
During the nine months ended September 30, 2025, we had floor plan borrowings incurred to finance the Herb Chambers acquisition of $262.7 million. In addition, certain subsidiaries of the Company borrowed $546.5 million (the "2025 Real Estate Facility") under a real estate term loan credit agreement. The Company used the proceeds from these borrowings, together with other available funds, to finance the Herb Chambers acquisition.
Read in the 10-Qopen_in_new
The 10-Q's risk factors against the 10-K
Item 1A of the 10-Q filed Oct 30, 2026 against Item 1A of the 10-K filed Feb 20, 2026.
A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed.
Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed,
Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal
(cut words struck through, new words highlighted).
Text on the page, not a score; each links to the filing at sec.gov.
Added10-Q Oct 30, 2026 vs 10-K Feb 20, 2026
In addition to the other information set forth in this Quarterly Report on Form 10-Q, you should carefully consider the risk factors that affect our business and financial results that are discussed in Part I, Item 1A, of our Annual Report on Form 10-K for the year ended December 31, 2025. These factors could materially adversely affect our business, financial condition, liquidity, results of operations and capital position, and could cause our actual results to differ materially from our historical results or the results contemplated by the forward-looking statements contained in this report. There have been no material changes to such risk factors.
Read it in the 10-Q at sec.govopen_in_new
No assurance can be provided that the Herb Chambers Dealerships acquisition will be completed in the manner and on the time frame currently anticipated, or at all. Completion of the Herb Chambers Dealerships acquisition is subject to the satisfaction or waiver of a number of conditions beyond our control that may prevent, delay or otherwise materially adversely affect its completion. If the Herb Chambers Dealerships acquisition is not completed, if there are significant delays in completing the Herb Chambers Dealerships acquisition or if the Herb Chambers Dealerships acquisition involves...
In the 10-K filed Feb 26, 2025open_in_new
Our future growth depends in part on our ability to acquire and effectively integrate acquired dealerships into our organization, such as the pending Herb Chambers Dealerships acquisition. The benefits that are expected to result from the Herb Chambers Dealerships acquisition will depend, in part, on our ability to consummate the Herb Chambers Dealerships acquisition within the anticipated time period, or at all, and to integrate and realize the anticipated cost synergies from the Herb Chambers Dealerships acquisition. There is a significant degree of difficulty and management distraction...
In the 10-K filed Feb 26, 2025open_in_new
The following are some but not all of the factors that could cause actual results or events to differ materially from those anticipated in connection with the Herb Chambers Dealerships acquisition: (i) risks related to disruption of management time from ongoing business operations due to the proposed acquisition; (ii) the failure to realize the benefits expected from the proposed acquisition; (iii) the failure to promptly and effectively integrate the operations, including information technology systems and security, and personnel, including applicable pay plans; (iv) the effect of the...
In the 10-K filed Feb 26, 2025open_in_new
We anticipate the completion of the Herb Chambers Dealerships acquisition will cause us to (i) use a substantial portion of our cash resources; (ii) incur additional debt, which will increase our interest expense, leverage and debt service requirements; (iii) assume certain liabilities; (iv) record goodwill and intangible assets that are subject to impairment testing on a regular basis and potential periodic impairment charges; (v) incur tax expenses in connection with the acquisition and related to the effect of the acquisition on our legal structure; (vi) incur financing, restructuring...
In the 10-K filed Feb 26, 2025open_in_new
Sources
Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.
Also
10-K change: what was reworded or cut, section by section.
Work with it
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/ABG/export.csv") into a cell.