Added10-Q Aug 26, 2026 vs 10-K Mar 9, 2026
number of current and potential customers, as our partners may no longer facilitate the adoption of our services by potential customers.
Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Mar 10, 2025. A box jumps to the paragraph as filed, below.
7 paragraphs in Risk Factors of the 10-K filed Mar 9, 2026 with nothing like them in the 10-K filed Mar 10, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.
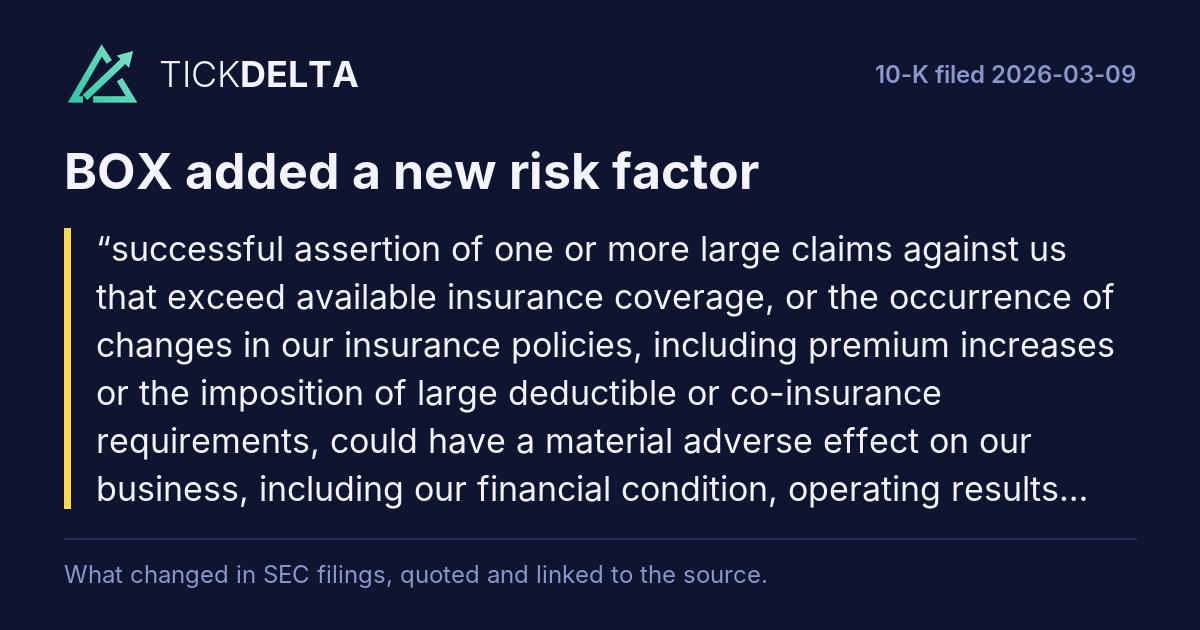
successful assertion of one or more large claims against us that exceed available insurance coverage, or the occurrence of changes in our insurance policies, including premium increases or the imposition of large deductible or co-insurance requirements, could have a material adverse effect on our business, including our financial condition, operating results, and reputation.
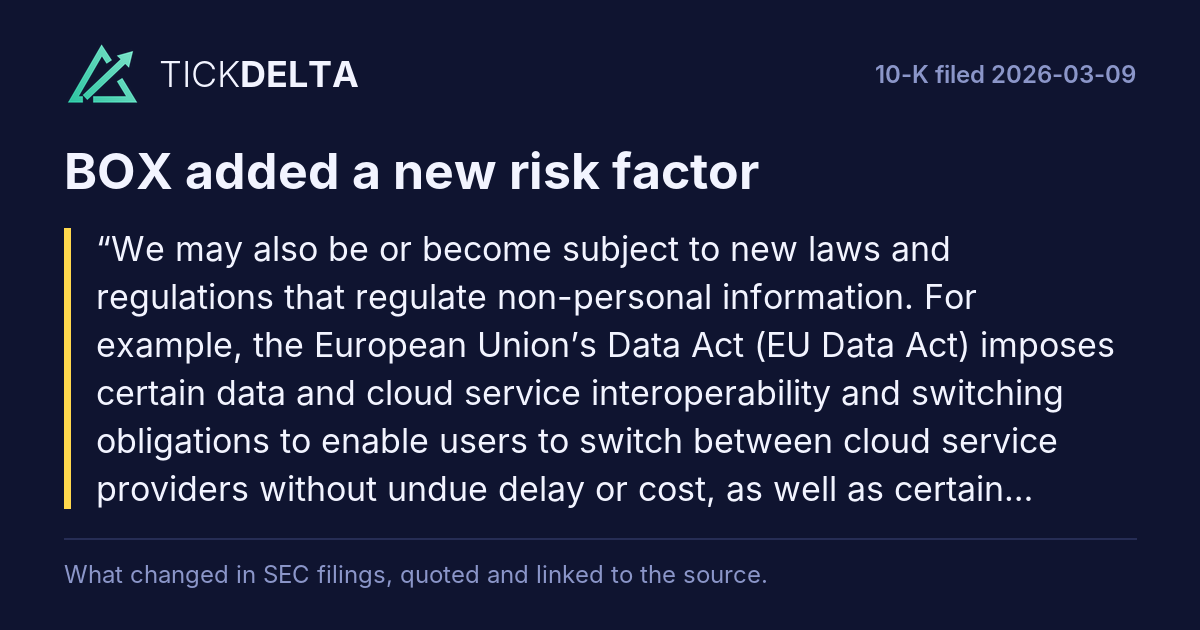
We may also be or become subject to new laws and regulations that regulate non-personal information. For example, the European Union’s Data Act (EU Data Act) imposes certain data and cloud service interoperability and switching obligations to enable users to switch between cloud service providers without undue delay or cost, as well as certain requirements concerning cross-border international transfers of, and governmental access to, non-personal information outside the European Economic Area. Depending on how the EU Data Act and any similar laws or regulations are implemented, interpreted and enforced, we may have to adapt our business practices, contractual arrangements, and services in the EEA to comply with such obligations, which could impact our regional revenue and results of operations.
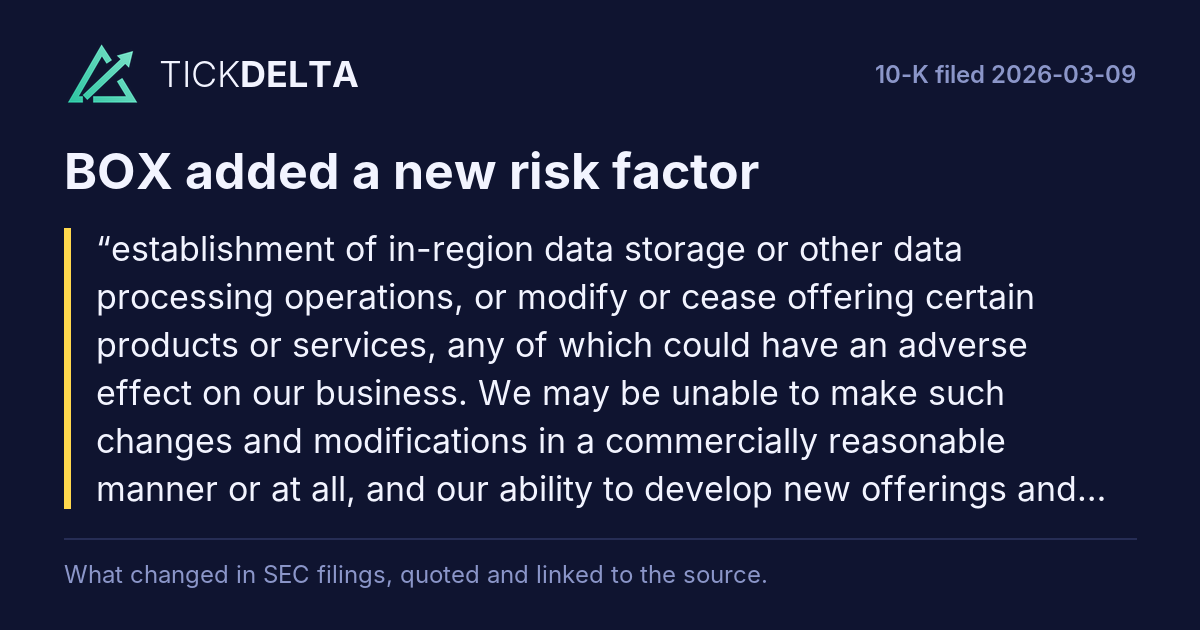
establishment of in-region data storage or other data processing operations, or modify or cease offering certain products or services, any of which could have an adverse effect on our business. We may be unable to make such changes and modifications in a commercially reasonable manner or at all, and our ability to develop new offerings and features could be limited.
We have experienced significant growth in the number of users and the amount of data that our operations infrastructure supports. We need to properly manage our technological operations infrastructure in order to support version control, changes in hardware and software parameters and the evolution of our services. We have
Our services are becoming increasingly mission-critical to our customers’ business operations, as well as their ability to comply with legal requirements, regulations, and standards such as GxP, FINRA, HIPAA, FedRAMP and StateRAMP. These services and offerings are inherently complex and may contain material defects or errors that could cause interruptions in the availability of our services, as well as user error, which could result in loss or
services. Identifying partners and resellers, and negotiating and documenting relationships with them, requires significant time and resources.
From time to time, third parties have claimed, and in the future may claim, that we are infringing upon their intellectual property rights, and we may be found to be infringing upon such rights. We may be unaware of the
New in the latest 10-Q
10 paragraphs in the 10-Q filed Aug 26, 2026 with nothing like them in the 10-Q filed May 27, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.
Six Months Ended July 31, 2026 Series A Convertible Class A Common Additional Accumulated Accumulated Total
Read in the 10-Q
Comprehensive Shares Amount Shares Amount Capital Loss Deficit Deficit Issuance of common stock under employee equity plans, net of shares withheld for employee payroll taxes — — 3,676 — (20,770) — — (20,770) Stock-based compensation related to stock awards — — — — 127,783 — — 127,783 Accretion and dividend on series A convertible preferred stock, net of dividends paid — 1,045 — — (8,545) — — (8,545) Repurchases of common stock — — (7,386) — (181,797) — — (181,797) Other comprehensive loss, net — — — — — (5,486) — (5,486) Net income — — — — — — 36,947 36,947 Six Months Ended July 31, 2025 Series A Convertible Class A Common Additional Accumulated Accumulated Total
Read in the 10-Q
Note 12. Subsequent Event On August 21, 2026, we entered into a Seventh Amendment to Office Lease (the “Seventh Amendment”) with Redwood City Partners, LLC (the “Landlord”), amending that certain Office Lease dated September 15, 2014, as amended, for our corporate headquarters in Redwood City, California. The Seventh Amendment extends the termination date of the lease to June 30, 2040 and reduces the rentable square footage from 283,062 to 242,935 starting July 1, 2028. Total undiscounted base rent payable under the Seventh Amendment, net of rent abatements, from July 1, 2028 through June 30, 2040 is expected to be approximately $283.3 million. In addition to base rent, we are also obligated to pay our proportionate share of certain operating expenses, utilities, insurance costs, and taxes associated with the premises. As an incentive to enter into the Seventh Amendment, the Landlord has agreed to provide a tenant improvement allowance of up to $27.5 million for the design and construction of specified improvements to the leased premises, which is payable through December 31, 2030.
Read in the 10-Q
developed software costs of $4.0 million and decreases of $0.6 million in contractors and consulting services and $0.4 million in workforce reorganization expenses. Research and development expenses as a percentage of revenue remained flat year-over-year.
Read in the 10-Q
litigation by private entities, or other requested remedies or demands, including demands that we modify or cease existing business practices, and expose us to significant fines, penalties and other damages and liabilities. In addition to the possibility of fines, proceedings, demands, claims, and litigation, we may find it necessary or appropriate to fundamentally change our business activities and practices, including the establishment of in-region data storage or other data processing operations, or modify or cease offering certain products or services, any of which could have an adverse effect on our business. We may be unable to make such changes and modifications in a commercially reasonable manner or at all, and our ability to develop new offerings and features could be limited.
Read in the 10-Q
number of current and potential customers, as our partners may no longer facilitate the adoption of our services by potential customers.
Read in the 10-Q
A common stock. In addition, if we are unable to continue to meet these requirements, we may not be able to remain listed on the NYSE.
Read in the 10-Q
On August 21, 2026, we entered into a Seventh Amendment to Office Lease (the “Seventh Amendment”) with Redwood City Partners, LLC (the “Landlord”), amending that certain Office Lease dated September 15, 2014, as amended, for our corporate headquarters in Redwood City, California. The Seventh Amendment extends the termination date of the lease to June 30, 2040 and reduces the rentable square footage from 283,062 to 242,935 starting July 1, 2028. Total undiscounted base rent payable under the Seventh Amendment, net of rent abatements, from July 1, 2028 through June 30, 2040 is expected to be approximately $283.3 million. In addition to base rent, we are also obligated to pay our proportionate share of certain operating expenses, utilities, insurance costs, and taxes associated with the premises. As an incentive to enter into the Seventh Amendment, the Landlord has agreed to provide a tenant improvement allowance of up to $27.5 million for the design and construction of specified improvements to the leased premises, which is payable through December 31, 2030.
Read in the 10-Q
10.1* Box, Inc. Amended and Restated 2015 Equity Incentive Plan, effective June 25, 2026. 8-K 001-36805 10.1 July 1, 2026
Read in the 10-Q
10.2 Seventh Amendment to Office Lease between Box, Inc. and Redwood City Partners, LLC, dated as of August 21, 2026.
Read in the 10-Q
Item 1A of the 10-Q filed Aug 26, 2026 against Item 1A of the 10-K filed Mar 9, 2026.
A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed.
Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed,
Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal
(cut words struck through, new words highlighted).
Text on the page, not a score; each links to the filing at sec.gov.
The first 15 of 22 are shown (at most 12 of each type).
Two-word phrases in Risk Factors of the 10-K filed Mar 9, 2026 that are in none of the 1 earlier 10-Ks stored, back to Mar 10, 2025
Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.
2 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.
Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.
10-K change: what was reworded or cut, section by section.
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/BOX/export.csv") into a cell.