Added10-Q Nov 9, 2026 vs 10-K Mar 2, 2026
In addition to the other information set forth in this report, you should carefully consider the risk factors discussed under “Part I - Item 1A -
Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Mar 3, 2025. A box jumps to the paragraph as filed, below.
6 paragraphs in Risk Factors of the 10-K filed Mar 2, 2026 with nothing like them in the 10-K filed Mar 3, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.
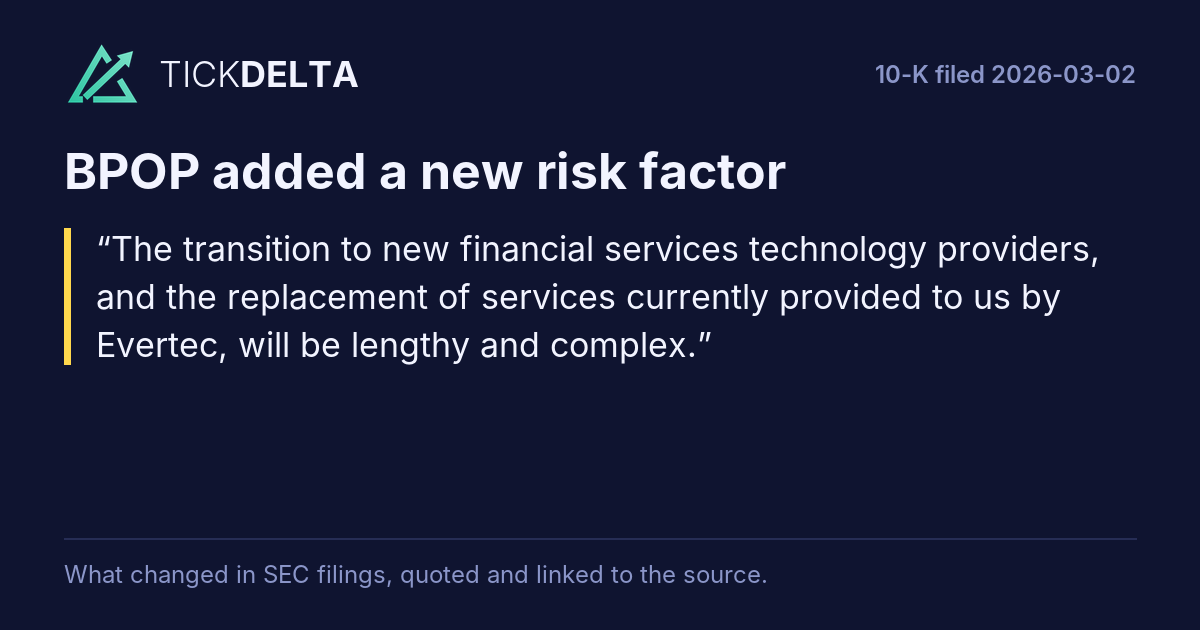
The transition to new financial services technology providers, and the replacement of services currently provided to us by Evertec, will be lengthy and complex.
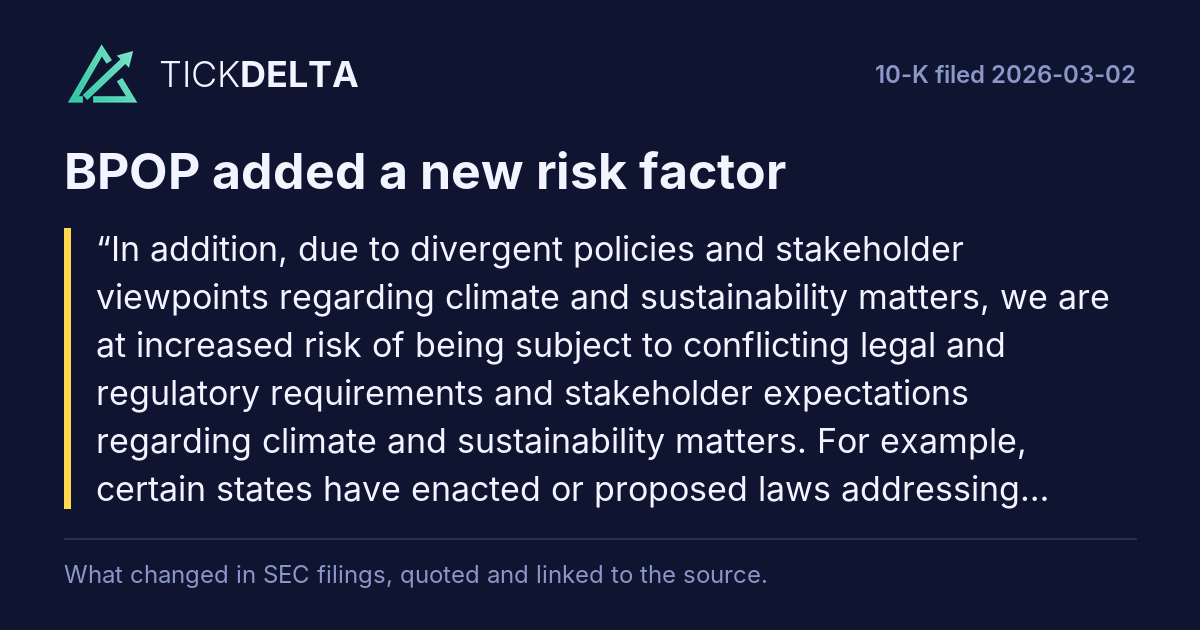
In addition, due to divergent policies and stakeholder viewpoints regarding climate and sustainability matters, we are at increased risk of being subject to conflicting legal and regulatory requirements and stakeholder expectations regarding climate and sustainability matters. For example, certain states have enacted or proposed laws addressing climate change and other sustainability issues, including climate-related disclosure requirements. On the other hand, certain states have enacted or proposed laws or regulations or taken other actions to prohibit the consideration of environmental and social factors in state investments and contracting. In addition, in August 2025, President Trump signed Executive Order 14331, “Guaranteeing Fair Banking Access for All Americans,” which states that it is the policy of the United States that no American should be denied access to financial services because of their constitutionally or statutorily protected beliefs, affiliations, or political views. The Executive Order directs the Treasury Secretary and federal banking regulators to address politicized or unlawful debanking activities. These, as well as other laws, regulations, guidance and expectations, many of which may have broad and extraterritorial application, have in the past subjected and may in the future subject us to additional requirements or different and conflicting requirements and expectations in the various jurisdictions in which we operate, which could negatively affect our business and brand.
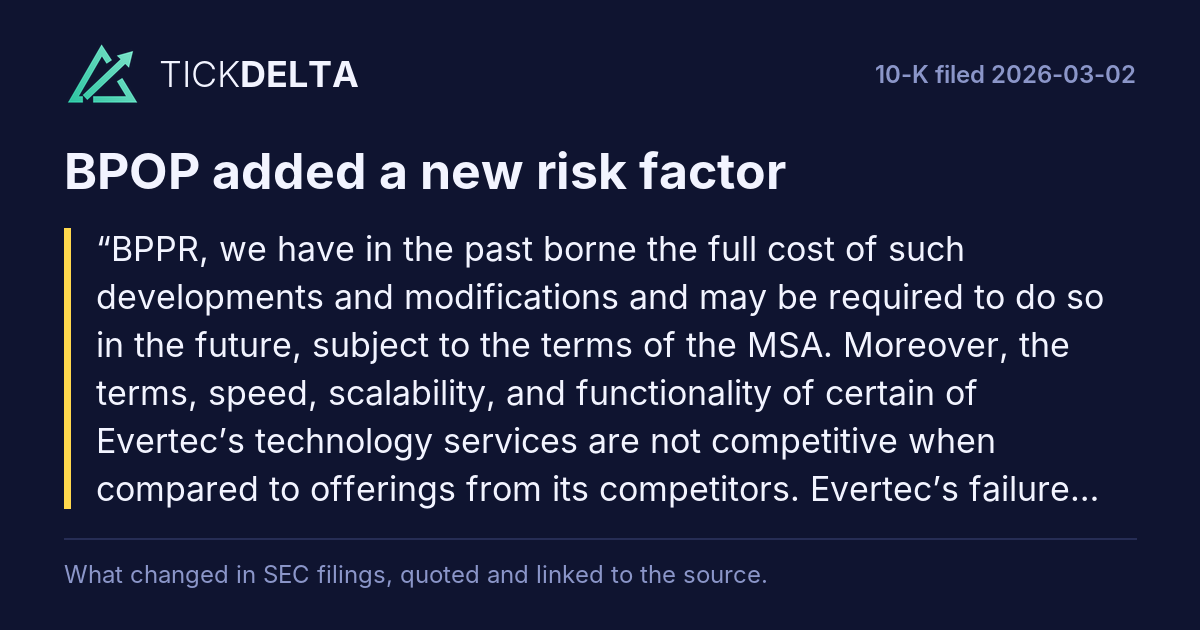
BPPR, we have in the past borne the full cost of such developments and modifications and may be required to do so in the future, subject to the terms of the MSA.
Moreover, the terms, speed, scalability, and functionality of certain of Evertec’s technology services are not competitive when compared to offerings from its competitors. Evertec’s failure to sufficiently invest in and upscale its technology and services infrastructure to meet the rapidly changing technology demands of our industry may result in our being unable to meet customer expectations and attract or retain customers. Furthermore, Evertec’s strategy and investments may also be refocused away from Popular towards other strategic initiatives,
potentially including initiatives that could have the effect of disintermediating us from our
The ability to attract and retain qualified employees is critical to our success.
New in the latest 10-Q
82 paragraphs in the 10-Q filed Nov 9, 2026 with nothing like them in the 10-Q filed Aug 7, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.
A summary of certificates of deposits by maturity at September 30, 2026 follows:
Read in the 10-Q
September 30, 2026, the Corporation had no significant exposure to a single borrower in the BVI.
Read in the 10-Q
(In thousands) Fair value at Valuation technique Unobservable inputs Weighted average (range) [1] September 30, 2025 Other - trading $118 Discounted cash flow model Weighted average life 2 years ──────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────── Yield 12.0% Prepayment speed 10.8% Other real estate owned $34 [2] External appraisal Haircut applied on external appraisals 20.0%
Read in the 10-Q
trend similar to 2024 and 2025. The Corporation evaluates performance trends, including the sustained improvement in operating results
Read in the 10-Q
over recent periods as objectively verifiable positive evidence. However, the Corporation considered as negative evidence history of
Read in the 10-Q
jurisdiction, 2022 and thereafter; and in the Puerto Rico jurisdiction, 2019 and thereafter.
Read in the 10-Q
Subsequent to September 30, 2026, a borrower in the quick service restaurant industry with a commercial and industrial loan relationship
Read in the 10-Q
with BPPR substantially ceased operations and filed for bankruptcy under Chapter 11 of the U.S. Bankruptcy Code. The relationship had
Read in the 10-Q
entered nonperforming status during the second quarter of 2026 and certain reserves and charge-offs related to this relationship had
Read in the 10-Q
already been recorded during the third quarter of 2026. The Corporation determined that these developments provided additional evidence
Read in the 10-Q
about conditions that existed at September 30, 2026 and, therefore, constituted a recognized subsequent event requiring adjustment of
Read in the 10-Q
these interim consolidated financial statements. Accordingly, the Corporation recognized an additional provision for credit losses in
Read in the 10-Q
developments to also result in an additional charge-off related to the relationship in the fourth quarter of 2026.
Read in the 10-Q
higher asset management fees associated with growth in assets under management. In addition, mortgage banking revenues
Read in the 10-Q
benefited from a favorable mortgage servicing rights ("MSR") valuation adjustment and lower portfolio runoff.
Read in the 10-Q
ended September 30, 2025. The increase was mainly driven by higher salaries resulting from annual merit increases, incentives
Read in the 10-Q
and profit sharing. Higher other operating expenses, net occupancy expense and an increase in technology and software
Read in the 10-Q
well as balance sheet information as of September 30, 2026 and December 31, 2025.
Read in the 10-Q
Financial Statements included in this Quarterly Report on Form 10-Q for information on recently adopted accounting standard updates.
Read in the 10-Q
commercial, mortgage and personal loan portfolio along with higher loan yields, which increased by seven basis points to 7.56%;
Read in the 10-Q
repricing continued to reflect lower short-term market rates prevailing earlier in the year, coupled with lower deposit costs in
Read in the 10-Q
was partially offset by lower reserve requirements in the auto and personal loan portfolios due to improved portfolio credit
Read in the 10-Q
The decrease in the construction portfolio was primarily driven by lower reserve requirements due to changes in macroeconomic
Read in the 10-Q
commercial portfolio were mainly attributed to reductions in the Commercial Real Estate ("CRE") portfolio, following the
Read in the 10-Q
the second and third quarters of 2026. These specific reserves are related to certain C&I loans placed in non-performing status
Read in the 10-Q
during 2026 due to borrower-specific circumstances that are not believed to be indicative of broader deterioration in the
Read in the 10-Q
mortgage portfolio of $9 million, and the lease portfolio of $7 million, reflecting improved credit performance, lower reserve
Read in the 10-Q
while the decrease in the consumer portfolio was driven by continued improvements in credit quality.
Read in the 10-Q
higher purchase volumes due, in part, to a new commercial credit card product launched in the second quarter of 2026, higher
Read in the 10-Q
• higher mortgage banking activities by $2 million, primarily due to a favorable fair value adjustment to the Mortgage Servicing
Read in the 10-Q
• an impairment charge on certain equity investments of $2 million; and a $2 million unfavorable fair value adjustment of securities
Read in the 10-Q
held for deferred benefit plans, which have an offsetting effect on personnel costs; and
Read in the 10-Q
higher purchase volumes due, in part, to higher purchase volume driven by a new commercial credit card product launched during
Read in the 10-Q
• $2 million in trading losses attributable to market interest rates increase; and
Read in the 10-Q
• lower services charge on deposits by $2 million driven by a new deposit product launched during the quarter, which offers $0
Read in the 10-Q
incentives by $10 million, including $7 million related to the maximum contribution to the profit-sharing plan and $2 million related
Read in the 10-Q
to short-term incentives, which both are tied to the Corporation's financial performance;
Read in the 10-Q
• higher net occupancy expenses by $3 million driven by a reassessment of real property tax estimate for certain properties in
Read in the 10-Q
• a non-cash goodwill impairment of $13 million that was recorded in the third quarter of 2025 due to lower projected earnings in our
Read in the 10-Q
• non-cash goodwill impairment of $13 million recorded in the third quarter of 2025 due to lower projected earnings in our U.S.
Read in the 10-Q
short-term incentives by $8 million, which are tied to the Corporation's financial performance; and
Read in the 10-Q
same period in 2025; the decrease of $6 million is attributed to the higher proportion of tax exempt income. The ETR for the nine-month
Read in the 10-Q
million; partially offset by lower service charges on deposits accounts by $2 million driven by a new deposit product launched in
Read in the 10-Q
August 2026 which offers $0 service fees to clients that meet certain criteria; and
Read in the 10-Q
compensation and higher salaries expense, higher occupancy expense by $6 million driven by a reassessment of real property
Read in the 10-Q
• lower operating expenses by $16 million, reflecting the goodwill impairment charge related to a U.S. based equipment leasing
Read in the 10-Q
subsidiary of $13 million recorded during the third quarter of 2025, as well as lower occupancy expenses;
Read in the 10-Q
• lower operating expenses by $21 million, reflecting the goodwill impairment charge related to our U.S. based equipment leasing
Read in the 10-Q
subsidiary of $13 million recorded in 2025, as well as lower occupancy expenses and professional fees;
Read in the 10-Q
$5 million compared to December 31, 2025. The decrease was primarily related to lower loans to insurance companies and credit
Read in the 10-Q
losses on debt securities available for sale of $330 million, and common and preferred dividends of $155 million, partially offset by net
Read in the 10-Q
Under the regulatory capital framework applicable to insured depository institutions, a depository institution is considered “well capitalized” if
Read in the 10-Q
requirements. In addition, BPPR and PB met the applicable regulatory capital requirements to be considered “well capitalized” under the
Read in the 10-Q
Reserve Bank of New York partly offset by a rise in market-linked P.R. public deposits. The profile reflects that in rising rate scenarios, the
Read in the 10-Q
Corporation's net interest income would increase slightly during the one-year horizon driven primarily by repricing of variable rate loans and
Read in the 10-Q
fixed-rate intermediate maturity assets coming within one year, offset in part by the repricing of market-linked P.R. public deposits.
Read in the 10-Q
reportable segment and by category, including balances under $250,000, balances exceeding $250,000, uninsured foreign deposits, and
Read in the 10-Q
including the FRB and the New York Department of Financial Services ("NYDFS"), that may limit the ability of those subsidiaries to act as a
Read in the 10-Q
obligations. Recent rating actions by credit rating agencies increased the Corporation's senior debt to investment grade. Management
Read in the 10-Q
expects these actions to enhance access to wholesale funding and, over time, reduce funding costs, subject to market conditions. The
Read in the 10-Q
ended on September 30, 2026. During the third quarter, the Corporation's Board of Directors approved an increase in its quarterly common
Read in the 10-Q
Popular International Bank, Inc. ("PIBI"), a wholly owned subsidiary of Popular, Inc., and $30 million from the non-banking subsidiaries.
Read in the 10-Q
rate reductions by the Federal Reserve. However, inflation has accelerated during 2026, with the annual rate of inflation in the U.S.
Read in the 10-Q
increase from 2% to 3.8% in the annual rate of inflation over the same period of time.
Read in the 10-Q
remains uncertain. In response to inflationary pressures, the Federal Reserve raised interest rates in September 2026 for the first time since
Read in the 10-Q
public corporations, instrumentalities and municipalities (collectively, “P.R. Government Entities”).
Read in the 10-Q
remained favorable, with historically low net charge-offs (despite a slight seasonal increase in the auto portfolio), historically low delinquency
Read in the 10-Q
levels, and net recoveries in the mortgage portfolio. Changes in commercial credit metrics during the quarter were driven by borrower-
Read in the 10-Q
specific developments; core commercial portfolios continue to show stable credit trends.
Read in the 10-Q
mainly reflecting improved credit performance in the auto portfolio, and a $13 million decrease in commercial NPLs. Popular U.S. NPLs
Read in the 10-Q
new NPL inflows during 2026 concentrated in three relationships totaling $198 million, offset by the resolution of a $155 million relationship
Read in the 10-Q
During the second quarter of 2026, a borrower under a commercial and industrial loan relationship in the quick service restaurant industry
Read in the 10-Q
with BPPR, entered nonperforming status. Reserves and charge-offs related to the relationship were recorded during the third quarter of
Read in the 10-Q
2026. Subsequent to September 30, 2026, the borrower filed for bankruptcy and substantially ceased operations. Because this development
Read in the 10-Q
provided additional evidence regarding conditions that existed at September 30, 2026, the Corporation recognized an additional provision
Read in the 10-Q
additional charge-off related to the relationship during the fourth quarter of 2026. See Note 27 - Subsequent Events to the unaudited interim
Read in the 10-Q
At September 30, 2026, BPPR’s funded exposure to borrowers in the quick service restaurant industry was $327 million, representing
Read in the 10-Q
approximately 5.4% of BPPR’s commercial and industrial loan portfolio, with an additional $45 million of unfunded commitments. Excluding
Read in the 10-Q
the relationship described above, the remaining funded exposure totaled $277 million, of which 99.6% was current and not adversely
Read in the 10-Q
Construction loans, which are excluded from the CRE portfolio described above, represent another significant real estate-secured loan
Read in the 10-Q
exposure. At September 30, 2026, the Corporation’s construction loan portfolio totaled $1.6 billion, including $469 million at BPPR and $1.1
Read in the 10-Q
in market risk exposures from disclosures presented in the 2025 Annual Report on Form 10-K.
Read in the 10-Q
Item 1A of the 10-Q filed Nov 9, 2026 against Item 1A of the 10-K filed Mar 2, 2026.
A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed.
Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed,
Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal
(cut words struck through, new words highlighted).
Text on the page, not a score; each links to the filing at sec.gov.
What the 10-Q itself says about its risk factors:Risk Factors" in our 2025 Annual Report on Form 10-K. These factors could materially adversely affect our business, financial condition,
Read in the 10-Q
What the 10-Q itself says about its risk factors:supplement or update the discussion of risk factors below and in our 2025 Annual Report on Form 10-K.
Read in the 10-Q
What the 10-Q itself says about its risk factors:There have been no material changes to the risk factors previously disclosed under Item 1A of the Corporation’s 2025 Annual Report on
Read in the 10-Q
Two-word phrases in Risk Factors of the 10-K filed Mar 2, 2026 that are in none of the 1 earlier 10-Ks stored, back to Mar 3, 2025
Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.
6 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.
Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.
10-K change: what was reworded or cut, section by section.
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/BPOP/export.csv") into a cell.