Screener / SEC EDGAR /CIK 0001714174 /10-K filed Feb 26, 2026, compared with Mar 3, 2025 /Numbers from the XBRL of the 10-Ks
NYSE Financials · Financial Services

Burford Capital Ltd BUR

Compare with peers Embed
New in the 10-K 5 paragraphs with nothing like them in the 10-K filed Mar 3, 2025 New in the 10-Q 14 paragraphs not in the 10-Q filed Aug 6, 2026 10-Q against the 10-K 6 risk factor paragraphs and sentences added or reworded

New risk paragraphs, branching off last year

Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Mar 3, 2025. A box jumps to the paragraph as filed, below.

5 new

Paragraphs with nothing like them in last year's 10-K

Quoted exactly

5 paragraphs in Risk Factors of the 10-K filed Feb 26, 2026 with nothing like them in the 10-K filed Mar 3, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.

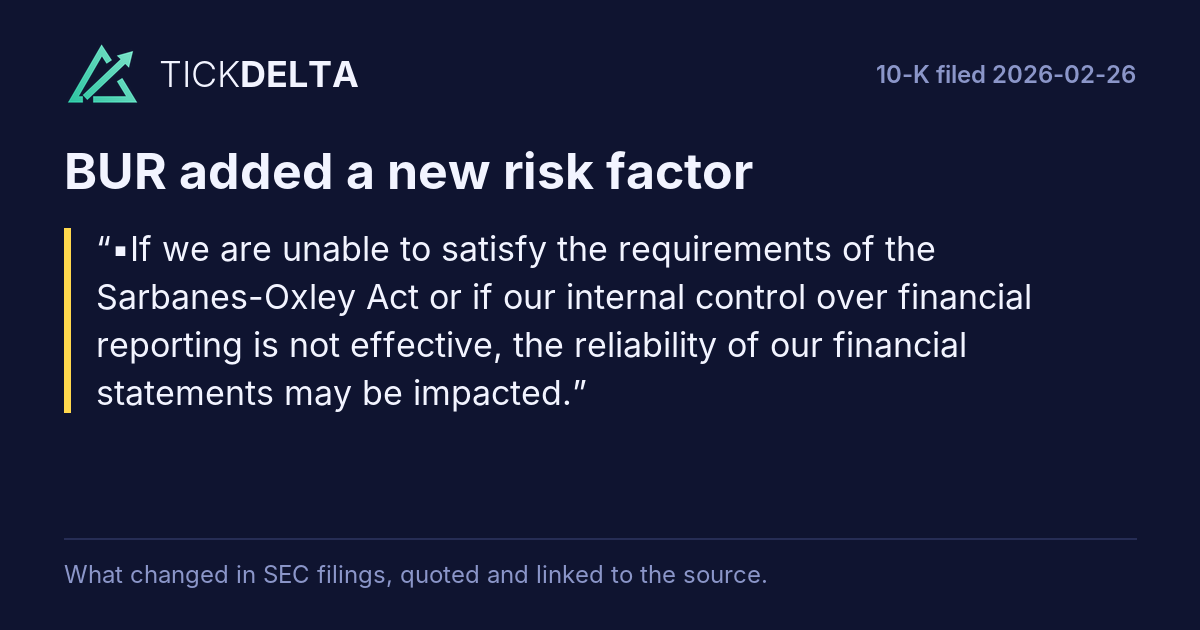
▪If we are unable to satisfy the requirements of the Sarbanes-Oxley Act or if our internal control over financial reporting is not effective, the reliability of our financial statements may be impacted.

Read in the 10-K

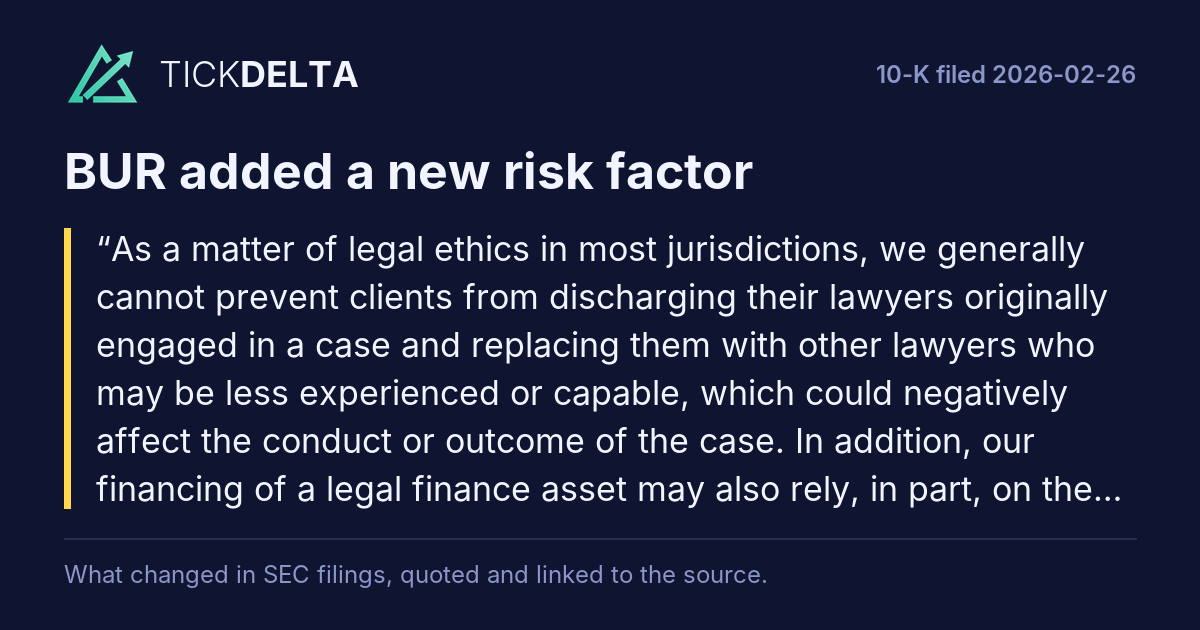
As a matter of legal ethics in most jurisdictions, we generally cannot prevent clients from discharging their lawyers originally engaged in a case and replacing them with other lawyers who may be less experienced or capable, which could negatively affect the conduct or outcome of the case. In addition, our financing of a legal finance asset may also rely, in part, on the economic arrangements with the originally engaged lawyers. If those lawyers are discharged, the value of those economic arrangements may be reduced or eliminated, even if replacement lawyers are retained, which could adversely affect the value of the related legal finance asset.

Read in the 10-K

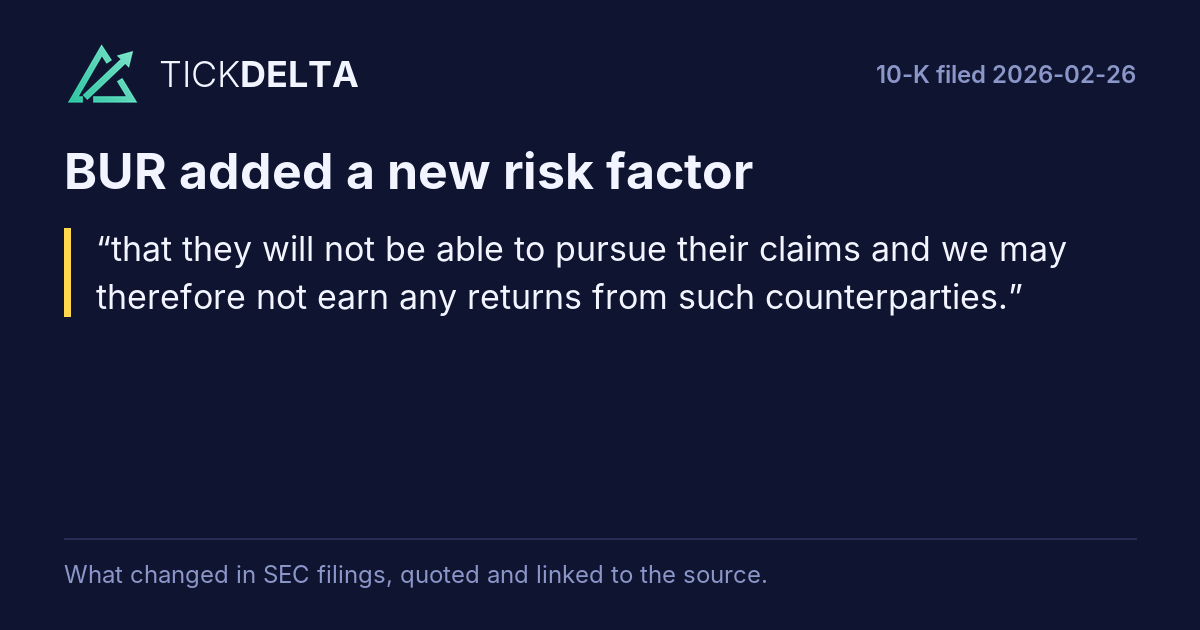
that they will not be able to pursue their claims and we may therefore not earn any returns from such counterparties.

Read in the 10-K

suitable replacements for significant numbers of qualified personnel or consultants could materially adversely affect our business and growth prospects.

Read in the 10-K

▪Difficulties in attracting and retaining qualified international management and/or personnel

Read in the 10-K

Paragraphs in the 10-Q filed Nov 4, 2026 that were not in the one before

New in the latest 10-Q

14 paragraphs in the 10-Q filed Nov 4, 2026 with nothing like them in the 10-Q filed Aug 6, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.

10-Q

(Former name, former address and former fiscal year, if changed since last report)

Read in the 10-Q

▪ Our ability to comply with the covenants in the indentures governing our outstanding debt securities and changes in our credit ratings

Read in the 10-Q

Financial statements and notes

of the 2029 Notes repurchased (or, in the case of other senior indebtedness, at the price required thereby, but not to exceed 100 % of the principal amount thereof), plus accrued and unpaid interest.

Read in the 10-Q

The Collateral (as defined in the indenture governing the 2029 Notes) that secures the 2029 Notes and the related guarantees consists of (i) in the case of the Company and any Foreign Guarantor (as defined in the indenture governing the 2029 Notes) (a) all of the capital stock of the wholly owned restricted subsidiaries to the extent directly owned by the Company or such Foreign Guarantor, respectively, and (b) solely in the event the Company or such Foreign Guarantor pledges assets to secure any Triggering Indebtedness (as defined in the indenture governing the 2029 Notes), the assets so pledged by the Company or such Foreign Guarantor, respectively, to secure such Triggering Indebtedness and (ii) in the case of the Issuer or any U.S. Guarantor (as defined in the indenture governing the 2029 Notes), all of the assets and property of the Issuer or such U.S. Guarantor, respectively, in the case of each of clauses (i) and (ii), other than any Excluded Assets (as defined in the indenture governing the 2029 Notes). The Collateral will exclude certain assets and the security interests in the Collateral will be subject to certain additional exceptions and limitations.

Read in the 10-Q

Total capital provision asset deployments were $94.0 million during the three months ended September 30, 2026. Of the total capital deployed during 2026, 14% was related to the vintage year 2020 and earlier vintage years.

Read in the 10-Q
Show the other 9

Total capital provision asset deployments were $269.1 million during the nine months ended September 30, 2026. Of the total capital deployed during 2026, 23% was related to the vintage year 2020 and earlier vintage years.

Read in the 10-Q

Total capital provision asset realizations were $74.6 million during the three months ended September 30, 2026. Of the total realizations during 2026, 19% was related to the vintage year 2020 and earlier vintage years.

Read in the 10-Q

Total capital provision asset realizations were $244.3 million during the nine months ended September 30, 2026. Of the total realizations during 2026, 35% was related to the vintage year 2020 and earlier vintage years.

Read in the 10-Q

($ in thousands) Consolidated Third-party interests Total segments (Burford-only) Consolidated Third-party interests Total segments (Burford-only)

Read in the 10-Q

Fair value adjustment during the period, net of previously recognized unrealized gains/(losses) transferred to realized gains/(losses) 122,958 (24,961) 97,997 (2,368,338) 823,101 (1,545,237)

Read in the 10-Q

Other information

On August 27, 2026, Mr. Christopher Bogart, our Chief Executive Officer, as trustee of, and on behalf of, Christopher P. Bogart Revocable Trust, entered into a “ Rule 10b5-1 trading arrangement ” (as defined by Item 408(a) of Regulation S-K). Mr. Bogart’s “Rule 10b5-1 trading arrangement” provides for the sale of up to 375,000 of the Company’s ordinary shares between December 2, 2026 and September 30, 2027 and is intended to satisfy the affirmative defense of Rule 10b5-1(c) under the Exchange Act.

Read in the 10-Q

On August 27, 2026, Mr. Jonathan Molot, our Chief Investment Officer, entered into a “Rule 10b5-1 trading arrangement” (as defined by Item 408(a) of Regulation S-K). Mr. Molot’s “ Rule 10b5-1 trading arrangement ” provides for the sale of up to 375,000 of the Company’s ordinary shares between December 2, 2026 and September 30, 2027 and is intended to satisfy the affirmative defense of Rule 10b5-1(c) under the Exchange Act.

Read in the 10-Q

On August 27, 2026, Ms. Elizabeth O’Connell, our Chief Strategy Officer, as trustee of, and on behalf of, Elizabeth M. O’Connell Revocable Trust, entered into a “ Rule 10b5-1 trading arrangement ” (as defined by Item 408(a) of Regulation S-K). Ms. O’Connell’s “Rule 10b5-1 trading arrangement” provides for the sale of up to 20,000 of the Company’s ordinary shares between December 2, 2026 and September 30, 2027 and is intended to satisfy the affirmative defense of Rule 10b5-1(c) under the Exchange Act.

Read in the 10-Q

Item 6

4.1 Indenture, dated as of September 17, 2026, by and among Burford Capital Global Finance LLC, as issuer, Burford Capital Limited, as parent guarantor, the other guarantors party thereto from time to time and U.S. Bank Trust Company, National Association, as trustee and collateral agent (including as Exhibit A thereto the Form of 8.000% Senior Secured Notes due 2029) (incorporated by reference to Exhibit 4.1 to the Current Report on Form 8-K of Burford Capital Limited (File No. 001-39511) as...

Read in the 10-Q

The 10-Q's risk factors against the 10-K

Item 1A of the 10-Q filed Nov 4, 2026 against Item 1A of the 10-K filed Feb 26, 2026. A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed. Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed, Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal (cut words struck through, new words highlighted). Text on the page, not a score; each links to the filing at sec.gov.

What the 10-Q itself says about its risk factors:See “Risk Factors” in the 2025 Form 10-K for a discussion of potential risks and uncertainties that could materially and adversely affect our business, financial condition, results of operations and/or liquidity. In addition, we have amended one of those risk factors in the 1Q26 Form 10-Q as set forth below. As of the date of this Form 10-Q, there have been no material changes to the risks and uncertainties disclosed in the 2025 Form 10-K and the Previous Forms 10-Q.

Read in the 10-Q
Added10-Q Nov 4, 2026 vs 10-K Feb 26, 2026
The risks and uncertainties disclosed in the 2025 Form 10-K, the Previous Forms 10-Q and this Form 10-Q are not the only risks and uncertainties facing us, and additional risks and uncertainties not currently known to us or that we currently deem to be immaterial may also materially and adversely affect our business, financial condition, results of operations and/or liquidity. We may disclose changes to such risks and uncertainties or disclose additional risks and uncertainties from time to time in our future periodic filings with the SEC.

Read it in the 10-Q at sec.gov

Added10-Q Nov 4, 2026 vs 10-K Feb 26, 2026
Fair value of capital provision assets - Fair value of YPF-related assets” for additional information with respect to the YPF-related assets.

Read it in the 10-Q at sec.gov

Reworded10-Q Nov 4, 2026 vs 10-K Feb 26, 2026
See “Management's discussion and analysis of financial condition and results of operations—Results operations - Results of operations and financial condition—Fair value of capital provision assets—Fair value of YPF-related assets” for additional information with respect to the YPF-related assets. condition -

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 4, 2026 vs 10-K Feb 26, 2026
We have As of December 31, 2025 and 2024, respectively, one set of exposures to the YPF-related assets that accounted for approximately 46% and 42% of the fair value of our capital provision assets as of December 31, 2025 and 2024, respectively. assets.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 4, 2026 vs 10-K Feb 26, 2026
See note 2 (Summary of significant accounting policies—Fair policies - Fair value of financial instruments), note 5 (Capital provision assets) and note 14 (Fair value of assets and liabilities) to our audited consolidated financial statements contained in this the 2025 Form 10-K and “Management's discussion and analysis of financial condition and results of operations—Results operations - Results of operations and financial condition—Fair condition - Fair value of capital provision assets” for additional information with respect to our valuation policy and fair value of our capital provision assets.

Read it in the 10-Q at sec.govThe 10-K sentence

Show the other 1

Phrases used for the first time

Two-word phrases in Risk Factors of the 10-K filed Feb 26, 2026 that are in none of the 1 earlier 10-Ks stored, back to Mar 3, 2025

data dissemination ×4systems risks ×3information intellectual ×2strategy due ×2cybersecurity measures ×2originally engaged ×2economic arrangements ×2employee data ×2
Where each one is used
  • data dissemination: ▪Information systems risks could result in the loss of data, dissemination of confidential or privileged information, business interruptions or reputational damage, which could in turn subject us to regulatory actions, increased costs and financial loss.
  • systems risks: ▪Information systems risks could result in the loss of data, dissemination of confidential or privileged information, business interruptions or reputational damage, which could in turn subject us to regulatory actions, increased costs and financial loss.
  • information intellectual: ▪Our business and operations could suffer if we are not able to prevent improper use or disclosure of, or access to, privileged information, intellectual property or litigation or business strategy due to cybersecurity breaches, unauthorized use or theft.
  • strategy due: ▪Our business and operations could suffer if we are not able to prevent improper use or disclosure of, or access to, privileged information, intellectual property or litigation or business strategy due to cybersecurity breaches, unauthorized use or theft.
  • cybersecurity measures: As described under “—Risks relating to cybersecurity, third-party service providers, information systems and data privacy and protection—Information systems risks could result in the loss of data, dissemination of confidential or privileged information, business interruptions or reputational damage, which could in...
  • originally engaged: As a matter of legal ethics in most jurisdictions, we generally cannot prevent clients from discharging their lawyers originally engaged in a case and replacing them with other lawyers who may be less experienced or capable, which could negatively affect the conduct or outcome of the case. In addition, our...
  • economic arrangements: As a matter of legal ethics in most jurisdictions, we generally cannot prevent clients from discharging their lawyers originally engaged in a case and replacing them with other lawyers who may be less experienced or capable, which could negatively affect the conduct or outcome of the case. In addition, our...
  • employee data: Our information systems and those of the third parties that we may engage from time to time may fail to operate properly or become disabled as a result of tampering or a breach of our network security systems or otherwise, as a result of tampering or a breach of our third parties’ network security systems or as a...

The 10-K at sec.gov

Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.

What was taken out

8 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.

Across all companies
As disclosed under “Controls and procedures”, a material weakness existed in our internal control over financial reporting as of December 31, 2024 as we have not yet fully remediated the material weakness in internal control over financial reporting previously disclosed in the Company’s annual report on Form 20-F for the year ended December 31, 2023 filed with the SEC on March 28, 2024 (the “2023 Form 20-F”) relating to a lack of available evidence to demonstrate the precision of our management’s review of the process to determine certain assumptions used in the measurement of the fair...
In the 10-K filed Mar 3, 2025
motivate our existing personnel and consultants. We may lose financing opportunities if we do not match our competitors’ pricing, terms, structure and/or quality of service. If we are forced to match our competitors’ pricing, terms, structure and/or quality of service to commit and/or deploy our capital, we may not be able to achieve acceptable returns on our legal finance assets or may bear substantial risk of capital loss.
In the 10-K filed Mar 3, 2025
Under the PCAOB auditing standards applicable to us as a reporting company under the Exchange Act, a “material weakness” is a deficiency, or a combination of deficiencies, in internal control over financial reporting, such that there is a reasonable possibility that a material misstatement of our consolidated financial statements will not be prevented or detected on a timely basis.
In the 10-K filed Mar 3, 2025
We are subject to the reporting requirements of the Exchange Act, the Sarbanes-Oxley Act, the Dodd-Frank Wall Street Reform and Consumer Protection Act of 2010, as amended, the listing requirements of the NYSE and other applicable securities rules and regulations. In addition, as of June 30, 2024, we determined that
In the 10-K filed Mar 3, 2025

Sources

Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.

Also

10-K change: what was reworded or cut, section by section.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/BUR/export.csv") into a cell.

Next:10-K change
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.