Screener / SEC EDGAR /CIK 0000861842 /10-K filed Mar 2, 2026, compared with Feb 28, 2025 /Numbers from the XBRL of the 10-Ks
Nasdaq Financials · Banks

Cathay General Bancorp CATY

Compare with peers Embed
New in the 10-K 1 paragraphs with nothing like them in the 10-K filed Feb 28, 2025 New in the 10-Q 7 paragraphs not in the 10-Q filed Aug 7, 2026 10-Q against the 10-K 1 risk factor paragraphs and sentences added or reworded

New risk paragraphs, branching off last year

Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Feb 28, 2025. A box jumps to the paragraph as filed, below.

1 new

Paragraphs with nothing like them in last year's 10-K

Quoted exactly

1 paragraph in Risk Factors of the 10-K filed Mar 2, 2026 with nothing like it in the 10-K filed Feb 28, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.

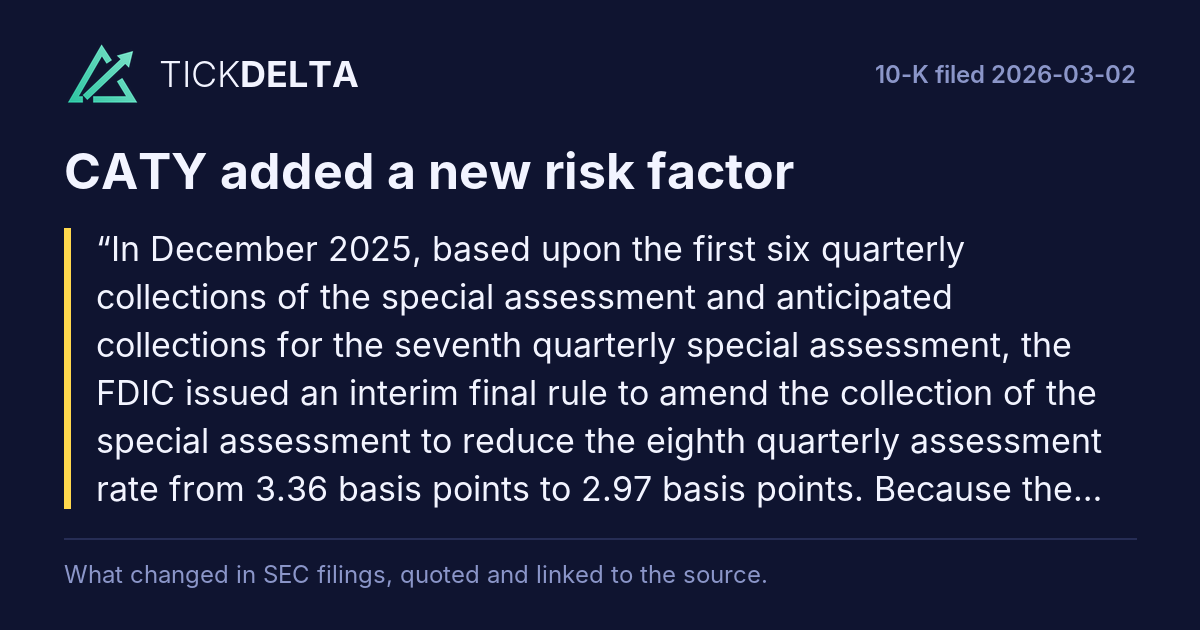
In December 2025, based upon the first six quarterly collections of the special assessment and anticipated collections for the seventh quarterly special assessment, the FDIC issued an interim final rule to amend the collection of the special assessment to reduce the eighth quarterly assessment rate from 3.36 basis points to 2.97 basis points. Because the cumulative amount collected through the initial eight quarter special assessment period is projected to equal the FDIC’s loss estimate, the additional two quarter extend assessment period was removed. The interim final rule also requires the FDIC to provide an offset to regular quarterly deposit insurance assessments for institutions subject to the special assessment if the aggregate amount collected exceeds estimated losses following the resolution of pending litigation, and again following the termination of the receiverships. As provided for in the special assessment rule, if losses at the termination of the receiverships exceed the amount collected, the FDIC will implement a one-time final shortfall special assessment to ensure the full amount of actual losses is recovered as required by law.

Read in the 10-K

Paragraphs in the 10-Q filed Nov 6, 2026 that were not in the one before

New in the latest 10-Q

7 paragraphs in the 10-Q filed Nov 6, 2026 with nothing like them in the 10-Q filed Aug 7, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.

Financial statements and notes

Nine Months Ended September 30, 2026 Financial Effects of Loan Modifications Term Extension Payment Delay Combo-Rate Reduction/Term Extension/Payment Delay Total Modification as a % of Loan Class Weighted-Average Reduction in Rate Weighted-Average Term Extension Weighted-Average Payment Deferral

Read in the 10-Q

Three Months Ended September 30, 2025 Financial Effects of Loan Modifications Term Extension Payment Delay Combo-Rate Reduction/Term Extension/Payment Delay Total Modification as a % of Loan Class Weighted-Average Reduction in Rate Weighted-Average Term Extension Weighted-Average Payment Deferral

Read in the 10-Q

Nine Months Ended September 30, 2025 Financial Effects of Loan Modifications Term Extension Payment Delay Combo-Rate Reduction/Term Extension/Payment Delay Total Modification as a % of Loan Class Weighted-Average Reduction in Rate Weighted-Average Term Extension Weighted-Average Payment Deferral

Read in the 10-Q

As of September 30, 2026, the Company completed the redemption of $54.1 million of Trust Preferred Securities ("TruPS"), issued by three of the Company's statutory business trusts and extinguished the related Junior Subordinated Notes. There was no gain or loss on the extinguishment of the Junior Subordinated Notes, as the reacquisition price equaled the carrying amount.

Read in the 10-Q

The increase in the ACL was driven primarily by strong quarterly loan growth and updated loss assumptions incorporating recent loan and charge-off data. This was largely offset by a decrease in individually evaluated reserves from three isolated credits - one construction loan which was fully reserved for last quarter, and two movie theater CRE loans inherited from the Far East National Bank acquisition.

Read in the 10-Q
Show the other 2

The qualitative component of the allowance decreased modestly during the quarter, inversely impacted by enhancements to the quantitative model’s updated loss assumptions. No new emerging qualitative risks were identified this quarter.

Read in the 10-Q

Share sales and buybacks

Issuer Purchases of Equity Securities Period (a) Total Number of Shares Purchased (b) Average Price Paid per Share (or Unit) (c) Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs (1) (d) Maximum Dollar Value of Shares that May Yet Be Purchased Under the Plans or Programs (July 1, 2026 - July 31, 2026) 155,594 $63.12 155,594 $126,133,364 (August 1, 2026 - August 31, 2026) 420,000 $63.33 420,000 $99,535,748 (September 1, 2026 - September 30, 2026) 225,000 $61.62 225,000 $85,671,258 Total 800,594 $62.81 800,594 $85,671,258 (1) On April 23, 2026, the Company announced the current $150.0 million share repurchase program. On July 22, 2026, the Company announced a proposed increase in the program of $50.0 million, to a total of $200.0 million, which is currently pending regulatory approval. The current stock repurchase program expires on April 23, 2027.

Read in the 10-Q

The 10-Q's risk factors against the 10-K

Item 1A of the 10-Q filed Nov 6, 2026 against Item 1A of the 10-K filed Mar 2, 2026. A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed. Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed, Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal (cut words struck through, new words highlighted). Text on the page, not a score; each links to the filing at sec.gov.

Added10-Q Nov 6, 2026 vs 10-K Mar 2, 2026
The Company is not aware of any material change to the risk factors as previously disclosed in Part I, Item 1A, of the Company’s 2025 Form 10-K for the year ended December 31, 2025. In addition to the other information set forth in this Quarterly Report on Form 10-Q, you should carefully consider the risk factors disclosed in Part I, Item 1A, of the Company’s 2025 Form 10-K for the year ended December 31, 2025, which could materially and adversely affect the Company’s business, financial condition, results of operations and stock price. The risk factors disclosed in the 2025 Form 10-K are not the only risks facing the Company. Additional risks and uncertainties, including those not presently known to the Company or that the Company presently believes not to be material, could also materially and adversely affect the Company’s business, financial condition, and results of operations and stock price.

Read it in the 10-Q at sec.gov

Phrases used for the first time

Two-word phrases in Risk Factors of the 10-K filed Mar 2, 2026 that are in none of the 1 earlier 10-Ks stored, back to Feb 28, 2025

amount collected ×3federal funds ×2funds rate ×2estimated losses ×2interim final ×2assessment period ×2
Where each one is used
  • amount collected: In December 2025, based upon the first six quarterly collections of the special assessment and anticipated collections for the seventh quarterly special assessment, the FDIC issued an interim final rule to amend the collection of the special assessment to reduce the eighth quarterly assessment rate from 3.36 basis...
  • federal funds: We seek to minimize the adverse effects of changes in interest rates by structuring our asset-liability composition to obtain the maximum spread. We use interest rate sensitivity analysis and a simulation model to assist us in estimating the optimal asset-liability composition. However, such management tools have...
  • funds rate: We seek to minimize the adverse effects of changes in interest rates by structuring our asset-liability composition to obtain the maximum spread. We use interest rate sensitivity analysis and a simulation model to assist us in estimating the optimal asset-liability composition. However, such management tools have...
  • estimated losses: The FDIC initial estimates of the total cost of the failures of Silicon Valley Bank and Signature Bank, were approximately $16.3 billion and was attributable to the protection of uninsured depositors. The FDIC has subsequently updated its estimate of the DIF's losses that are recoverable through the special...
  • interim final: In December 2025, based upon the first six quarterly collections of the special assessment and anticipated collections for the seventh quarterly special assessment, the FDIC issued an interim final rule to amend the collection of the special assessment to reduce the eighth quarterly assessment rate from 3.36 basis...
  • assessment period: In December 2025, based upon the first six quarterly collections of the special assessment and anticipated collections for the seventh quarterly special assessment, the FDIC issued an interim final rule to amend the collection of the special assessment to reduce the eighth quarterly assessment rate from 3.36 basis...

The 10-K at sec.gov

Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.

What was taken out

1 paragraph of last year's Risk Factors with nothing like them now. The longest are quoted.

Across all companies
The special assessment initially would be collected at an annual rate of approximately 13.4 basis points for an anticipated total of eight quarterly assessment periods. Given the update to the loss estimates and the increase in the aggregate special assessment base resulting from amendments to the reported amount of estimated uninsured deposits, the FDIC currently projects that the special assessment will be collected for an additional two quarter beyond the initial eight-quarter collection period, at a lower rate. Because the estimated loss pursuant to the systemic risk determination will...
In the 10-K filed Feb 28, 2025

Sources

Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.

Also

10-K change: what was reworded or cut, section by section.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/CATY/export.csv") into a cell.

Next:10-K change
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.