Added10-Q Nov 5, 2026 vs 10-K Mar 6, 2026
Item 2. Unregistered Sales of Equity Securities, Use of Proceeds, and Issuer Purchases of Equity Securities
Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Mar 10, 2025. A box jumps to the paragraph as filed, below.
5 paragraphs in Risk Factors of the 10-K filed Mar 6, 2026 with nothing like them in the 10-K filed Mar 10, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.
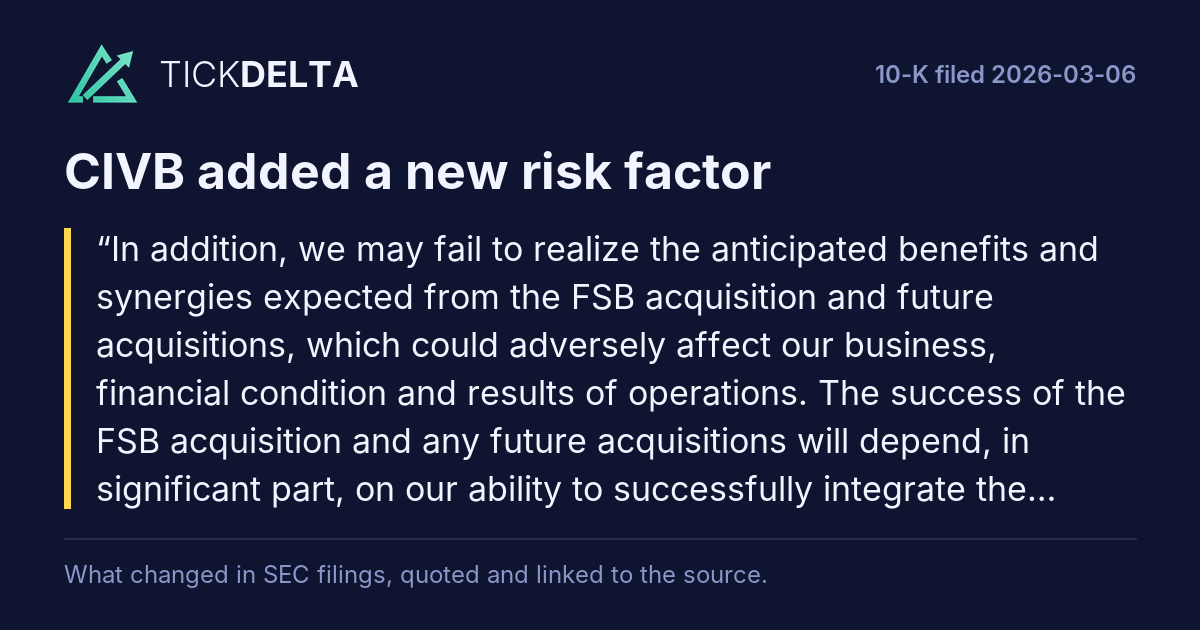
In addition, we may fail to realize the anticipated benefits and synergies expected from the FSB acquisition and future acquisitions, which could adversely affect our business, financial condition and results of operations. The success of the FSB acquisition and any future acquisitions will depend, in significant part, on our ability to successfully integrate the acquired business, grow our revenue and realize the anticipated strategic benefits and synergies from the combination. However, achieving these goals requires, among other things, realization of targeted cost synergies. This growth and the anticipated benefits of the transaction may not be realized fully, or at all, or may take longer to realize than expected. Actual operating, strategic and revenue opportunities, if achieved at all, may be less significant than expected or may take longer to achieve than anticipated. If we are not able to achieve these objectives and realize the anticipated benefits and synergies expected from the FSB acquisition and any future acquisitions within the anticipated timing or at all, our business, financial condition and results of operations may be adversely affected.
If we do not appropriately maintain effective internal control over financial reporting in accordance with Section 404 of the Sarbanes-Oxley Act of 2002, we may
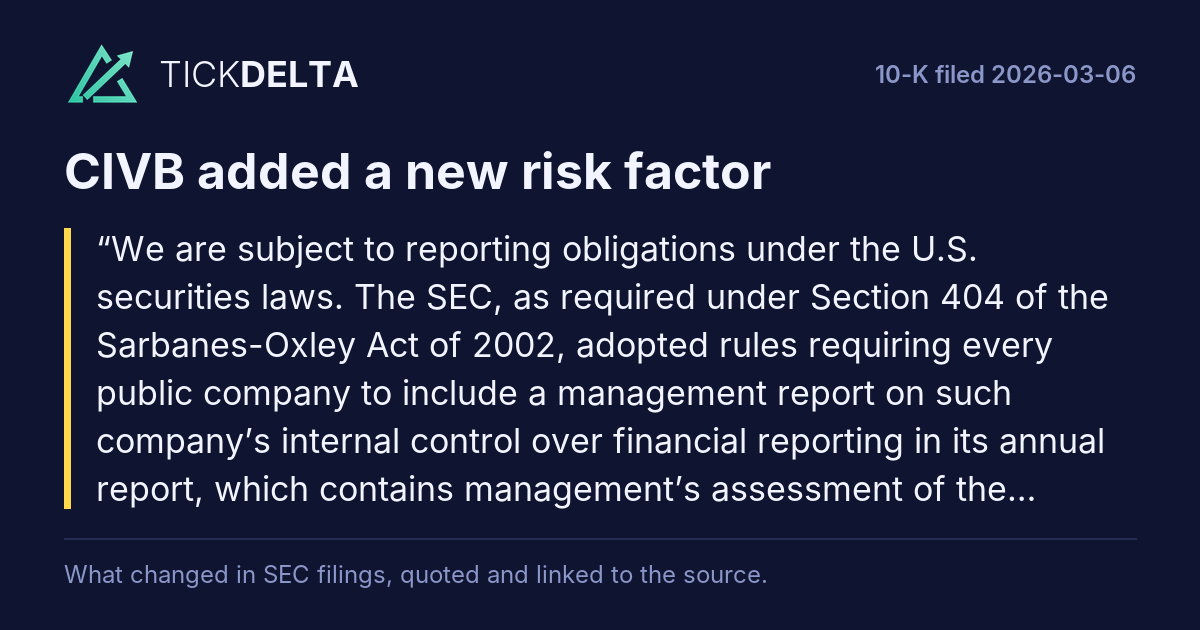
We are subject to reporting obligations under the U.S. securities laws. The SEC, as required under Section 404 of the Sarbanes-Oxley Act of 2002, adopted rules requiring every public company to include a management report on such company’s internal control over financial reporting in its annual report, which contains management’s assessment of the effectiveness of the company’s internal control over financial reporting. Such internal controls are designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles.
During 2024 and 2025, we made the decision to make greater investments in our finance department, which included the hiring of a Chief Financial Officer. During that period, we experienced turnover in our accounting and financial reporting staff and function, which was addressed by making further investments in talent. We continued to integrate our more recent acquisition such as CLF, a division of Civista Bank, which we acquired in the fourth quarter of 2022. During 2025, we implemented a conversion of CLF’s legacy software system to a new core operating system, which resulted in the recognition of certain one-time nonrecurring items in our financial statements for the second quarter of 2025. As we continue to grow our business, implement our strategic plan and integrate any businesses we acquire, such as FSB, we may continue to seek to enhance our talent, policies and procedures across the Company, which may result in changes to and enhancements and remediation of certain of our internal controls, including our internal control over financial reporting. If we fail to maintain effective internal control over financial reporting in the future, our management and our independent registered public accounting firm may not be able to conclude that we have effective internal control over financial reporting at a reasonable assurance level. Similarly, if any material weaknesses in the Company’s internal controls are identified in the future and are not fully remediated, those material weaknesses could cause the Company to be unable to accurately report its financial results, reduce the market’s confidence in its financial statements, negatively impact the trading price of our securities and subject the Company to sanctions or investigations by the SEC or other regulatory authorities. In addition, the Company’s common shares may not be able to remain quoted on The Nasdaq Capital Market or any other securities quotation service or exchange.
As of December 31, 2025, management concluded that the Company maintained effective internal controls over financial reporting and that no material weaknesses were identified.
New in the latest 10-Q
16 paragraphs in the 10-Q filed Nov 5, 2026 with nothing like them in the 10-Q filed Aug 6, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.
Shares Earnings Shares Loss Equity Net Income — — 16,019 — — 16,019 Other comprehensive income (loss) — — — — (24,278) (24,278) Stock-based compensation — 175 — — — 175 Common stock dividends — — (3,743) — — (3,743)
Read in the 10-Q
Financial Statement presentation/reclassification change: Beginning in the third quarter of 2026, the Company revised the presentation of certain components of noninterest income to better reflect the nature of its mortgage banking and leasing activities. Mortgage-related income is now presented within “Mortgage banking,” while lease-related income is presented within “Leasing and commercial finance revenue.” All amounts previously presented within “Net gain (loss) on sale of loans and leases” have been reclassified to these respective categories. Mortgage banking income includes loan servicing fee income, mortgage servicing rights amortization, the gain or loss on mortgage banking derivatives, and the gain or loss on sale of mortgage loans. Leasing and commercial finance revenue includes revenue associated with sales-type, direct financing, and operating lease activity, as well as gain or loss on the sale of commercial loans and leases. Prior-period amounts have been reclassified to conform to the current-period presentation. These reclassifications had no effect on total noninterest income or net income.
Read in the 10-Q
(5) Allowance for Credit Losses The following tables present, by portfolio segment, the changes in the allowance for credit losses ("ACL") for the three and nine months ended September 30, 2026. Allowance for credit losses: For the three months ended September 30, 2026 Beginning balance Charge-offs Recoveries Provision Ending Balance ───────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────── Commercial & Agriculture $ 7,324 $ (1,655) $ 375 $ (1,250) $ 4,794 Commercial Real Estate: Owner Occupied 4,361 - 6 197 4,564 Non-Owner Occupied 10,665 - 959 476 12,100 Residential Real Estate 14,102 (17) 34 1,068 15,187 Real Estate Construction 3,840 - - 264 4,104 Farm Real Estate 226 - - 5 231 Lease Financing Receivables 959 - 183 38 1,180 Consumer and Other 236 (26) 2 25 237 Total $ 41,713 $ (1,698) $ 1,559 $ 823 $ 42,397 For the nine months ended September 30, 2026 Beginning balance Charge-offs Recoveries Provision Ending Balance ────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────── Commercial & Agriculture $ 5,153 $ (1,753) $ 471 $ 923 $ 4,794 Commercial Real Estate: Owner Occupied 4,420 - 9 135 4,564 Non-Owner Occupied 12,118 (484) 961 (495) 12,100 Residential Real Estate 14,718 (47) 68 448 15,187 Real Estate Construction 3,842 - - 262 4,104 Farm Real Estate 279 - - (48) 231 Lease Financing Receivables 1,169 (348) 227 132 1,180 Consumer and Other 321 (46) 13 (51) 237 Total $ 42,020 $ (2,678) $ 1,749 $ 1,306 $ 42,397 For the three and nine months ended September 30, 2026, the Company provided $823 and $1,306, respectively, to the allowance for credit losses. The Company experienced an increase in the allowance for credit losses primarily due to an increase in the loan portfolio. The provision recorded in the three months ended September 30, 2026 in the Commercial & Agriculture portfolio was reduced due to the decrease in quantitative factors due to an improved loss given default forecast. The charge-offs for the Commercial & Agriculture portfolio mainly consisted of one charge-off that had a specific reserve and did not impact the provision. The increased provision in the Residential Real Estate portfolio was due to a growth in loan balances. The Company experienced a large charge-off during the three months ended September 30, 2026 in one commercial relationship and two large recoveries from two different commercial relationships.
Read in the 10-Q
Unrealized Defined Cashflow Hedge (a) Total (a) Unrealized Defined Cashflow Hedge (a) Total (a)
Read in the 10-Q
Activity for mortgage servicing rights ("MSRs") for the three and nine months ended September 30, 2026 and September 30, 2025 was as follows: Three Months Ended September 30, Nine Months Ended September 30, 2026 2025 2026 2025 ───────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────── Mortgage Servicing Rights: Balance at Beginning of Period $ 2,554 $ 2,775 $ 2,683 $ 2,877 Additions 12 41 66 89 Additions from acquisition - - - - Disposals - - - - Amortized to expense (84) (78) (267) (228) Other charges - - - - Change in valuation allowance - - - - Balance at End of Period $ 2,482 $ 2,738 $ 2,482 $ 2,738 There was no valuation allowance for the three and nine months ended September 30, 2026 and September 30, 2025. Estimated amortization expense for each of the next five years and thereafter is as follows: MSRs Core deposit Total
Read in the 10-Q
Mortgage banking derivative: Residential mortgage loans with locked interest rates to be sold in the secondary market and forward commitments for the future delivery of mortgage loans to third-party investors and forward mortgage-backed securities contracts are considered derivatives. Fair values are estimated based on observable changes in the mortgage interest rates from the date of the commitment and do not typically involve significant judgments by management (Level 2).
Read in the 10-Q
The Company presents non-designated derivative positions gross on the Consolidated Balance Sheets for customers and net for financial institution counterparty positions subject to master netting arrangements. The fair value on the asset side was reduced by the margin call adjustment per the Company's netting arrangement in the amounts of $9,020 and $2,180 as of September 30, 2026 and December 31, 2025, respectively.
Read in the 10-Q
of loans as well as selling forward mortgage-backed securities contracts. Loan interest rate lock commitments generally have fixed expiration dates or other termination clauses and may require payment of a fee. Since many of the commitments are expected to expire without being drawn upon, the total commitment amounts do not necessarily represent future cash requirements. The notional amount of these commitments at September 30, 2026 was $21,333. Commitments to originate residential mortgage loans held-for-sale and forward commitments to sell residential mortgage loans are considered derivative instruments not designated as hedging instruments. Mortgage banking derivatives are recorded at fair value and recorded in other assets on the Consolidated Balance Sheets. Fair values are estimated based on observable changes in mortgage interest rates from the date of the commitment. Changes in the fair value are recognized directly in earnings and recorded in mortgage banking in the consolidated statements of operations.
Read in the 10-Q
Most leases include one or more options to renew. The exercise of lease renewal options is typically at our sole discretion. Renewals to extend the lease terms are only included in our ROU assets and lease liabilities when it is reasonably certain they will be exercised.
Read in the 10-Q
As most of our leases do not provide an implicit rate, we use the fully collateralized FHLB borrowing rate, commensurate with the lease terms based on the information available at the lease commencement date in determining the present value of the lease payments.
Read in the 10-Q
The balance sheet information related to our operating leases were as follows as of September 30, 2026 and December 31, 2025:
Read in the 10-Q
Classification on the Consolidated Balance Sheet September 30, 2026 December 31, 2025
Read in the 10-Q
The Company conducts its operations through one single business segment, which is determined by the Chief Financial Officer, who is the designated chief operating decision maker ("CODM").
Read in the 10-Q
Loans outstanding as of September 30, 2026 and December 31, 2025 were as follows:
Read in the 10-Q
Beginning in the third quarter of 2026, the Company revised the presentation of certain components of noninterest income to better reflect the nature of its mortgage banking and leasing activities. Mortgage-related income is now presented within “Mortgage banking,” while lease-related income is presented within “Leasing and commercial finance revenue.” All amounts previously presented within “Net gain (loss) on sale of loans and leases” have been reclassified to these respective categories. Mortgage banking income includes loan servicing fee income, mortgage servicing rights amortization, the gain or loss on mortgage banking derivatives, and the gain or loss on sale of mortgage loans. Leasing and commercial finance revenue includes revenue associated with sales-type, direct financing, and operating lease activity, as well as gain or loss on the sale of commercial loans and leases. Prior-period amounts have been reclassified to conform to the current-period presentation. These reclassifications had no effect on total noninterest income or net income.
Read in the 10-Q
increased $1,290 for the nine months ended September 30, 2026, compared to the same period of 2025, mainly due to higher lease origination activity in 2026, partially offset by the non-recurring adjustment noted above.
Read in the 10-Q
Item 1A of the 10-Q filed Nov 5, 2026 against Item 1A of the 10-K filed Mar 6, 2026.
A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed.
Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed,
Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal
(cut words struck through, new words highlighted).
Text on the page, not a score; each links to the filing at sec.gov.
What the 10-Q itself says about its risk factors:There were no material changes during the current period to the risk factors previously disclosed under “Item 1A. Risk Factors” of Part I of the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2025, as supplemented by the disclosures under "Item 1A. Risk Factors" of Part II of the Company's Quarterly Report on Form 10-Q for the fiscal quarter ended March 31, 2026.
Read in the 10-Q
Two-word phrases in Risk Factors of the 10-K filed Mar 6, 2026 that are in none of the 1 earlier 10-Ks stored, back to Mar 10, 2025
Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.
5 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.
Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.
10-K change: what was reworded or cut, section by section.
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/CIVB/export.csv") into a cell.