Form 10-K for the Year Ended December 31, 2021
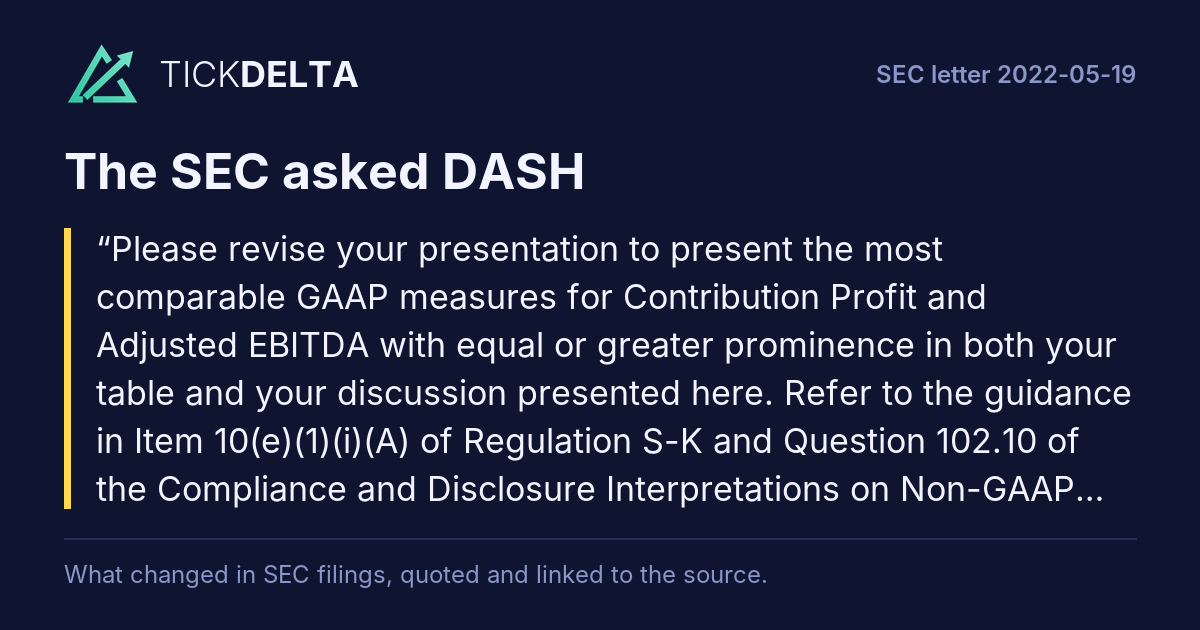
Please revise your presentation to present the most comparable GAAP measures for Contribution Profit and Adjusted EBITDA with equal or greater prominence in both your table and your discussion presented here. Refer to the guidance in Item 10(e)(1)(i)(A) of Regulation S-K and Question 102.10 of the Compliance and Disclosure Interpretations on Non-GAAP Measures.
The Company acknowledges the Staff’s comment and respectfully advises the Staff that in future filings the Company will present any Non-GAAP financial measures along with the most directly comparable GAAP measures with equal or greater prominence consistent with Item 10(e)(1)(i)(A) of Regulation S-K and Question 102.10 of the Compliance and Disclosure Interpretations on Non-GAAP
Measures. Read in the reply ↗
First report after the company's reply of 2022-06-03: 10-Q filed 2022-08-05 ↗, against the 10-Q filed 2022-05-06 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
We note that all of your Non-GAAP measures presented here, except for Adjusted EBITDA, include an adjustment for "Allocated Overhead." Overhead appears to include normal, recurring, cash operating expenses necessary to operate your business. Please tell us why you believe these adjustments are permitted under Rule 100(b) of Regulation G.Rest of the question
Refer to Question 100.01 of the Compliance and Disclosure Interpretations on Non-GAAP Measures.
The Company respectfully advises the Staff that, prior to preparing and including any non-GAAP measures in its Form 10-K, it reviewed the requirements of Rule 100(b) of Regulation G and the guidance in the Compliance and Disclosure Interpretations, including Question 100.01. The Company has further reviewed the rule and related guidance, and based upon such review, does not believe that the adjustments for allocated overhead violate Rule 100(b) of Regulation G.Read in the reply ↗Rest of the answer
The non-GAAP financial measures that adjust for allocated overhead, when considered with the information and other accompanying discussion of the Company’s GAAP and non-GAAP financial measures, do not contain an untrue statement of a material fact nor omit a material fact necessary in order to make the presentation of its non-GAAP financial measures, in light of the circumstances in which they are presented, not misleading.
As described in the Form 10-K, allocated overhead is determined based on an allocation of shared costs, such as facilities (including rent and utilities) and information technology costs, among all departments based on employee headcount. These costs tend to be fixed in nature and are not directly impacted by Total Orders or revenue. While allocated overhead is excluded from adjusted cost of revenue, adjusted sales and marketing expense, and adjusted research and development expense, all such excluded allocated overhead amounts have been included in adjusted general and administrative expense, in addition to any amounts that would otherwise be included in general and administrative expense. The purpose of these adjustments is to shift allocated overhead, which, as noted, is generally a fixed cost, to a category of operating expense that is also typically fixed in nature and does not tend to be sensitive to changes in Total Orders or revenue. Further, it permits investors to evaluate shared costs, such as facilities, which are incurred by the Company in the aggregate, on an aggregate basis and not divided among functions in a way that may vary from period to period. The Company believes that this presentation appropriately represents, and is more meaningful to an investor’s understanding of, the
Company’s business and performance, particularly its unit economics and its fixed costs.
Page
The Company further advises the Staff that it presents adjusted cost of revenue, adjusted sales and marketing expense, and adjusted research and development expense excluding allocated overhead because it believes that such presentation provides investors with important insights into the Company’s performance and provides comparability of the Company’s variable costs over various periods. As allocated overhead is not directly impacted by changes in Total Orders or revenue, excluding it from the foregoing non-GAAP measures enables investors to better understand the relationship of changes in Total Orders and revenue on the Company’s cost structure, and thereby provides investors with further insight on the unit economics of the Company’s business.
Additionally, separating out allocated overhead provides investors with incremental clarity on such fixed costs. Therefore, the Company believes that it is appropriate to exclude allocated overhead in the determinations of the foregoing non-GAAP measures as changes to allocated overhead are not necessarily reflective of the Company’s unit economics. Further, the Company believes that providing these non-GAAP financial measures with adjustments for allocated overhead enhances its overall financial disclosure and provides context within which its GAAP financial information should be analyzed.
The Company further submits that its treatment of allocated overhead in its presentation of non-GAAP measures in the Form 10-K is reflective of how management views and operates the Company’s business. The Company’s management focuses on how variable costs, Total Orders, and revenue vary from period to period, and the relationship between its variable costs, Total Orders, and revenue, and has presented these adjustments to allocated overhead to enable investors to see the Company’s business through management’s eyes.
Lastly, the Company further notes for the Staff that the amounts of allocated overhead excluded from adjusted cost of revenue, adjusted sales and marketing expense, and adjusted research and development expense and added to adjusted general and administrative expense have historically not been material, either individually or in the aggregate. For example, in the year ended
December 31, 2021, allocated overhead represented:
•
$25 million, or approximately 1% of cost of revenue;
$14 million, or less than 1% of sales and marketing expense;
$13 million, or approximately 3% of research and development expense; and
$11 million, or approximately 1% of general and administrative expense.
For all of the foregoing reasons, the Company believes that certain non-GAAP financial measures that adjust for allocated overhead are useful to investors, provide meaningful additional disclosure for investors, and are permitted under Rule 100(b) of Regulation G.
First report after the company's reply of 2022-06-03: 10-Q filed 2022-08-05 ↗, against the 10-Q filed 2022-05-06 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: closing letter, 2022-06-13