Screener / SEC EDGAR /CIK 0001467623 /10-K filed Feb 20, 2026, compared with Feb 21, 2025 /Numbers from the XBRL of the 10-Ks
Nasdaq Technology · Software

Dropbox, Inc. DBX

Compare with peers Embed
New in the 10-K 9 paragraphs with nothing like them in the 10-K filed Feb 21, 2025 New in the 10-Q 9 paragraphs not in the 10-Q filed Aug 7, 2026 10-Q against the 10-K 42 risk factor paragraphs and sentences added or reworded

New risk paragraphs, branching off last year

Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Feb 21, 2025. A box jumps to the paragraph as filed, below.

9 new

Paragraphs with nothing like them in last year's 10-K

Quoted exactly

9 paragraphs in Risk Factors of the 10-K filed Feb 20, 2026 with nothing like them in the 10-K filed Feb 21, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.

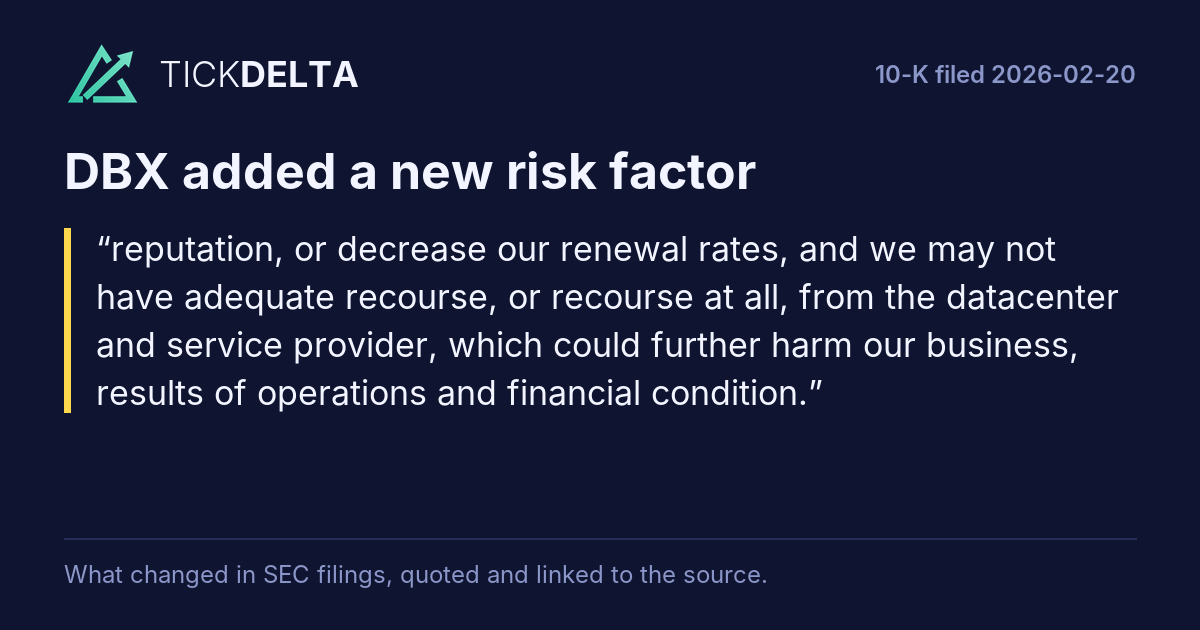
reputation, or decrease our renewal rates, and we may not have adequate recourse, or recourse at all, from the datacenter and service provider, which could further harm our business, results of operations and financial condition.

Read in the 10-K

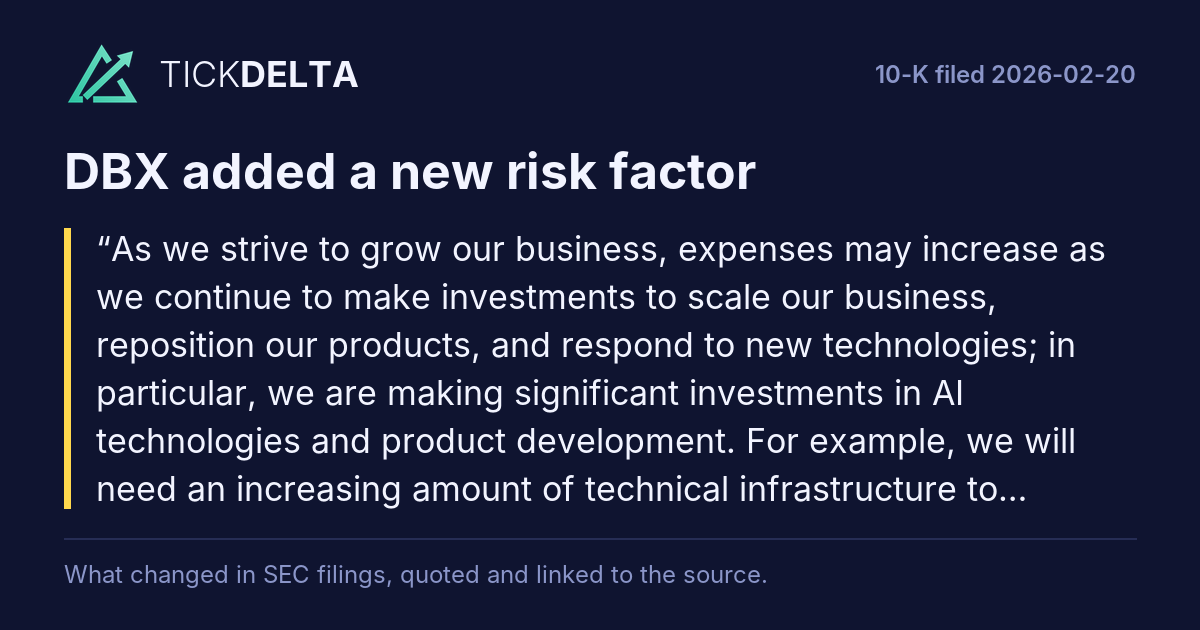
As we strive to grow our business, expenses may increase as we continue to make investments to scale our business, reposition our products, and respond to new technologies; in particular, we are making significant investments in AI technologies and product development. For example, we will need an increasing amount of technical infrastructure to continue to satisfy the needs of our user base. Our research and development expenses may also increase as we plan to continue to hire

Read in the 10-K

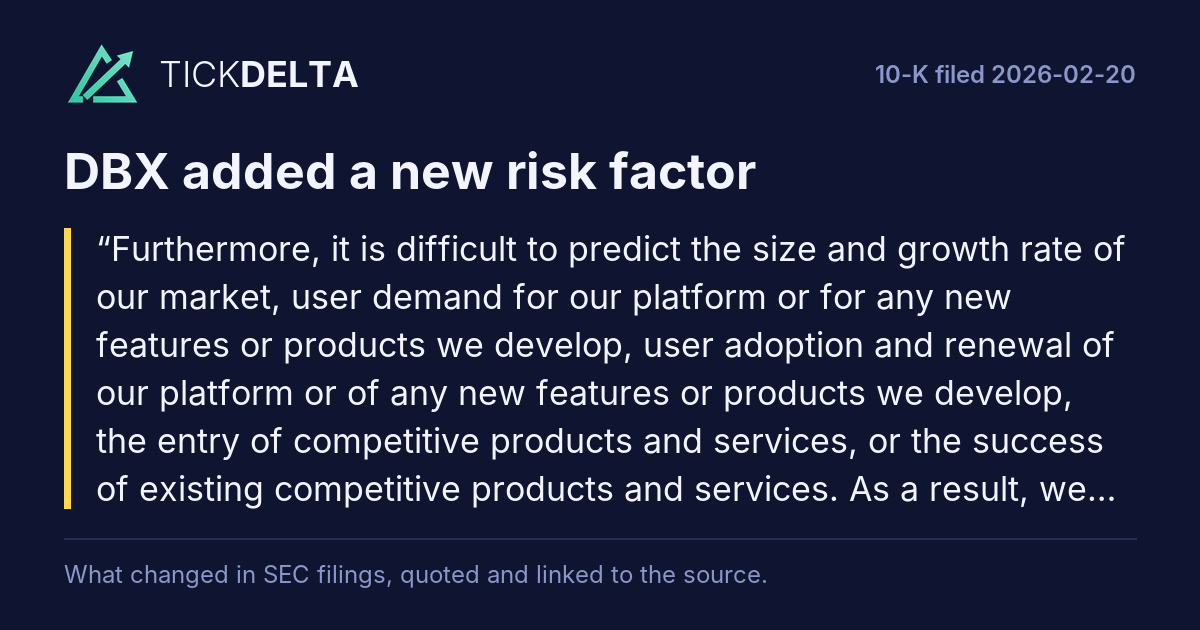
Furthermore, it is difficult to predict the size and growth rate of our market, user demand for our platform or for any new features or products we develop, user adoption and renewal of our platform or of any new features or products we develop, the entry of competitive products and services, or the success of existing competitive products and services. As a result, we may not achieve or maintain profitability in future periods, or we may not otherwise achieve our goals related to profitability. If we fail to grow our revenue sufficiently to keep pace with our investments and other expenses, our results of operations and financial condition would be adversely affected.

Read in the 10-K

For example, on July 4, 2025, tax legislation commonly known as the One Big Beautiful Bill Act (the "OBBBA") was enacted in the United States. The OBBBA includes significant provisions, such as the permanent extension of certain expiring provisions of the Tax Cuts and Jobs Act, modifications to the international tax framework and the restoration of favorable tax treatment for certain business provisions. The legislation has multiple effective dates, with certain provisions effective in 2025 and others implemented through 2027. OBBBA reduced our U.S. cash tax payments in 2025 but increased tax expense, primarily due to limits to the availability of certain credits and deductions resulting from the reinstatement of immediate expensing for U.S. research expenditures. The issuance of future regulatory or accounting guidance related to OBBBA may adversely affect our tax provision.

Read in the 10-K

With respect to the Motion Offense Litigation, a jury trial was conducted in May 2023. The jury found in favor of Dropbox on all counts including non-infringement and invalidity of the patents and awarded no damages to Motion Offense. In August 2024, the court entered judgment in line with the May 2023 jury verdict. A decision on post-trial briefing is currently pending. The final judgment may be appealed to the Federal Circuit.

With respect to the Entangled Media Litigation, trial is currently set for September 8, 2026. Any final judgment in the district court may be appealed by either party to the Federal Circuit.

Read in the 10-K
Show the other 3

•actual sales or announcements of sales of shares of our Class A common stock by us or our stockholders;

Read in the 10-K

Beginning December 1, 2025, holders of the 2026 Notes have the right to convert all or any portion of their 2026 Notes at any time prior to the close of business on the second scheduled trading day immediately preceding March 1, 2026, the maturity date of the 2026 Notes.

Read in the 10-K

We do not intend to pay dividends or other distributions for the foreseeable future.

Read in the 10-K

Paragraphs in the 10-Q filed Nov 6, 2026 that were not in the one before

New in the latest 10-Q

9 paragraphs in the 10-Q filed Nov 6, 2026 with nothing like them in the 10-Q filed Aug 7, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.

Financial statements and notes

On November 3, 2026, the Company entered into a definitive agreement to acquire Tigris Data Inc. (“Tigris”), a globally distributed object storage platform built for AI workloads, for cash consideration of approximately $ 350.0 million, subject to customary purchase price adjustments. The Company expects this acquisition to enhance its platform services and advance its acceleration into commercial infrastructure. The acquisition is expected to close during the fourth quarter of 2026, subject to the satisfaction or waiver of certain customary closing conditions.

Read in the 10-Q

On October 28, 2026, the Company announced a reduction of its global workforce by approximately 9 % to align the Company’s investments and team structure with its top product and growth priorities and support its long-term strategy. The Company estimates that it will make total cash expenditures of approximately $ 27 million to $ 33 million, primarily consisting of severance payments, employee benefits, and related costs. Severance payments include the pro rata portion of the fiscal year 2026 annual employee bonus through October 28 2026, for which the Company has accrued compensation expense through September 30, 2026. The Company expects to recognize approximately $ 20 million to $ 25 million of incremental expense in connection with the reduction in workforce. The Company expects substantially all of the incremental expense to be recognized, and a majority of the cash expenditure to be paid in the fourth quarter of 2026, with the remainder expected to be recognized and paid in 2027. The estimated cash expenditures and incremental expenses are based on certain assumptions, including local law requirements in various jurisdictions, and actual amounts may differ materially from such estimates.

Read in the 10-Q

The Company may incur other incremental expenses or cash expenditures not currently contemplated due to unanticipated events that may occur as a result of or in connection with the implementation of the reduction in workforce.

Read in the 10-Q

During the three and nine months ended September 30, 2026, we outperformed expectations, primarily driven by self-serve Teams growth from simplified pricing and packaging and continued strength in our Individuals plans, reflecting the durability of our core business and robust free cash flow generation. As we advance our recently announced DBX Agent Cloud infrastructure offering, we remain disciplined in scaling investment in step with results, while continuing to expand operating margin.

Read in the 10-Q

On October 28, 2026, we announced an additional reduction of our global workforce by approximately 9% to align our investments and team structure with our top product and growth priorities and support our long-term strategy (together with the second and third quarter 2026 reductions in workforce, the "2026 reductions in workforce"). Refer to Note 15. "Subsequent Events" for additional information.

Read in the 10-Q
Show the other 4

As of Constant Currency September 30, 2026 December 31, 2025 September 30, 2025 (In millions) Total ARR $2,555 $2,562 $2,572

Read in the 10-Q

Our FCF decreased for the nine months ended September 30, 2026, compared to the nine months ended September 30, 2025, primarily due to a decrease in cash provided by operating activities, reflecting higher interest payments associated with borrowings under our term loan facility, which is fully drawn.

Read in the 10-Q

Risk Factors

users. Moreover, public announcements concerning any cybersecurity-related incidents and steps we may take to respond to or remediate any such incidents could be perceived by securities analysts or investors to be negative, and such perception could, among other things, have an adverse effect on the price of our Class A common stock.

Read in the 10-Q

This law aims to establish a universal framework for managing and mitigating information and communication technology risks that will apply to entities in the financial sector and their third-party cloud service providers.

Read in the 10-Q

The 10-Q's risk factors against the 10-K

Item 1A of the 10-Q filed Nov 6, 2026 against Item 1A of the 10-K filed Feb 20, 2026. A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed. Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed, Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal (cut words struck through, new words highlighted). Text on the page, not a score; each links to the filing at sec.gov.

Added10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
users. Moreover, public announcements concerning any cybersecurity-related incidents and steps we may take to respond to or remediate any such incidents could be perceived by securities analysts or investors to be negative, and such perception could, among other things, have an adverse effect on the price of our Class A common stock.

Read it in the 10-Q at sec.gov

Added10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
indebtedness will depend on the capital markets and our financial condition at such time. We may not be able to engage in any of these activities or engage in these activities on desirable terms, which could result in a default on our debt obligations, which would materially and adversely impact our business, financial condition and operating results.

Read it in the 10-Q at sec.gov

Added10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
We receive, store, process, and use personal information and other user content. Numerous federal, state, local, and international laws and regulations address privacy (including children's privacy), data protection, information security, and the storing, sharing, use, processing, transfer, disclosure, and protection of personal information and other content, the scope of

Read it in the 10-Q at sec.gov

Added10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
This law aims to establish a universal framework for managing and mitigating information and communication technology risks that will apply to entities in the financial sector and their third-party cloud service providers.

Read it in the 10-Q at sec.gov

Show the other 14
Reworded10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
Interruptions in our platform might, among other things, reduce our revenue, cause us to issue refunds to users, subject us to potential liability, harm our reputation, or decrease our renewal rates, and we may not have adequate recourse, or recourse at all, from the datacenter and service provider, which could further harm our business, results of operations and financial condition.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
We continue to face risks relating to this incident, including harm to our reputation and customer relationships, and ongoing litigation, in the form of a consolidated class action lawsuit that has been filed in federal court in the Northern District of California, and regulatory scrutiny related to this incident, and we may discover other impacts or new related events may occur that could affect our business operations, financial condition or results of operations.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
A successful assertion by a state, country, or other jurisdiction that we should have been or should be collecting additional sales, use, or other taxes on our services could, among other things, result in substantial tax liabilities for past sales, create significant administrative burdens for us, discourage users from purchasing subscriptions to our platform, or otherwise harm our business, results of operations, and financial condition.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
Computer malware, Malware, ransomware, viruses, social engineering (phishing attacks), (such as phishing), denial of service or service, insider misuse, and other attacks, employee theft or misuse and increasingly sophisticated network attacks have become more prevalent, particularly against cloud cloud-based services.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
Paying users may downgrade or not renew their subscriptions because of several factors, such as dissatisfaction with our products, support, pricing, mix of features (including data storage limits), or user experience, a user no longer having a need for our products, as a result of impacts from our decisions regarding marketing spend and investment focus, including changes in our strategy with respect to, or phase-out of, certain products or features, such as our announcement regarding FormSwift, the availability of competitive products, including products that are, or are perceived to be, less expensive, shifts in the mix of monthly and annual subscriptions or the impact of macroeconomic trends or catastrophic events on our paying users and their willingness or ability to pay for subscriptions.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
We expect that the requirements of these rules and regulations will continue to increase our legal, accounting, and financial compliance costs, make some activities more difficult, time-consuming and costly, and place significant strain on our personnel, systems, and resources.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
We evaluate financing opportunities from time-to-time, and our ability to obtain financing will depend, among other things, on our development efforts, business plans, operating performance, and condition of the capital markets at the time we seek financing.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
If we are unable or are perceived to be unable to comply with any of these regulations, standards, requirements, or other actual or asserted obligations, if we are unable to maintain certifications or standards relevant to our customers, or if our customers are unable to obtain regulatory approval to use our services where required, our business may be harmed.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 20, 2026
Our new product initiatives, including any AI-based initiatives, initiatives and those related to advancing our recently announced DBX Agent Cloud infrastructure offering, are intended to result in growth, but such initiatives require a period of investment and ultimately may not succeed on the timelines we expect or at all.

Read it in the 10-Q at sec.govThe 10-K sentence

The first 19 of 42 are shown (at most 12 of each type).

Phrases used for the first time

Two-word phrases in Risk Factors of the 10-K filed Feb 20, 2026 that are in none of the 1 earlier 10-Ks stored, back to Feb 21, 2025

entangled media ×4malfunctions cyber-attacks ×3cyber-attacks wars ×3offense litigation ×3media litigation ×3experienced negative ×2retaliatory actions ×2limitations provided ×2otherwise submitted ×2nevada revised ×2revised statutes ×2nevada clark ×2directors authorized ×2
Where each one is used
  • entangled media: We own a large number of patents, copyrights, trademarks, domain names, and trade secrets and, from time-to-time, are subject to litigation based on allegations of infringement, misappropriation or other violations of intellectual property, or other rights. As we face increasing competition and gain an increasingly...
  • malfunctions cyber-attacks: •catastrophic events, including earthquakes, fires, floods, tsunamis, or other weather events, power loss, telecommunications failures, software or hardware malfunctions, cyber-attacks, wars, or terrorist attacks, and pandemics;
  • cyber-attacks wars: •catastrophic events, including earthquakes, fires, floods, tsunamis, or other weather events, power loss, telecommunications failures, software or hardware malfunctions, cyber-attacks, wars, or terrorist attacks, and pandemics;
  • offense litigation: We own a large number of patents, copyrights, trademarks, domain names, and trade secrets and, from time-to-time, are subject to litigation based on allegations of infringement, misappropriation or other violations of intellectual property, or other rights. As we face increasing competition and gain an increasingly...
  • media litigation: We own a large number of patents, copyrights, trademarks, domain names, and trade secrets and, from time-to-time, are subject to litigation based on allegations of infringement, misappropriation or other violations of intellectual property, or other rights. As we face increasing competition and gain an increasingly...
  • experienced negative: Our rate of growth has declined and we have experienced negative growth in past periods. If we do not successfully execute our plan for future growth, our growth rate may continue to decline and we may continue to experience negative growth in future periods.
  • retaliatory actions: Further, as we continue to evolve our business to meet the needs of our users, we may overestimate or underestimate our infrastructure capacity requirements, which could adversely affect our results of operations. The costs associated with leasing and maintaining our custom-built infrastructure in co-location...
  • limitations provided: Our Class A common stock has one vote per share, our Class B common stock has ten votes per share, and our Class C common stock has no voting rights, except as otherwise required by law and subject to any limitations provided in our articles of incorporation. As of December 31, 2025, our directors and executive...

The 10-K at sec.gov

Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.

What was taken out

10 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.

Across all companies
For example, the Organization for Economic Cooperation and Development (“OECD”) and many countries have proposed to reallocate some portion of profits of large multinational companies with global revenues exceeding EUR20 billion to markets where sales arise (“Pillar One”), as well as enact a global minimum tax rate of at least 15% for multinationals with global revenue exceeding EUR750 million (“Pillar Two”), and many countries are considering or have begun to adopt these proposals. In December 2022, the Council of the European Union (“EU”) formally adopted the EU Minimum Tax Directive,...
In the 10-K filed Feb 21, 2025
We have experienced periods in which our number of paying users has declined, and our paying and registered user growth rates have declined and may continue to decline in the future as our pricing and packaging strategy and features (including data storage limits) change, our market penetration rates increase, and as a result of market conditions and increasing competition with respect to our current products. The availability of less expensive and bundled competitive products also has negatively impacted and may continue to negatively impact our user growth rate and our ability to convert...
In the 10-K filed Feb 21, 2025
Furthermore, events or conditions that financially impact our registered users and other prospective paying users, such as macroeconomic factors, layoffs, inflation, fluctuating interest rates, or catastrophic events, have in the past caused and may cause in future periods these users to delay or reduce technology spending, which impacted, and may continue to impact our ability to convert registered users or otherwise attract new paying users, restricting our ability to grow our revenue. If we are unable to increase our paying user growth rates or to offset declines in the number of new...
In the 10-K filed Feb 21, 2025
If and when we reincorporate from Delaware to Nevada, our Nevada bylaws will have similar provisions regarding forum for adjudication of disputes except that where our current bylaws specify the Court of Chancery of the State of Delaware, our bylaws following our planned reincorporation in Nevada will specify the Eighth Judicial District Court of the State of Nevada, in Clark County, Nevada.
In the 10-K filed Feb 21, 2025

Sources

Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.

Also

10-K change: what was reworded or cut, section by section.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/DBX/export.csv") into a cell.

Next:10-K change
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.