Enterprise Financial Services Corp EFSC
New risk paragraphs, branching off last year
Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Feb 28, 2025. A box jumps to the paragraph as filed, below.
Paragraphs with nothing like them in last year's 10-K
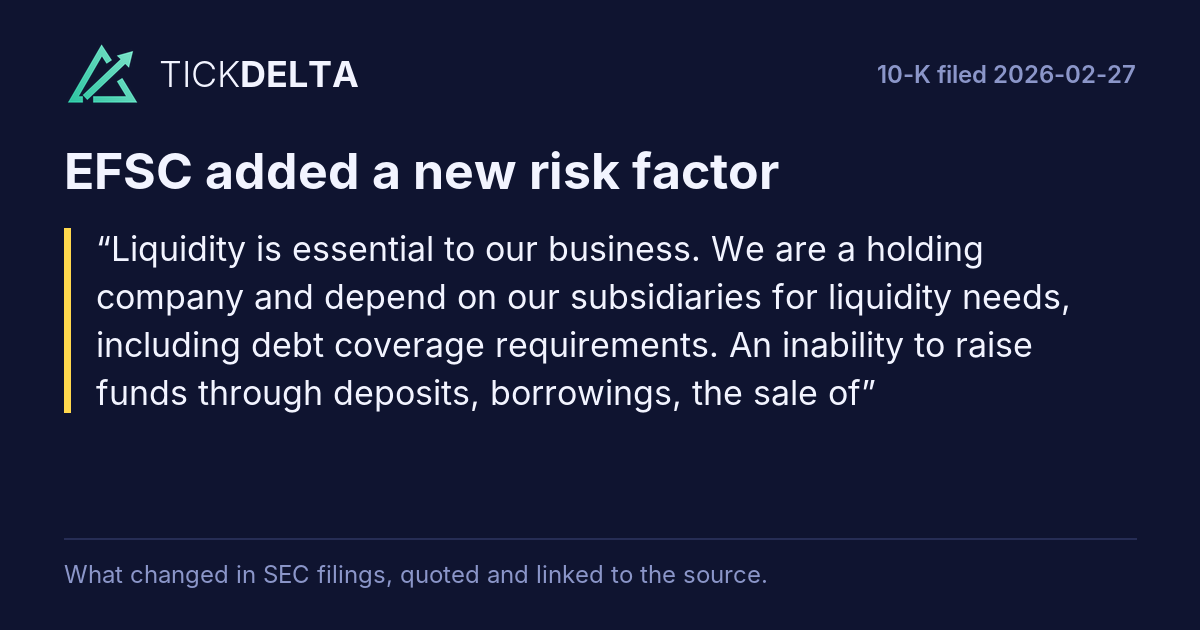
1 paragraph in Risk Factors of the 10-K filed Feb 27, 2026 with nothing like it in the 10-K filed Feb 28, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.
Liquidity is essential to our business. We are a holding company and depend on our subsidiaries for liquidity needs, including debt coverage requirements. An inability to raise funds through deposits, borrowings, the sale of
Paragraphs in the 10-Q filed Oct 30, 2026 that were not in the one before
New in the latest 10-Q
5 paragraphs in the 10-Q filed Oct 30, 2026 with nothing like them in the 10-Q filed Jul 31, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.
Financial statements and notes
($ in thousands) Net Unrealized Loss on Available-for-Sale Securities Unamortized Gain on Held-to-Maturity Securities Net Unrealized Gain (Loss) on Cash Flow Hedges Total
Read in the 10-Q
($ in thousands) Net Unrealized Gain (Loss) on Available-for-Sale Debt Securities Unamortized Gain on Held-to-Maturity Securities Net Unrealized Gain (Loss) on Cash Flow Hedges Total
Read in the 10-Q
On August 22, 2026, the Company exercised its option to redeem $ 7,732,000 of its outstanding 10.20 % fixed rate junior subordinated deferrable interest debentures originally due February 22, 2031 (the “Debentures”) held by Jefferson County Statutory Trust I (“JEFFCO Stat Trust I”) pursuant to the terms of the Debentures. In addition to the principal redemption, the Company paid $ 394,332 of accrued but unpaid interest as of the redemption date. The redemption was funded with a portion of the net proceeds from the Company's issuance of fixed-to-floating rate subordinated notes due 2036, which was completed during the second quarter of 2026. The Debentures were carried at face value with no unamortized debt issuance costs, discounts or premiums. Accordingly, no gain or loss on extinguishment was recognized.
Read in the 10-Q
The redemption proceeds received by JEFFCO Stat Trust I were used to redeem $ 7,500,000 of trust preferred securities held by third parties and $ 232,000 of common securities held by the Company.
Read in the 10-Q
Compared to the prior year-to-date period, the decrease was primarily driven by the $32.1 million in accrued insurance proceeds that are anticipated to be received as a result of the recaptured tax credits recognized in the prior year-to-date period that did not reoccur, and a $11.5 million decrease in tax credit income.
Read in the 10-Q
The 10-Q's risk factors against the 10-K
Item 1A of the 10-Q filed Oct 30, 2026 against Item 1A of the 10-K filed Feb 27, 2026.
A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed.
Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed,
Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal
(cut words struck through, new words highlighted).
Text on the page, not a score; each links to the filing at sec.gov.
What the 10-Q itself says about its risk factors:For information regarding risk factors affecting the Company, please see the cautionary language regarding forward-looking statements in the introduction to Item 2 of Part I of this Quarterly Report on Form 10-Q, and Part I, Item 1A of our Report on Form 10-K for the fiscal year ended December 31, 2025. There have been no material changes to the risk factors described in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025.
Read in the 10-Q
1 paragraph in the 10-Q's Item 1A, and none of them adds, rewords or quietly edits a paragraph of the 10-K's.
Phrases used for the first time
Two-word phrases in Risk Factors of the 10-K filed Feb 27, 2026 that are in none of the 1 earlier 10-Ks stored, back to Feb 28, 2025
Where each one is used
- becomes nonperforming: Our C&I loans and sponsor finance loans are underwritten based primarily on cash flow, profitability and enterprise value of the client and are not fully covered by the value of tangible assets or collateral of the client. Consequently, if any of these transactions becomes nonperforming, we could experience...
- treasury cdfi: We participate in and have previously been an “Allocatee” of the New Markets Tax Credit Program of the Treasury CDFI. Through this program, we provide our allocation to certain projects, which in turn for an equity investment from an investor in the project generate federal tax credits to those investors. This...
Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.
What was taken out
6 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.
Sources
Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.
Also
10-K change: what was reworded or cut, section by section.
Work with it
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/EFSC/export.csv") into a cell.