Company will provide additional disclosure (see bolded additional disclosure) related to Interest Credited to Policyholders. A portion of
Page the disclosure being added to this location, which has also been italicized, was included in the “Market Value Risk” section of the Company’s December 31, 2012
Management’s Discussion and Analysis.
Rest of the answer
The Company also discussed the sensitivity of deferred policy acquisition cost amortization in the “Critical Accounting Policies” section of the Company’s December 31, 2012
Management’s Discussion and Analysis, which is also incorporated in the future filings disclosure below.
Interest Credited to
Policyholders
Year Ended
December 31,
Change From
Prior Year
December
31,
2012
2011
Percent
Amount
2010
Annuity
$121.4
$113.6
6.9%
$7.8
$106.3
Life
42.2
41.3
2.2%
0.9
40.4
Total
$163.6
$154.9
5.6%
$8.7
$146.7
Compared to 2011, the current year increase in annuity segment interest credited reflected a
10.6% increase in average accumulated fixed deposits, partially offset by a 15 basis point decline in the average annual interest rate credited to 3.86%. Compared to 2010, the 2011 increase in annuity segment interest credited reflected a 10.7% increase in average accumulated fixed deposits, partially offset by a 15 basis point decline in the average annual interest rate credited to 4.01%. Life insurance interest credited increased slightly in both 2012 and 2011 as a result of the growth in interest-sensitive life insurance reserves.
The net interest spread on fixed annuity account value on deposit measures the difference between the rate of income earned on the underlying invested assets and the rate of interest which policyholders are credited on their account values. The net interest spreads for the years ended December 31, 2012, 2011 and 2010 were 211 basis points, 202 basis points and 196 basis points, respectively. The net interest spread increases in 2012 and 2011 primarily reflected crediting rate decreases, supplemented by favorable investment yields resulting from the
Company’s investment portfolio management.
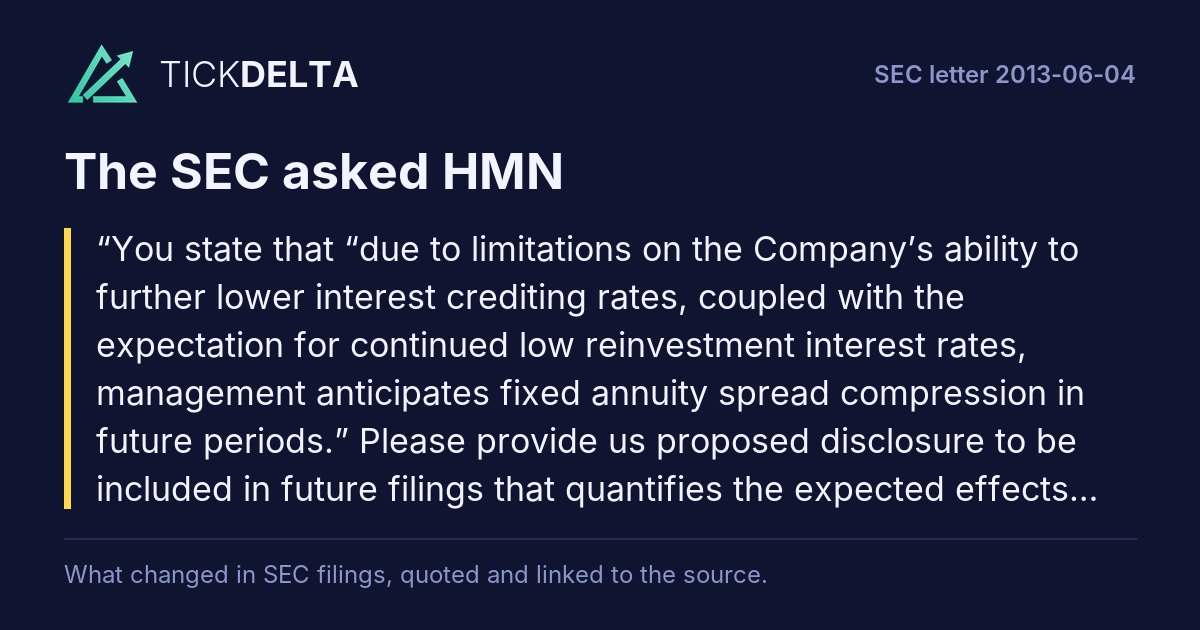
As of December 31, 2012, fixed annuity account values totaled $3.4 billion, including $3.1 billion of deferred annuities. As shown in the table below, for approximately 85%, or $2.6 billion of the deferred annuity account values, the credited interest rate was equal to the minimum guaranteed rate. Due to limitations on the Company’s ability to further lower interest crediting rates, coupled with the expectation for continued low reinvestment interest rates, management anticipates fixed annuity spread compression in future periods. The majority of assets backing the net interest spread on fixed annuity business is invested in fixed-income securities. The Company actively manages its interest rate risk exposure, considering a variety of factors, including earned interest rates, credited interest rates and the relationship between the expected duration of assets and liabilities. Management estimates that approximately $400 million of the December 31, 2012 portfolio and related investable cash flows will be reinvested in 2013. As interest rates remain at low levels, borrowers may prepay or redeem the securities with greater frequency in order to borrow at lower market rates, which could increase investable cash flows and exacerbate the reinvestment risk. As a general guideline, for a 100 basis point decline in the average reinvestment rates and based on the
Company’s existing policies and investment portfolio as of December 31, 2012, the impact from investing in that lower interest rate environment could further reduce annuity segment net investment income by approximately $1.9 million and
$5.7 million in 2013 and 2014, respectively, further reducing the net interest spread by approximately 5 basis points and 14 basis points, respectively. The Company also could consider potential changes in rates credited to policyholders, tempered by any restrictions on the ability to adjust policyholder rates due to guaranteed crediting rates.
The expectation for future net interest spreads is also an important component in the amortization of annuity deferred policy acquisition costs. In terms of the sensitivity of this amortization to the net interest spread, based on capitalized annuity policy acquisition costs as of December 31, 2012 and assuming all other assumptions are met, a 10 basis point deviation in the annual targeted interest rate spread assumption would impact amortization between $0.15 million and $0.25 million.
This result may change depending on the magnitude and direction of any actual deviations but represents a range of reasonably likely experience for the noted assumption.
Additional information regarding the interest crediting rates and balances equal to the minimum guaranteed rate for deferred annuity account values as of December 31, 2012 is shown below.
Deferred Annuities at
Total Deferred Annuities
Minimum Guaranteed Rate
Accumulated of Total
Value
Minimum guaranteed interest rates:
Less than 2%
14.0
%
$ 433.8
3.1
$ 82.0
Equal to 2% but less than 3%
9.5
296.4
6.9
181.8
Equal to 3% but less than 4%
16.7
518.1
19.2
503.4
Equal to 4% but less than 5%
57.9
1,802.3
68.5
5% or higher
1.9
60.0
2.3
100.0
$3,110.6
$2,629.5
The Company will continue to be proactive in executing strategies to mitigate the negative impact on profitability of a sustained low interest rate environment. However, the success of these strategies may be affected by the factors discussed in “Item 1A. Risk Factors” and other factors discussed herein.