Form 10-K for the Year Ended June 30, 2021
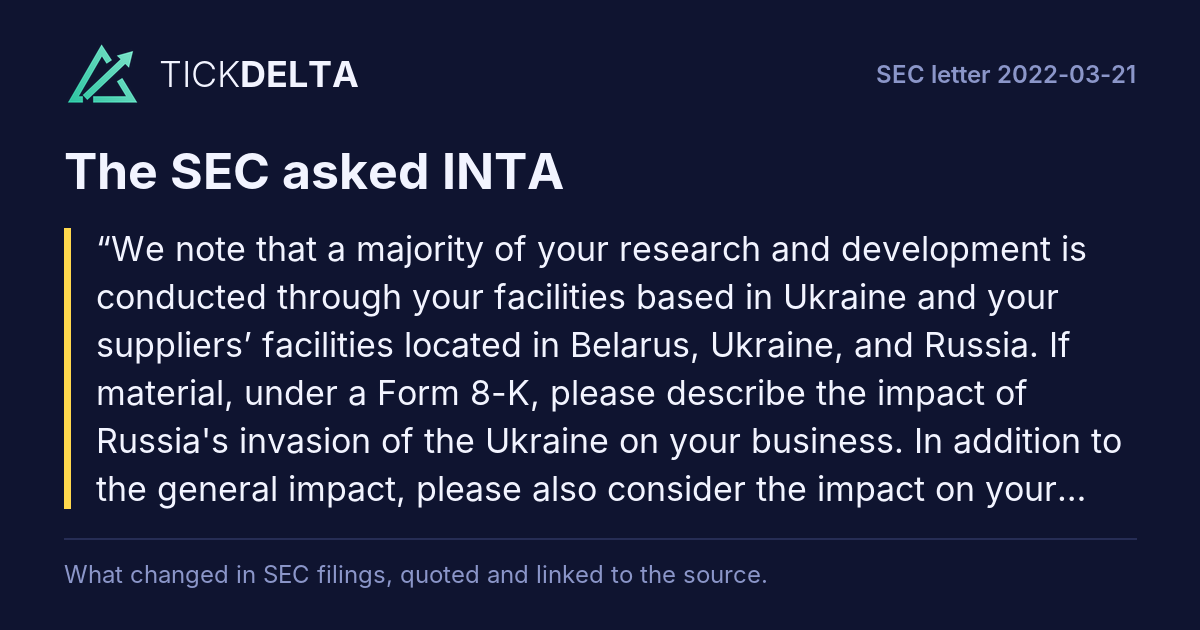
We note that a majority of your research and development is conducted through your facilities based in Ukraine and your suppliers’ facilities located in Belarus, Ukraine, and Russia. If material, under a Form 8-K, please describe the impact of Russia's invasion of the Ukraine on your business.Rest of the question
In addition to the general impact, please also consider the impact on your supply chain based in Belarus, Ukraine and Russia, any impact from sanctions and export controls, and whether you will need to evaluate any aspects of your business for impairment. If the impact is not considered to be material, please tell us why.
The Company respectfully advises the Staff that it does not currently believe that Russia’s invasion of Ukraine has had, or will have, a material impact on its business. The Company is performing an ongoing assessment of the impact of the invasion. As noted in the Company’s public filings, at the time of such filings a majority of its research and development was being conducted through leased facilities based in Ukraine and in third-party facilities located in Belarus, Ukraine, and Russia.Read in the reply
SHEARMAN.COM
Shearman & Sterling LLP is a limited liability partnership organized in the UnitedRest of the answer
States under the laws of the state of Delaware, which laws limit the personal liability of partners.
The Company has implemented contingency plans with respect to its contract research and development teams located in Belarus, Ukraine, and Russia, including relocation of certain resources to other geographic locations and transitioning work previously performed by such resources to other teams outside of the conflict zone.
The Company expects that the majority of its research and development efforts will be conducted outside the conflict zone by the end of fiscal 2022. The implementation of contingency plans with respect to the Company’s research and development teams in Belarus, Ukraine, and Russia has thus far been, and the Company believes will continue to be, accomplished without materially impacting the Company’s ability to support its platform, products and customer needs.
The Company does expect a small increase in research and development spend in fiscal year 2023 over fiscal year 2022 due to increased labor rates and relocation bonuses in connection with relocating resources from Ukraine, Belarus and Russia to other jurisdictions and backfilling positions in other jurisdictions for those not willing or able to relocate. The projected incremental cost as a percentage of the Company’s projected total costs for the applicable period for fiscal years 2022 and 2023 is not expected to be material and is expected to be offset in part by cost reductions in future discretionary spending.
The Company has a small number of customers that have operations in Russia, some of which have closed or severed such operations, and consequently such customers may require fewer licenses of the Company’s products when the contracts come due for renewal. The overall impact to the Company’s revenue with respect to such customers is not expected to be material in either of fiscal years 2022 or 2023.
no impairment charges are expected as its long-lived assets in Ukraine are fully depreciated.
The Company has also analyzed the impact of sanctions and export controls on its business and respectfully advises the Staff that no customers of the Company are sanctioned entities and no material impacts from current sanctions and export controls are expected. The Company plans to continue to monitor the impact of sanctions and exports controls on its business and update its disclosure should the impact on the Company change materially.
As a result of the foregoing, the Company respectfully advises the Staff that it does not believe that further disclosure to investors under a Form 8-K is required at this time.
The Company will continue to monitor the impact of Russia's invasion of Ukraine on its business and will update its disclosure in future reports if its current assessment of such impact changes.
*****
We thank the Staff for its consideration of the
Company’s Form 10-K for the year ended June 30, 2021 and hope the Staff finds that the foregoing answer is responsive to its comment.
If you should have any questions or further comments with respect to the Company’s Form 10-K, please do not hesitate to contact me at (212) 848-4879.
Yours very truly,
/s/ Kristina Trauger
Kristina Trauger cc:
John Hall, Intapp, Inc.
Stephen Robertson, Intapp, Inc.
Steven Todd, Intapp, Inc.
First report after the company's reply of Apr 4, 2022: 10-Q filed May 13, 2022 ↗, against the 10-Q filed Feb 11, 2022 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
We note your forward-looking presentation of Non-GAAP Operating Loss and Non- GAAP Net loss per share. Please disclose and state if true that you omitted a reconciliation to the most comparable GAAP measures in reliance on the “unreasonable efforts” exception in Item 10(e)(1)(i)(B) of Regulation S-K. Further identify the information that is unavailable.Rest of the question
Although you cited the "uncertainty regarding, and the potential variability of, the amounts of stock-based compensation expense and amortization of intangible assets that may be incurred in the future" (page 5), it is unclear how estimating these costs in the near term could require unreasonable efforts. In this regard, we note that your projected non-GAAP operating loss and non-GAAP net loss per share for your fourth fiscal quarter account for a significant portion of your full year outlook for those measures without further explanation by you. Refer to Q&A 102.10 of the C&DI on Non-GAAP Financial Measures and Rule 100(a) and (b) of Regulation G.
to the Staff’s comment that the Company’s projected non-GAAP operating loss and non-GAAP net loss per share for the fourth quarter of fiscal year 2022 accounted for a significant portion of its full year outlook for these measures without further explanation, the Company respectfully advises that this was largely due to the Company’s expectation of a return to pre-COVID levels of marketing expenditure, including in-person marketing events and employee business travel, which were significantly lower than during first half of fiscal year 2022 and prior periods, as well as an increase in theRead in the replyRest of the answer
pace of hiring in the fourth quarter of fiscal year 2022. The Company also had expected certain requisitions for new employee hires to be filled in the fourth quarter of fiscal 2022.
The Company respectfully acknowledges the Staff’s comment and, in future SEC filings, to the extent that it cannot provide the reconciliation to the forward-looking comparable GAAP measures without unreasonable effort, it will disclose that fact as well as the other disclosures required under Q&A 102.10 of the C&DI on Non-GAAP Financial Measures and Rule 100(a) and (b) of Regulation G. Please see below a draft of the disclosure to be included in the
“Outlook” section in future SEC filings:
“The Company has not included a quantitative reconciliation of its guidance for non-GAAP operating loss and non-GAAP net loss per share to their most directly comparable GAAP financial measures because certain of these reconciling items, including stock-based compensation and amortization of intangible assets, could be highly variable and cannot be reasonably predicted without unreasonable effort. This is due to the inherent difficulty of forecasting the timing of certain events that have not yet occurred and are out of the Company’s control and the amounts of associated reconciling items. Please note that the unavailable reconciling items could significantly impact the Company’s GAAP operating results.”
*****
We thank the Staff for its consideration of the Company’s Form 8-K filed on May 11, 2022 and hope the Staff finds that the foregoing answer is responsive to its comment. If you should have any questions or further comments with respect to the Company’s Form 8-K, please do not hesitate to contact me at (212) 848-8414.
Yours very truly,
/s/
Lona Nallengara cc: John Hall, Intapp, Inc.
Stephen Robertson, Intapp, Inc.
Steven Todd, Intapp, Inc.
Yian Huang, Shearman & Sterling LLP
First report after the company's reply of Jul 18, 2022: 10-K filed Sep 9, 2022 ↗, against the 10-K filed Sep 15, 2021 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: closing letter, 2022-08-09