Form 10-K
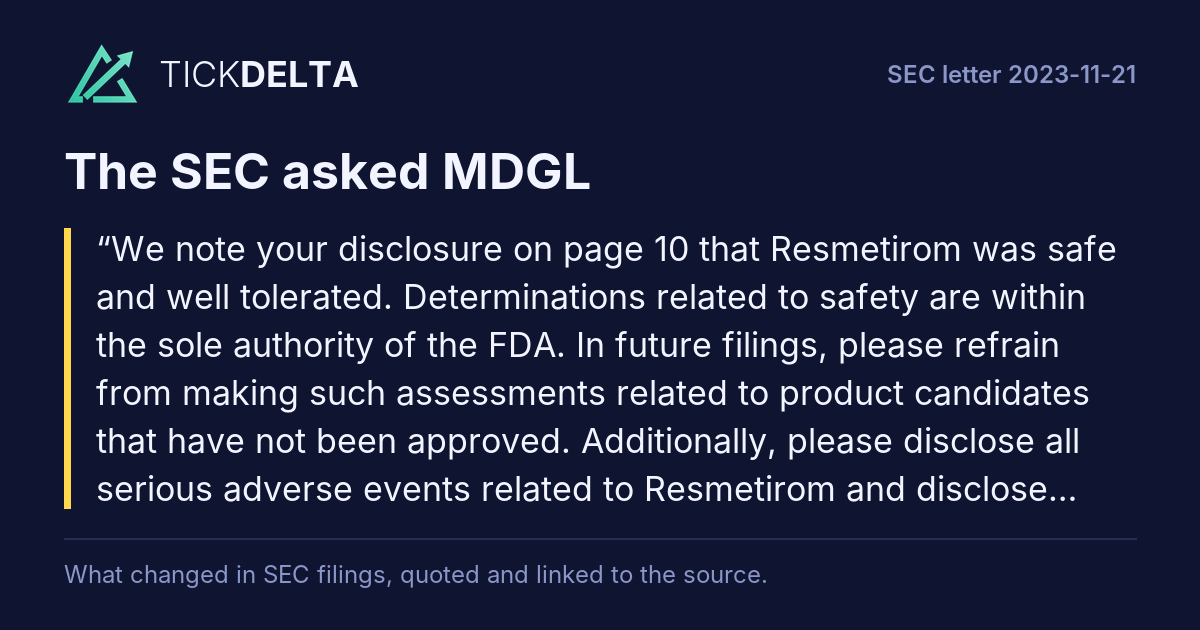
We note your disclosure on page 10 that Resmetirom was safe and well tolerated. Determinations related to safety are within the sole authority of the FDA. In future filings, please refrain from making such assessments related to product candidates that have not been approved. Additionally, please disclose all serious adverse events related to Resmetirom and disclose the number of such events.Rest of the question
Explain how you have determined that the candidate is well tolerated when trial participants experienced serious adverse events.
Madrigal acknowledges the Staff’s comment and advises the Staff that in future reports filed with the SEC, it will refrain from making express statements that resmetirom is safe pending approval by the U.S. FDA, or unless another (e.g. foreign) regulatory authority has made such a safety determination concerning resmetirom (in which case such disclosure would be limited to such context).Read in the reply
(b)
Madrigal acknowledges the Staff’s comment and confirms the referenced disclosure will be updated in our forthcoming Form 10-K to be filed with the SEC concerning any reportable SAE (and number)Rest of the answer
considered related to investigational product.
(c)
Madrigal believes that the referenced disclosure is accurate that resmetirom was well tolerated since treated patients experienced only generally mild and transient diarrhea at the beginning of therapy and generally mild nausea. These are not SAEs related to resmetirom. Based on SEC positions and responses in other life science comment letters, and subject to your review, Madrigal currently plans to continue to make “well tolerated” statements in future filings.
First report after the company's reply of Dec 14, 2023: 10-K filed Feb 28, 2024 ↗, against the 10-K filed Feb 23, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
We note the statement that you expect your research and development expenses will increase substantially in the future. Accordingly for each period presented in future filings, please revise to provide a breakdown of the amount of research and development expense incurred for each of your lead product candidates by program. For product candidates with more than one application, provide a breakdown by indication.Rest of the question
To the extent that you do not track expenses by product candidate, program, or indication, please disclose that fact and explain why you do not maintain and evaluate research and development cost in this manner. For all unallocated research and development expense, provide a breakdown by type or nature of expense such that the sum reconciles to total research and development expense for the period.
The statement made concerning expected increases in future research and development expenses in the Form 10-K was accurate when made. However, for the information of the Staff, Madrigal will evaluate whether it is appropriate to include this statement (or make an adjusted statement for future R&D spend outlook) in future filings.Read in the reply
Madrigal wishes to advise the Staff that it has a single product candidate (resmetirom) and is seeking approval of resmetirom to treat one disease state, NASH, for which there is no currently approved therapeutic in the US or EU.Rest of the answer
See disclosures in the Form 10-K on pages 7, 8 (clinical trials chart describing studies to support use of resmetirom to treat one disease state, NASH), 12, 13 and 64.
Since there is currently not more than one product candidate or program under clinical study for approval,
Madrigal respectfully submits that a breakdown of R&D expenses along the lines suggested in the Staff’s comment is not required. All R&D costs in the Form 10-K for the three year period ending
December 31, 2022 relate to R&D costs for resmetirom to treat NASH patients; the same is true for R&D costs reported in the first through third quarter Forms 10-Q filed during 2023.
(d)
Madrigal further confirms that it had no Unallocated R&D expenses to report in its Form 10-K and does not currently expect to have any such Unallocated R&D expenses in the future.
* * *
If the Staff should have any questions, or would like further information, concerning any of the responses above, please do not hesitate to contact the undersigned at 267 824 2827. We thank you in advance for your attention to the above.
First report after the company's reply of Dec 14, 2023: 10-K filed Feb 28, 2024 ↗, against the 10-K filed Feb 23, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
We note your response to prior comment 2. For each period presented in your financial statements, please revise future MD&A to provide a quantified breakdown of research and development expenses by the type or nature of expense.
The Company confirms that it will prepare future MD&A presentations to provide a quantitative breakdown of R&D expense components by the type or nature of expense for each period presented in such filing, consistent with Item 303(b) of Regulation S-K.Read in the reply
* * *
If the Staff should have any questions, concerning the responses above, please do not hesitate to contact the undersigned at 267 824 2827. We thank you in advance for your attention to this.
First report after the company's reply of Jan 17, 2024: 10-K filed Feb 28, 2024 ↗, against the 10-K filed Feb 23, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: request for more time, Dec 8, 2023, closing letter, 2024-01-25