Screener / SEC EDGAR /CIK 0000789570 /10-K filed Feb 11, 2026, compared with Feb 18, 2025 /Numbers from the XBRL of the 10-Ks
NYSE Consumer discretionary · Hotels

MGM Resorts MGM

Compare with peers Embed
SEC comment letters, last 20 years

2 reviews of MGM's filings by SEC staff

UPLOAD and CORRESP
Reviews 2 latest letter Sep 19, 2022
Questions asked 5 each answered in the company's own letter
No closing letter 0 reviews without a letter saying the staff completed it

When the SEC's staff reviews a filing, it writes to the company with numbered questions, and the company answers each one in a letter. SEC publishes the exchange once the review is over, at least 20 business days later. A question is not an accusation; most reviews end with the company adding detail to its next filing.

How the reviews went

Every review on EDGAR, from the first staff letter to the letter that closes it

  1. 1. Staff letters 3 UPLOAD
  2. 2. Questions in them 5 numbered comments
  3. 3. Company replies 3 CORRESP
  4. 4. Reviews closed 2 of 2 closing letter

Half the closed reviews took 35 days or less from the first letter to the closing letter.

Form 10-K for the Fiscal Year Ended December 31, 2021

2022-09-19 to 2022-09-26 · 2 questions · 1 letter from the SEC, 1 from the company
Review closed 2022-09-26
Non-GAAP measuresKey metrics
Second Quarter 2022 Financial Highlights · Consolidated Results, page 2
SEC asked (1)
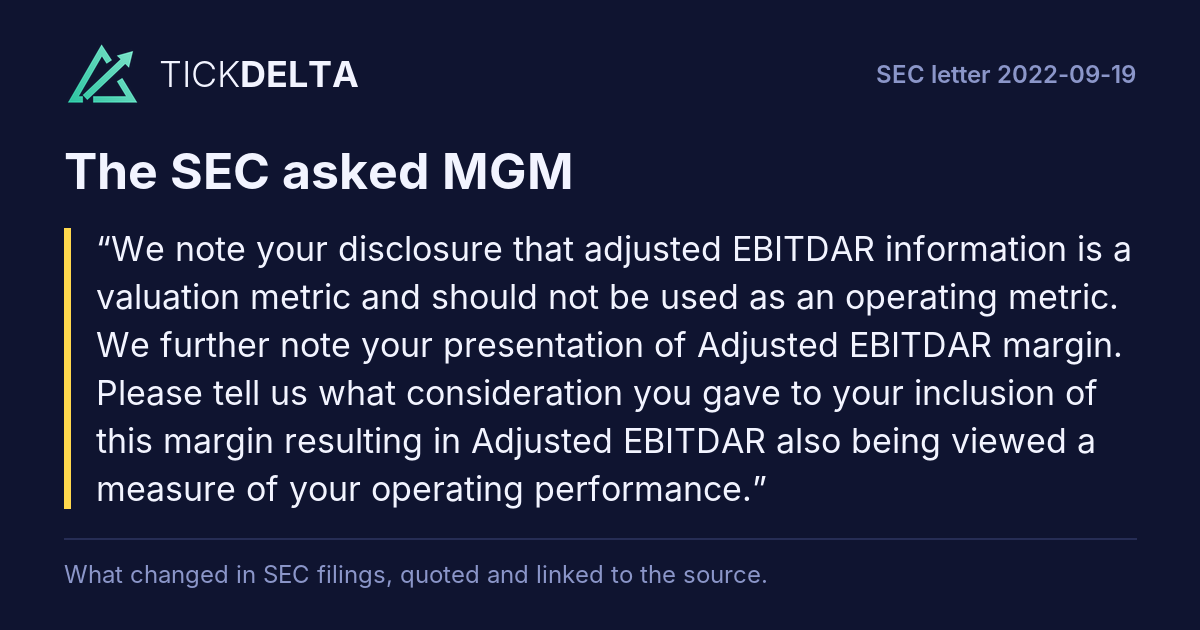
We note your disclosure that adjusted EBITDAR information is a valuation metric and should not be used as an operating metric. We further note your presentation of Adjusted EBITDAR margin. Please tell us what consideration you gave to your inclusion of this margin resulting in Adjusted EBITDAR also being viewed a measure of your operating performance.
MGM answered
In future filings, the Company will revise its presentation to remove Adjusted EBITDAR margin.
Read in the reply
In its next report

First report after the company's reply of Sep 22, 2022: 10-Q filed Nov 2, 2022 ↗, against the 10-Q filed Aug 3, 2022 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.
Adjusted Diluted Earnings Per Share, page 3
SEC asked (2)
We note your adjustment for loss (gain) related to equity investments to arrive at adjusted diluted earnings per share. Please tell us the nature of this adjustment and how it is derived.
MGM answered
Loss (gain) related to equity investments reflects the net unrealized loss (gain) relating to equity investments for which the Company has elected the fair value option of ASC 825 and equity investments accounted for under ASC 321 for which there is a readily determinable fair value.

If there are additional comments or questions, please do not hesitate to contact the undersigned at (212) 530-5022.
Read in the reply
In its next report

First report after the company's reply of Sep 22, 2022: 10-Q filed Nov 2, 2022 ↗, against the 10-Q filed Aug 3, 2022 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Also in this review: closing letter, 2022-09-26

Form 10-K for the year ended December 31, 2019

2020-07-16 to 2020-08-20 · 3 questions · 2 letters from the SEC, 2 from the company
Review closed 2020-08-20
Non-GAAP measuresResults discussion (MD&A)Segments
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations · Non-GAAP Measures , page 40
SEC asked
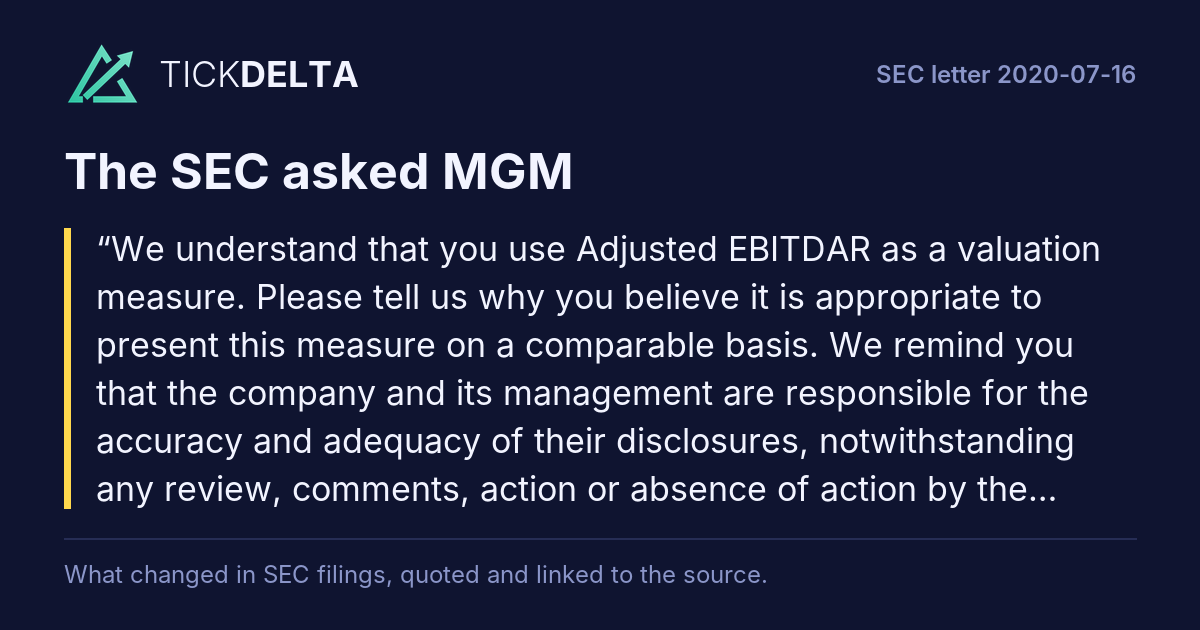
We understand that you use Adjusted EBITDAR as a valuation measure. Please tell us why you believe it is appropriate to present this measure on a comparable basis. We remind you that the company and its management are responsible for the accuracy and adequacy of their disclosures, notwithstanding any review, comments, action or absence of action by the staff.
MGM answered
The Company presents Adjusted EBITDAR on a consistent and comparable basis for all periods presented solely as a supplemental disclosure to reported GAAP measures that the Company believes is widely used as a principal basis for the valuation of gaming companies by analysts, lenders, financial institutions, investors, the Company and its peers, and because presenting Adjusted EBITDAR on a comparable basis assists such analysts, investors and others to understand changes in the Company’s value over time as evidenced by comparative Adjusted EBITDAR presentations included by analysts within
Rest of the answer

certain research reports.

Adjusted EBITDAR provides useful information to analysts, lenders, financial institutions, and investors when valuing the Company, as well as comparing the Company’s valuation to other gaming companies, without regard to differences in capital structure and leasing arrangements, since Adjusted EBITDAR eliminates the effects of triple net operating leases and ground leases and the capital structures of other gaming companies may or may not include triple net operating leases or ground leases. Adjusted EBITDAR is also commonly used by operating companies in other industries where there is significant variability in the way that capital assets are financed, such as airline operators and nursing home operators. Adjusted EBITDAR is an especially important valuation metric for the Company because a majority of the Company’s properties are subject to triple net lease arrangements. Since the Company has financed (and may finance in the future) a significant majority of its real estate through triple net leases, investors and analysts value the Company’s enterprise by utilizing a multiple which is applied to the estimated rental payments specific to the Company’s triple net leases with its landlords, which is then added to the Company’s net debt and market capitalization. The sum is then divided by Adjusted EBITDAR to arrive at the Company’s enterprise value multiple.

Disclosing Adjusted EBITDAR on a consistent and comparable basis for all periods presented serves an important purpose in helping investors and analysts value the Company’s present business, which importantly includes understanding the changes in the Company’s value over time in much the same way that presenting comparative balance sheets allow investors and analysts to understand changes in the Company’s financial position over time. To provide further management discussion and analysis around the changes in what constitutes Adjusted EBITDAR, the Company discloses and analyzes the changes in the underlying Adjusted Property EBITDAR (the Company’s primary profit measure for its reportable segments) which aggregate to the consolidated Adjusted EBITDAR and reconciles such amounts to net income for all periods presented.

If there are additional comments or questions, please do not hesitate to contact the undersigned at (212) 530-5022.

Read in the reply
In its next report

First report after the company's reply of Jul 21, 2020: 10-Q filed Aug 3, 2020 ↗, against the 10-Q filed May 1, 2020 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations · Adjusted EBITDAR, page 37
SEC asked (1)
We note your presentation of Adjusted EBITDAR and that management uses Adjusted Property EBITDAR as the primary profit measure for your reportable segments. Please note the presentation of the total segment profit or loss measure in any context other than the ASC 280 required reconciliation in the footnote is considered a presentation of a non- GAAP financial measure.
Rest of the question

In future filings, please revise your presentation accordingly. Refer to Question 104.04 of the Compliance & Disclosure Interpretations for Non-GAAP Financial Measures.

MGM answered
In future filings, the Company will revise its presentation of Adjusted EBITDAR to remove the subtotal of its reportable segments’ Adjusted Property EBITDAR.
Read in the reply
In its next report

First report after the company's reply of Aug 19, 2020: 10-Q filed Nov 3, 2020 ↗, against the 10-Q filed May 1, 2020 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Non-GAAP Measures , page 40
SEC asked (2)
We note your response to comment 1. In future filings, please limit your presentation of Adjusted EBITDAR to the most current period presented.
MGM answered
In future filings, the Company will revise its presentation of Adjusted EBITDAR to present an Adjusted EBITDAR total only for the most current period.

If there are additional comments or questions, please do not hesitate to contact the undersigned at (212) 530-5022.
Read in the reply
In its next report

First report after the company's reply of Aug 19, 2020: 10-Q filed Nov 3, 2020 ↗, against the 10-Q filed May 1, 2020 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Also in this review: closing letter, 2020-08-20

From the SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), 8 letters filed since 2020-07-16. Questions and answers are matched by their numbers; topics come from words in each question. The reports are compared word for word (same form, before the first SEC letter against the first report after the company's reply). No AI.

Sources

The SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), matched question by question. No AI.

Also

Filings: the letters in the filing list.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/MGM/export.csv") into a cell.

Next in Owners and insiders:Insider trades
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.