Form 10-K for the Fiscal Year Ended January 29, 2022
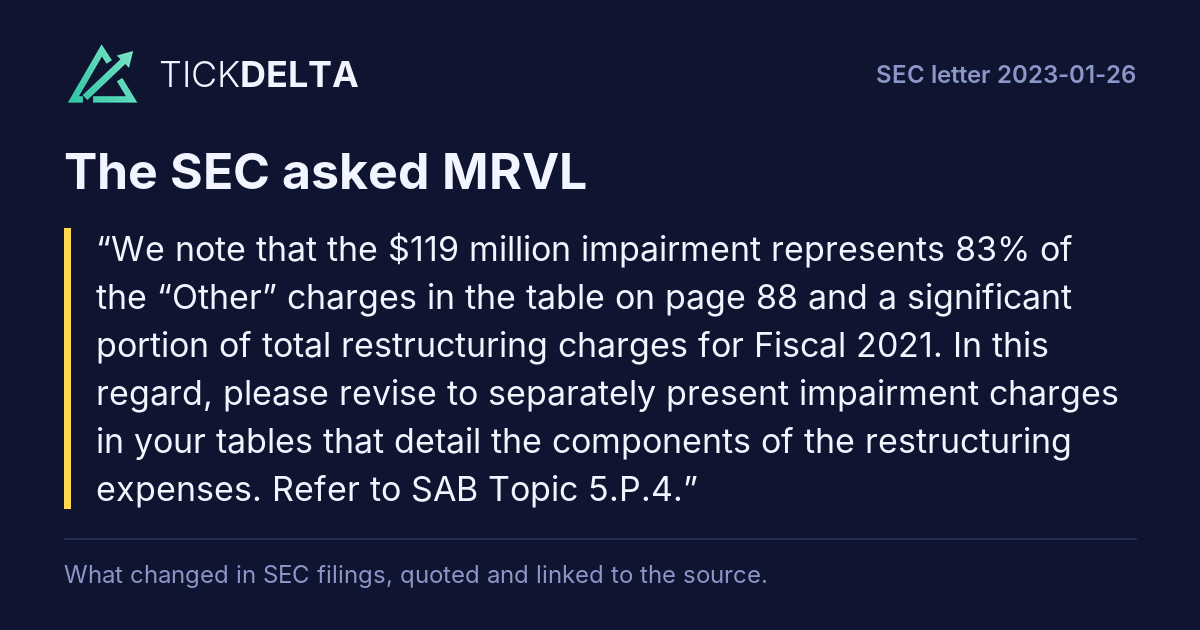
We note that the $119 million impairment represents 83% of the “Other” charges in the table on page 88 and a significant portion of total restructuring charges for Fiscal 2021. In this regard, please revise to separately present impairment charges in your tables that detail the components of the restructuring expenses. Refer to SAB Topic 5.P.4.
The Company acknowledges the Staff’s comment, and, in future filings, will provide added disclosure.
While we respectfully note that we had explained the impairment charges in detail directly below the table, under the Fiscal 2021 caption in our Annual Report on Form 10-K for the fiscal year ended
January 29, 2022, in the future if we incur significant impairment charges, we will present such impairment charges as separate line items in the table.Read in the reply ↗Rest of the answer
Below is an illustration of the proposed disclosure that the Company anticipates including in its next Annual Report on Form 10-K for the fiscal year ended January 28, 2023 with changes from our previous filing shown in bold text below. We have added three additional rows of sub-categories of impairment charges into the table below. Please note while reviewing the table below that we do not yet have final financial statements for the most recently completed fiscal year ended
January 28, 2023 and so have left that column blank at this time. In addition, the three new subcategories of impairment charges were not applicable in the fiscal year ended January 29, 2022.
The following table presents details related to the restructuring related charges as presented in the consolidated statements of operations (in millions):
Year Ended
January 28,
2023
January 29,
2022
January 30,
First report after the company's reply of 2023-02-03: 10-K filed 2023-03-09 ↗, against the 10-K filed 2022-03-10 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
In a related matter, your MD&A should be revised on page 48 to provide a robust discussion of the nature of your restructuring charges rather than just referencing the financial statement footnote.
The Company acknowledges the Staff’s comment, and we respectfully note that we had explained the restructuring charges in detail in “Note 10 – Restructuring” in the Notes in the Consolidated Financial Statements in our Annual Report on Form 10-K for the fiscal year ended January 29, 2022. We included the explanation in the Notes and not also in the MD&A in an effort to reduce duplicative disclosure; however, in the future if we incur significant restructuring charges, we will separately discuss such charges in the MD&A section.
Below is an illustration of the proposed disclosure that theRead in the reply ↗Rest of the answer
Company anticipates including in its next Annual Report on Form 10-K for the fiscal year ended January 28, 2023 with changes from our previous filing shown in bold text below. As noted above, we do not yet have final financial statements for the most recently completed fiscal year ended January 28, 2023 and so have left that column and related discussion blank at this time.
Restructuring Related Charges
(in millions)
Restructuring related charges
32.4
170.8
Fiscal 2023 vs Fiscal 2022: We recorded total restructuring related charges of $0.0 million in fiscal 2023 as we integrated the acquired businesses and continued to evaluate our existing operations to increase operational efficiency, decrease costs and improve profitability.
Fiscal 2022 vs Fiscal 2021: During the second quarter of fiscal 2021, we made changes to the scope of our server processor product line in response to changes in the associated market. We transitioned our product offering from standard server processors to the broad server market to focus only on customized server processors for a few targeted customers. This change in strategy required us to assess whether the carrying value of the associated assets would be recoverable. As a result of the assessment, we determined the carrying amount of certain impacted assets were not recoverable, which resulted in recognition of $119.0 million of restructuring related charges associated with the server processor product line during the second quarter of fiscal 2021. The charges included $50.3 million in impairment of acquired intangibles,
$36.0 million in impairment of purchased IP licenses and $32.7 million in equipment and inventory impairment and other related restructuring charges. The remaining restructuring charges of $61.4 million include approximately
$36.9 million in severance and related costs and $24.5 million in other costs. The severance costs primarily relate to the employee separation costs in connection with the acquisitions. The other costs primarily relate to the remaining payments under lease obligations upon vacating certain worldwide office locations, and ongoing operating expenses of vacated facilities. See “Note 10 – Restructuring” in the Notes to the Consolidated Financial Statements for further information.
Notes to Unaudited Condensed
Consolidated Financial Statements
Note 7. Goodwill and Acquired Intangible Assets, Net, page 20
We note that in the second quarter of fiscal 2023, you acquired IPR&D and hired staff to expand your engineering resources and this resulted in $20.1 million of IPR&D and $40 million of goodwill. As this appears to be an asset acquisition rather than a business combination, please clarify for us how this represents a business combination under ASC 805. Specifically refer to ASC 805-10-55-3A through 9.
Response: The Company acknowledges the Staff’s comment, and would like to clarify that the Company acquired two separate semiconductor design businesses in the second quarter of fiscal year 2023, primarily for the purpose of expanding our engineering resources and obtaining intellectual property (IP). These businesses were located in the U.S. and India and were acquired for aggregate purchase consideration of $60.1 million.
While these are individually and in the aggregate immaterial, the Company evaluated each of the transactions in accordance with ASC 805 Business Combinations to determine whether such transaction met the requirements to be accounted for as a business combination. ASC 805-10-25-1 provides that “an entity shall determine whether a transaction or other event is a business combination by applying the definition, which requires that the assets acquired and liabilities assumed constitute a “business”. If the assets acquired are not a business, the reporting entity shall account for the transaction or other event as an asset acquisition.”
ASC 805-10-55-5A provides that
“If substantially all of the fair value of the gross assets acquired is concentrated in a single identifiable asset or a group of similar identifiable assets, the set is not a business.” When applying this standard, we evaluated the gross assets acquired from each transaction and determined that multiple identifiable assets were acquired, and that not substantially all of the fair value is concentrated in a single identifiable asset or group of similar identifiable assets. For example, some of the assets acquired in each transaction included: acquired intangible assets, prepaid assets and deposits, property and equipment, facility lease related right-of-use assets, etc. as well as assembled workforce and assumed liabilities.
We then considered ASC 805-10-55-4 which provides that “A business consists of inputs and processes applied to those inputs that have the ability to create outputs. Although businesses usually have outputs, outputs are not required for an integrated set to qualify as a business.” ASC 805-10-55-5D further discusses transactions such as an early stage business that has not yet generated revenue output. If the business has an organized employee workforce with the necessary skills, knowledge, or experience that can develop or convert into revenue generating output such as developing IP into revenue generating output, then the business has the necessary inputs and substantive processes to create output.
“The three elements of a business are defined as follows:
a.
Input. Any economic resource that creates, or has the ability to create, outputs when one or more processes are applied to it. Examples include long-lived assets (including intangible assets or rights to use long-lived assets), intellectual property and the ability to obtain access to necessary materials or rights and employees.”
We acquired one privately held company and one business of another privately held company (collectively, the
“companies”), both of which design and develop IP. One of the companies develops Compute Express Link (CXL) based products, which enables increased memory bandwidth, capacity and utilization within and across servers. The second designs and develops certain controller products which will be developed in conjunction with the first company’s IP to expand CXL 2.0 to CXL 3.0 with differentiated features. Therefore, both companies satisfy the above requirements related to
Input.
b.
“Process. Any system, standard, protocol, convention, or rule that when applied to an input or inputs, creates or has the ability to contribute to the creation of outputs. Examples include strategic management processes, operational processes, and resource management processes. These processes typically are documented, but the intellectual capacity of an organized workforce having the necessary skills and experience following rules and conventions may provide the necessary processes that are capable of being applied to inputs to create outputs. Accounting, billing, payroll, and other administrative systems typically are not processes used to create outputs.”
The acquired companies each have established management and operational processes over their IP development activity, marketing processes, and resource management processes over their engineering workforce. Both transactions provide Marvell with technical staff acquired that are organized workforces with the necessary skills, knowledge and experience that can develop the acquired CXL IP and convert it to an output. Therefore, both companies satisfy the above requirements related to Process.
c.
“Output. The result of inputs and processes applied to those inputs that provide goods or services to customers, investment income (such as dividends or interest), or other revenues.”
While the acquired companies have not generated revenue to date, the results of the inputs and processes enables CXL technologies critical to relevant products to sell to customers and generate revenue and therefore both companies satisfy the above requirements whereby the inputs and processes can convert to output.
Based on the aforementioned analysis, the Company concluded that the transactions met the criteria under the framework guidance to be accounted for as business combinations in accordance with ASC 805.
In addition, we respectfully advise the Staff that these two transactions were not material to the Company’s consolidated financial statements. The transactions contributed nominal net assets to Marvell’s consolidated financial statements at close. As a result, we did not include expanded business combination disclosure in our Quarterly Report on Form 10-Q for the second fiscal quarter of fiscal year 2023. However, we note that because the transaction activity increased goodwill in the applicable period, we included additional explanatory disclosure in “Note 7 – Goodwill and Acquired Intangible Assets, Net” in the Notes to the Consolidated Financial Statements in our Quarterly Report on Form 10-Q for the second fiscal quarter of fiscal year 2023.
Exhibit 99.1 Earnings Release, page 9
4. We note you present several non-GAAP financial measures including, net income on a non-GAAP basis and net income per share on a non-GAAP basis, which include related income tax adjustments. It is not clear to us how you calculated the income tax adjustments related to these non-GAAP financial measures or how you determined the income tax adjustments comply with the response to Question 102.11 of the Compliance and Disclosure Interpretations on Non-GAAP Financial Measures. In this regard, we note your use of a 5 and 6% income tax rate related to the non-GAAP adjustments you recorded and, for the twelve months ended January 29, 2022 we note your effective income tax rate was about 12% on a GAAP basis and was much higher for the 2023 quarters. Please explain to us how you calculated the income tax adjustments related to these non-GAAP financial measures and how you determined the non-GAAP income tax adjustments are appropriate and comply with Question 102.11 or explain how you intend to revise your non-GAAP financial measures to comply with Question 102.11.
Response: We respectfully advise the Staff that our non-GAAP income tax expense (benefit) is computed inclusive of both current and deferred income taxes consistent with Question 102.11 for a performance measure. Our non-GAAP policy for income taxes, as disclosed in our filing, is as follows:
Marvell uses a non-GAAP tax rate to compute the non-GAAP tax provision. This non-GAAP tax rate is based on Marvell’s estimated annual GAAP income tax forecast, adjusted to account for items excluded from Marvell’s non-GAAP income, as well as the effects of significant non-recurring and period specific tax items which vary in size and frequency, and excludes tax deductions and benefits from acquired tax loss and credit carryforwards and changes in valuation allowance on acquired deferred tax assets. Marvell’s non-GAAP tax rate is determined on an annual basis and may be adjusted during the year to take into account events that may materially affect the non-GAAP tax rate such as tax law changes; acquisitions; significant changes in Marvell’s geographic mix of revenue and expenses; or changes to Marvell’s corporate structure.
Our non-GAAP tax rate is calculated by adjusting the GAAP income tax provision for the income tax effects of our non-GAAP pre-tax adjustments. Consistent with our non-GAAP income tax policy, our non-GAAP income taxes for the interim periods in fiscal year 2023 excluded the tax effects of non-recurring income tax items as were described in our Quarterly Reports on Form
10-Q. In the first quarter of our current fiscal year, $213.6 million of non-recurring income tax expense associated with the extension of a tax incentive in
Singapore was excluded from our non-GAAP income tax expense. Additionally, during the third quarter of our current fiscal year ended January 28, 2023, we excluded $22.4 million of non-recurring income tax expense associated with the claw back of incentive benefits that resulted from our election to avail ourselves of a preferential temporary tax provision in Israel.
As a result of both the tax effects of our non-GAAP pre-tax adjustments and the non-recurring tax items described above, our non-GAAP income tax rate was significantly lower than our GAAP income tax rate. On a prospective basis, for our future filings, we will provide an explanation of any material unusual or non-recurring items with respect to our non-GAAP income taxes.
5. We note that several of your non-GAAP performance measures adjust for the amortization of acquired intangible assets. Please revise to disclose the specific nature of the amortization that is being excluded from the measure, and that while the expense is excluded, the revenue of the acquired company is reflected in the measure and that those assets contribute to revenue generation.
Response: The Company acknowledges the Staff’s comment, and, in future filings, the Company plans to provide added disclosure related to the referenced non-GAAP measures with respect to adjustments for acquired intangible assets. We intend to include the following proposed additional disclosure under the caption “Discussion of Non-GAAP Financial Measures” in our Exhibit 99.1 Earnings Release to be included in Form
8-K for the fiscal year ended January 28, 2023.
Although Marvell excludes the amortization of all acquired intangible assets from these non-GAAP financial measures, management believes that it is important for investors to understand that such intangible assets were recorded as part of purchase price accounting arising from acquisitions, and that such amortization of intangible assets that relate to past acquisitions will recur in future periods until such intangible assets have been fully amortized. Investors should note that the use of intangible assets contributed to Marvell’s revenues recognized during the periods presented and are expected to contribute to Marvell’s future period revenues as well.
First report after the company's reply of 2023-02-03: 10-K filed 2023-03-09 ↗, against the 10-K filed 2022-03-10 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
We note that in the second quarter of fiscal 2023, you acquired IPR&D and hired staff to expand your engineering resources and this resulted in $20.1 million of IPR&D and $40 million of goodwill. As this appears to be an asset acquisition rather than a business combination, please clarify for us how this represents a business combination under ASC 805. Specifically refer to ASC 805-10-55-3A through 9.
No numbered answer found in the reply. Read the reply ↗
First report after the company's reply of 2023-02-03: 10-K filed 2023-03-09 ↗, against the 10-K filed 2022-03-10 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
We note you present several non-GAAP financial measures including, net income on a non-GAAP basis and net income per share on a non-GAAP basis, which include related income tax adjustments. It is not clear to us how you calculated the income tax adjustments related to these non-GAAP financial measures or how you determined the income tax adjustments comply with the response to Question 102.11 of the Compliance andRest of the question
Disclosure Interpretations on Non-GAAP Financial Measures. In this regard, we note your use of a 5 and 6% income tax rate related to the non-GAAP adjustments you recorded and, for the twelve months ended January 29, 2022 we note your effective income tax rate was about 12% on a GAAP basis and was much higher for the 2023 quarters. Please explain to us how you calculated the income tax adjustments related to these non-GAAP financial measures and how you determined the non-GAAP income tax adjustments are appropriate and comply with Question 102.11 or explain how you intend to revise your non-GAAP financial measures to comply with Question 102.11.
No numbered answer found in the reply. Read the reply ↗
First report after the company's reply of 2023-02-03: 10-K filed 2023-03-09 ↗, against the 10-K filed 2022-03-10 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
We note that several of your non-GAAP performance measures adjust for the amortization of acquired intangible assets. Please revise to disclose the specific nature of the amortization that is being excluded from the measure, and that while the expense is excluded, the revenue of the acquired company is reflected in the measure and that those assets contribute to revenue generation.
No numbered answer found in the reply. Read the reply ↗
First report after the company's reply of 2023-02-03: 10-K filed 2023-03-09 ↗, against the 10-K filed 2022-03-10 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: closing letter, 2023-02-10