Paragraph 167 · 46% changed
Every version of it
Screener
/
SEC EDGAR
/CIK 0001547903
/10-K filed Feb 12, 2026, compared with Feb 14, 2025
/Numbers from the XBRL of the 10-Ks
Nasdaq
Financials · Surety Insurance
NMI Holdings, Inc. NMIH
The 10-K against last year's
145 changes: 15 added, 49 removed, 80 reworded, 1 quiet changes
10-K Feb 12, 2026 vs Feb 14, 2025
Risk Factors
7.7%
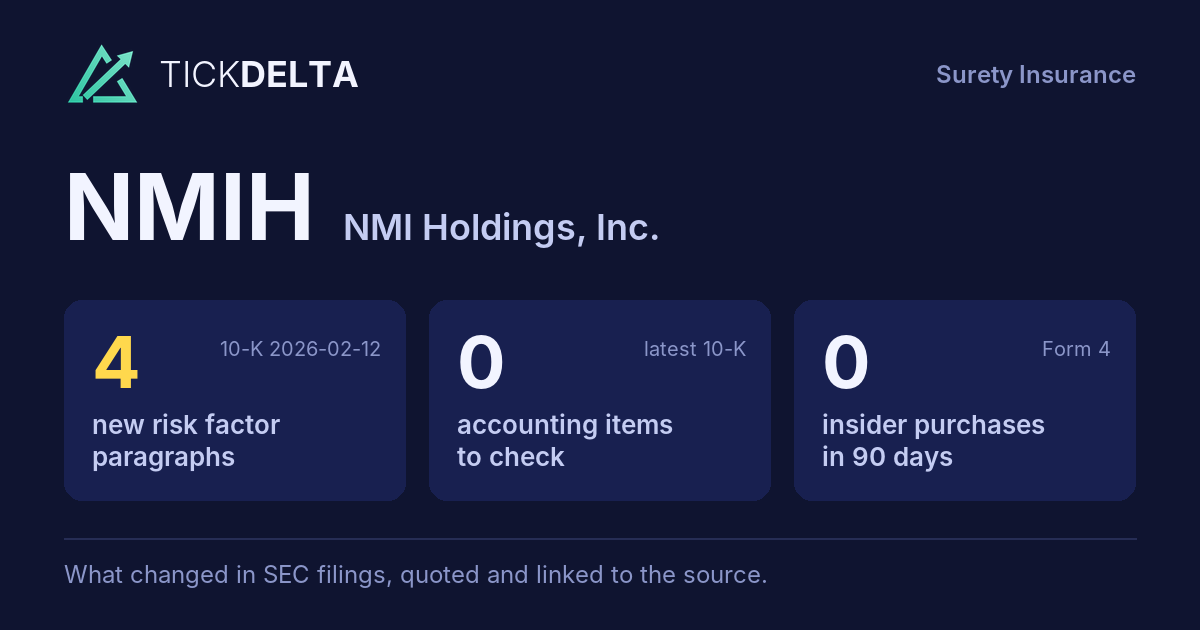
of the text changed · 18,538 words now · 4 new paragraphs, 4 gone
MD&A
23.1%
of the text changed · 11,994 words now · 11 new paragraphs, 45 gone
Legal Proceedings
10.4%
of the text changed · 345 words now
Accounting Policies
14.8%
of the text changed · 3,438 words now
10-K 0001547903-26-000011 (Feb 12, 2026) vs 10-K 0001547903-25-000026 (Feb 14, 2025)
Every paragraph, and how much of it changed
One bar per paragraph, in the order of the 10-K. Height and colour show the share of its words not in the closest paragraph a year earlier; the tallest bars are new paragraphs.
Risk Factors
243 paragraphs · 4 new · 54 reworded · 4 gone · 10-K Feb 12, 2026 against Feb 14, 2025
New paragraph
Reworded (5% of its words or more)
Same or nearly
Paragraph 92 · 41% changed
Every version of it
Paragraph 68 · 36% changed
Every version of it
The success of our mortgage insurance business is highly dependent on our ability to attract and retain as customers the most significant mortgage lenders in the U.S., measured through the combined volume of their retail originations and/or the insured loans they may acquire from other originators. As a result of their size and market share, these entities originate a significant majority of high-LTV mortgages in the U.S. and, therefore, influence the size and pricing of the MI market. We are currently doing business with a majority of these lenders. However, there is no assurance we will receive approvals from each of the remaining lenders to transact MI business with them or that those lenders who have approved us will continue to maintain business relationship with us. If we are unable to maintain our approved status with one or more of these mortgage lenders, our business, financial condition and operating results could be adversely impacted.
Paragraph 134 · 36% changed
Every version of it
Reinsurance does not relieve us of our direct liability to our insureds to pay claims, even when there are reinsurance recoverables available to us under the QSR Transactions or XOL Transactions. Accordingly, we bear credit risk with respect to such reinsurers. To mitigate this risk, there are certain contractual protections that establish sources from which we may directly obtain our reinsurance recoverables under the QSR Transactions or XOL Transactions. The ILN Transactions are fully collateralized with funds deposited into trust accounts to secure the obligations of the reinsurers to NMIC under the respective reinsurance agreement. See Part II, Item 8, "Financial Statements and Supplementary Data - Notes to Consolidated Financial Statements - Note 6, Reinsurance," below. To the extent the amounts in the QSR Transaction or XOL Transaction trust accounts are insufficient to cover loss recoveries and other amounts to which we are entitled under the QSR Transactions or XOL Transactions, we would attempt to recover such amounts directly from the reinsurers. One or more reinsurers may be unable or unwilling to pay reinsurance recoverables owed to us in the future, which could have an adverse effect on our financial condition.
Paragraph 187 · 34% changed
Every version of it
In January 2014, the CFPB implemented the Dodd-Frank Act ATR mortgage provisions, which govern the obligation of lenders to determine a borrower's ability to pay when originating a mortgage loan covered by ATR. A subset of mortgages falling under the ATR that has certain low-risk characteristics are known as QMs. QMs that are deemed to have the lowest risk profiles are entitled to a safe-harbor presumption of compliance with the ability-to-pay requirements. In the fourth quarter of 2020, the CFPB released a series of final rules to (i) eliminate the temporary QM category, typically referred to as the "QM Patch", “QM Patch”, (ii) amend the definition of a General QM, and (iii) provide for a new, Seasoned QM category. The General QM final rule was effective on March 1, 2021 with an extended mandatory compliance date of October 1, 2022. However, the GSEs announced on April 8, 2021 that, for loan applications received on or after July 1, 2021, they will only purchase loans satisfying the New General QM Definition. See "Item 1, "Business - U.S. Mortgage Insurance Regulation - Other U.S. Regulation - Housing Finance Reform" above for a summary of the GSEs final rules related to QMs. The long-term effects of the expiration of the QM Patch and implementation of the General QM and Seasoned QM final rules could affect the residential mortgage market and demand for private mortgage insurance.
Paragraph 150 · 30% changed
Every version of it
We have adopted information security procedures and controls to safeguard our systems and the information that we process, transmit and store, including multi-factor authentication and a new biometrics solution to authenticate employee login. Despite these efforts, we may not be able to anticipate or implement effective preventive measures against all cyber threats, or detect and contain a breach in a timely manner, including because employees or contractors may not follow the controls we have implemented, the invasive techniques used change frequently or are not recognized until launched, and because security attacks can originate from a wide variety of sources and methods. Further, the sophistication, availability and use of artificial intelligence by threat actors may present an increased level of risk. Our remote or hybrid working arrangements may exacerbate these risks. Our employees, contractors, customers or other users of our systems are are, from time-to-time time to time, subject to fraudulent inducements by parties attempting to gain access to our data or that of our customers. Although we seek to have appropriate information security policies and systems in place, there is no assurance that our information security policies and systems in place can prevent unauthorized use or disclosure of confidential information, including nonpublic personal information. Any compromise of the security of our IT systems may result in loss of personally identifiable information, financial losses, loss of customers and the inability to transact business; could be costly and time-consuming to address and resolve; could expose us to liability for further compromise, damages, harm our reputation; and may subject us to regulatory scrutiny and/or expose us to civil litigation or regulatory action. If any of these were to occur, our business, financial condition and operating results could be materially adversely affected. Further, the technology errors and omissions, and insurance coverage we maintain may be unavailable or inadequate to fully cover claims and/or costs associated with incidents that may occur in the future.
Paragraph 188 · 30% changed
Every version of it
Paragraph 143 · 28% changed
Every version of it
We are exposed to many types of operational risk, including the risk of fraud or malfeasance by borrowers, employees and outsiders, including third-party service providers, clerical record-keeping errors and transactional errors. Our business depends on our employees and third parties to process a large number of transactions. We could be materially and adversely affected if one of our employees or one of our systems causes a significant operational breakdown or failure, either as a result of human error or where an individual purposefully sabotages or fraudulently manipulates our operations or systems. Third parties with whom we do business also could be sources of operational risk to us, including breakdowns or failures of such parties' own systems or employees. Given our hybrid and remote work arrangements of our employees and staff, the effectiveness of our compliance programs and overall ability to prevent and detect fraud or malfeasance by our employees or contractors may be diminished. Any of these occurrences could result in a diminished ability to operate our business, potential liability to customers, reputational damage and regulatory intervention, which could result in a material adverse effect on our financial position and operating results.
Paragraph 167 · 46% changed
Every version of it
10-K Feb 14, 2025With the GSEs in a prolonged conservatorship, there has been ongoing debate over the future role and purpose of the GSEs in the U.S. housing market. The U.S. Congress may legislate, or the administration may implement through administrative reform, structural and other changes to the GSEs and the functioning of the secondary mortgage market. Since 2011, there have been numerous legislative proposals intended to incrementally scale back the GSEs (such as a statutory mandate for the GSEs to transfer mortgage credit risk to the private sector) or to completely reform the housing finance system. Congress, however, has not enacted any legislation to date. The proposals vary with regard to the government's role in the housing market and, more specifically, with regard to the existence of an explicit or implicit government guarantee. Recently, there has been increased focus on and discussion of administrative reform independent of legislative action. The former director of FHFA leadership under the first Trump administration was more focused on preparing the GSEs to exit from conservatorship by increasing the GSEs’ overall capital levels and reducing their credit risk profile. In December 2020, the FHFA published a final rule (2020 ERCF rule) establishing a new enterprise regulatory capital framework (ERCF) for the GSEs, which included provisions governing the capital relief allowed to the GSEs for loans with private MI. The 2020 ERCF rule established that loans with private MI, as opposed to loans without private MI, provide more favorable capital relief to the GSEs. Additionally, while in conservatorship, each GSE has been subject to the terms of senior Preferred Stock Purchase Agreements (PSPAs) establishing Treasury's ownership of senior preferred stock and warrants in the GSEs. The PSPAs, as amended by the Treasury Department in collaboration with the FHFA, also establish Treasury's right to consent to any GSE release from conservatorship, among other rights.
10-K Feb 12, 2026
relief allowed to the GSEs for loans with private MI. The 2020 ERCF rule established that loans with private MI, as opposed to loans without private MI, provide more favorable capital relief to the GSEs. Additionally, while in conservatorship, each GSE has been subject to the terms of senior Preferred Stock Purchase Agreements (PSPAs) establishing Treasury's ownership of senior preferred stock and warrants in the GSEs. The PSPAs, as amended by the Treasury Department in collaboration with the FHFA, also establish Treasury's right to consent to any GSE release from conservatorship, among other rights.
Paragraph 92 · 41% changed
Every version of it
10-K Feb 14, 2025Our mortgage insurance premiums may not be adequate to cover our future claim payments. We set premiums at the time a policy is issued based on our expectations regarding likely performance over the term of the policy. Our premium rates are developed based on certain expectations that may ultimately prove to be inaccurate. Our premiums are subject to approval by certain state insurance regulators, which can delay or limit our ability to increase our premiums. Generally, we will not be able to cancel the MI coverage or adjust renewal premiums during the life of an MI policy to mitigate adverse development. As a result, when facing higher than anticipated claims, we generally will not be able to offset it by increasing premiums on policies in force, or mitigate it by not renewing or cancelling any coverage. While we believe our capital, premiums and investment earnings will provide a pool of resources sufficient to cover expected loss payments and we have made estimates regarding loss payments and potential claims, we cannot predict with certainty the ultimate number and magnitude of claims we experience. Therefore, the actual premiums (along with investment earnings) may not be sufficient to cover losses and/or our operating costs. An increase in the number or size of claims, compared to what we anticipate, could adversely affect our operating results or financial condition. We may not be able to achieve the results that we expect, and there can be no assurance that losses will not exceed our total resources.
10-K Feb 12, 2026
potential claims, we cannot predict with certainty the ultimate number and magnitude of claims we experience. Therefore, the actual premiums (along with investment earnings) may not be sufficient to cover losses and/or our operating costs. An increase in the number or size of claims, compared to what we anticipate, could adversely affect our operating results or financial condition. We may not be able to achieve the results that we expect, and there can be no assurance that losses will not exceed our total resources.
Paragraph 68 · 36% changed
Every version of it
10-K Feb 14, 2025
The success of our mortgage insurance business is highly dependent on our ability to attract and retain as customers the most significant mortgage lenders in the U.S., measured through the combined volume of their retail originations and/or the insured loans they may acquire from other originators. As a result of their size and market share, these entities originate a significant majority of high-LTV mortgages in the U.S. and, therefore, influence the size and pricing of the MI market. We are currently doing business with a majority of these lenders. However, there is no assurance we will receive approvals from each of the remaining lenders to transact MI business with them or that those lenders who have approved us will continue to maintain business relationship with us. If we are unable to maintain our approved status with one or more of these mortgage lenders, our business, financial condition and operating results could be adversely impacted.
10-K Feb 12, 2026
The success of our mortgage insurance business is highly dependent on our ability to attract and retain as customers the most significant mortgage lenders in the U.S., measured through the combined volume of their retail originations and/or the insured loans they may acquire from other originators. As a result of their size and market share, these entities originate a
Paragraph 134 · 36% changed
Every version of it
10-K Feb 14, 2025
Reinsurance does not relieve us of our direct liability to our insureds to pay claims, even when there are reinsurance recoverables available to us under the QSR Transactions or XOL Transactions. Accordingly, we bear credit risk with respect to such reinsurers. To mitigate this risk, there are certain contractual protections that establish sources from which we may directly obtain our reinsurance recoverables under the QSR Transactions or XOL Transactions. The ILN Transactions are fully collateralized with funds deposited into trust accounts to secure the obligations of the reinsurers to NMIC under the respective reinsurance agreement. See Part II, Item 8, "Financial Statements and Supplementary Data - Notes to Consolidated Financial Statements - Note 6, Reinsurance," below. To the extent the amounts in the QSR Transaction or XOL Transaction trust accounts are insufficient to cover loss recoveries and other amounts to which we are entitled under the QSR Transactions or XOL Transactions, we would attempt to recover such amounts directly from the reinsurers. One or more reinsurers may be unable or unwilling to pay reinsurance recoverables owed to us in the future, which could have an adverse effect on our financial condition.
10-K Feb 12, 2026
Reinsurance does not relieve us of our direct liability to our insureds to pay claims, even when there are reinsurance recoverables available to us under the QSR Transactions or XOL Transactions. Accordingly, we bear credit risk with respect to such reinsurers. To mitigate this risk, there are certain contractual protections that establish sources from which we may directly obtain our reinsurance recoverables under the QSR Transactions or XOL Transactions. The ILN Transactions are fully
Paragraph 187 · 34% changed
Every version of it
10-K Feb 14, 2025
In January 2014, the CFPB implemented the Dodd-Frank Act ATR mortgage provisions, which govern the obligation of lenders to determine a borrower's ability to pay when originating a mortgage loan covered by ATR. A subset of mortgages falling under the ATR that has certain low-risk characteristics are known as QMs. QMs that are deemed to have the lowest risk profiles are entitled to a safe-harbor presumption of compliance with the ability-to-pay requirements. In the fourth quarter of 2020, the CFPB released a series of final rules to (i) eliminate the temporary QM category, typically referred to as the "QM Patch", (ii) amend the definition of a General QM, and (iii) provide for a new, Seasoned QM category. The General QM final rule was effective on March 1, 2021 with an extended mandatory compliance date of October 1, 2022. However, the GSEs announced on April 8, 2021 that, for loan applications received on or after July 1, 2021, they will only purchase loans satisfying the New General QM Definition. See "Item 1, "Business - U.S. Mortgage Insurance Regulation - Other U.S. Regulation - Housing Finance Reform" above for a summary of the GSEs final rules related to QMs. The long-term effects of the expiration of the QM Patch and implementation of the General QM and Seasoned QM final rules could affect the residential mortgage market and demand for private mortgage insurance.
10-K Feb 12, 2026
In January 2014, the CFPB implemented the Dodd-Frank Act ATR mortgage provisions, which govern the obligation of lenders to determine a borrower's ability to pay when originating a mortgage loan covered by ATR. A subset of mortgages falling under the ATR that has certain low-risk characteristics are known as QMs. QMs that are deemed to have the lowest risk profiles are entitled to a safe-harbor presumption of compliance with the ability-to-pay requirements. In the fourth quarter of 2020, the CFPB released a series of final rules to (i) eliminate the temporary QM category, typically referred to as the “QM Patch”, (ii)
Paragraph 150 · 30% changed
Every version of it
10-K Feb 14, 2025
We have adopted information security procedures and controls to safeguard our systems and the information that we process, transmit and store, including multi-factor authentication and a new biometrics solution to authenticate employee login. Despite these efforts, we may not be able to anticipate or implement effective preventive measures against all cyber threats, or detect and contain a breach in a timely manner, including because employees or contractors may not follow the controls we have implemented, the invasive techniques used change frequently or are not recognized until launched, and because security attacks can originate from a wide variety of sources and methods. Further, the sophistication, availability and use of artificial intelligence by threat actors may present an increased level of risk. Our remote or hybrid working arrangements may exacerbate these risks. Our employees, contractors, customers or other users of our systems are from time-to-time subject to fraudulent inducements by parties attempting to gain access to our data or that of our customers. Although we seek to have appropriate information security policies and systems in place, there is no assurance that our information security policies and systems in place can prevent unauthorized use or disclosure of confidential information, including nonpublic personal information. Any compromise of the security of our IT systems may result in loss of personally identifiable information, financial losses, loss of customers and the inability to transact business; could be costly and time-consuming to address and resolve; could expose us to liability for further compromise, damages, harm our reputation; and may subject us to regulatory scrutiny and/or expose us to civil litigation or regulatory action. If any of these were to occur, our business, financial condition and operating results could be materially adversely affected. Further, the technology errors and omissions, and insurance coverage we maintain may be unavailable or inadequate to fully cover claims and/or costs associated with incidents that may occur in the future.
10-K Feb 12, 2026
We have adopted information security procedures and controls to safeguard our systems and the information that we process, transmit and store, including multi-factor authentication and a new biometrics solution to authenticate employee login. Despite these efforts, we may not be able to anticipate or implement effective preventive measures against all cyber threats, or detect and contain a breach in a timely manner, including because employees or contractors may not follow the controls we have implemented, the invasive techniques used change frequently or are not recognized until launched, and because security attacks can originate from a wide variety of sources and methods. Further, the sophistication, availability and use of artificial intelligence by threat actors may present an increased level of risk. Our remote or hybrid working arrangements may exacerbate these risks. Our employees, contractors, customers or other users of our systems are, from time to time, subject to fraudulent inducements by
Paragraph 188 · 30% changed
Every version of it
10-K Feb 14, 2025In January 2014, the CFPB implemented the Dodd-Frank Act ATR mortgage provisions, which govern the obligation of lenders to determine a borrower's ability to pay when originating a mortgage loan covered by ATR. A subset of mortgages falling under the ATR that has certain low-risk characteristics are known as QMs. QMs that are deemed to have the lowest risk profiles are entitled to a safe-harbor presumption of compliance with the ability-to-pay requirements. In the fourth quarter of 2020, the CFPB released a series of final rules to (i) eliminate the temporary QM category, typically referred to as the "QM Patch", (ii) amend the definition of a General QM, and (iii) provide for a new, Seasoned QM category. The General QM final rule was effective on March 1, 2021 with an extended mandatory compliance date of October 1, 2022. However, the GSEs announced on April 8, 2021 that, for loan applications received on or after July 1, 2021, they will only purchase loans satisfying the New General QM Definition. See "Item 1, "Business - U.S. Mortgage Insurance Regulation - Other U.S. Regulation - Housing Finance Reform" above for a summary of the GSEs final rules related to QMs. The long-term effects of the expiration of the QM Patch and implementation of the General QM and Seasoned QM final rules could affect the residential mortgage market and demand for private mortgage insurance.
10-K Feb 12, 2026
amend the definition of a General QM, and (iii) provide for a new, Seasoned QM category. The General QM final rule was effective on March 1, 2021 with an extended mandatory compliance date of October 1, 2022. However, the GSEs announced on April 8, 2021 that, for loan applications received on or after July 1, 2021, they will only purchase loans satisfying the New General QM Definition. See “Item 1, “Business - U.S. Mortgage Insurance Regulation - Other U.S. Regulation - Housing Finance Reform” above for a summary of the GSEs final rules related to QMs. The long-term effects of the expiration of the QM Patch and implementation of the General QM and Seasoned QM final rules could affect the residential mortgage market and demand for private mortgage insurance.
Paragraph 143 · 28% changed
Every version of it
10-K Feb 14, 2025
We are exposed to many types of operational risk, including the risk of fraud or malfeasance by borrowers, employees and outsiders, including third-party service providers, clerical record-keeping errors and transactional errors. Our business depends on our employees and third parties to process a large number of transactions. We could be materially and adversely affected if one of our employees or one of our systems causes a significant operational breakdown or failure, either as a result of human error or where an individual purposefully sabotages or fraudulently manipulates our operations or systems. Third parties with whom we do business also could be sources of operational risk to us, including breakdowns or failures of such parties' own systems or employees. Given our hybrid and remote work arrangements of our employees and staff, the effectiveness of our compliance programs and overall ability to prevent and detect fraud or malfeasance by our employees or contractors may be diminished. Any of these occurrences could result in a diminished ability to operate our business, potential liability to customers, reputational damage and regulatory intervention, which could result in a material adverse effect on our financial position and operating results.
10-K Feb 12, 2026
We are exposed to many types of operational risk, including the risk of fraud or malfeasance by borrowers, employees and outsiders, including third-party service providers, clerical record-keeping errors and transactional errors. Our business depends on our employees and third parties to process a large number of transactions. We could be materially and adversely affected if one of our employees or one of our systems causes a significant operational breakdown or failure, either as a result of human error or where an individual purposefully sabotages or fraudulently manipulates our operations or systems. Third parties
MD&A
174 paragraphs · 11 new · 62 reworded · 45 gone · 10-K Feb 12, 2026 against Feb 14, 2025
New paragraph
Reworded (5% of its words or more)
Same or nearly
Paragraph 80 · 42% changed
Under the PMIERs, approved insurers must maintain available assets that equal or exceed minimum required assets, which is an amount equal to the greater of (i) $400 million or (ii) a total risk-based required asset amount. The risk-based required asset amount is a function of the risk profile of an approved insurer's RIF, assessed on a loan-by-loan basis and considered against certain risk-based factors derived from tables set out in the PMIERs, which is then adjusted on an aggregate basis for reinsurance transactions approved by the GSEs, such as with respect to our ILN Transactions, XOL Transactions and QSR Transactions. The aggregate gross risk-based required asset amount for performing, primary insurance is subject to a floor of 5.6% of performing primary adjusted RIF.
Paragraph 121 · 40% changed
Reinsurance recoverable increased year-on-year at December 31, 2025 as a result of an increase in ceded losses recoverable under our QSR Transactions. Transactions tied to an increase in our gross reserve for insurance claims and claim expenses during the year ended
Paragraph 130 · 40% changed
Net cash provided by operating activities increased in each successive year year-on-year primarily due to an increase in our net premium receipts and receipts, growth in our investment income, partially offset by an increase income and a reduction in the purchase of tax and loss bonds from period-to-period. Cash provided by operating activities for the year ended December 31, 2024, was further impacted bonds, partially offset by an increase in cash taxes paid, an increase in the interest payments made on the 2024 Notes and an increase in net claims paid and during the settlement of previously accrued short-term employee incentive awards. Cash provided by operating activities for the year ended December 31, 2023, was also impacted by a decline in short-term employee incentive payments. year.
Paragraph 101 · 37% changed
Underwriting and operating expenses increased marginally during the year ended December 31, 2024, 2025 primarily reflecting due to an increase in certain technology expenses and premium taxes, largely offset by a decrease in employee compensation costs costs, amortization and an adjustment to the pace of amortization of deferred policy acquisition costs, partially offset by an increase in ceding commissions received under our QSR Transactions depreciation expenses, and a decline in certain technology expenses. contract and professional fees.
Paragraph 96 · 32% changed
Net premiums earned increased sequentially during each successive year, the year ended December 31, 2025 primarily driven by due to growth in our monthly IIF and direct monthly pay premium receipts, partially offset by a decline in the contribution from single premium policy cancellations. Net impact of ceded premiums earned for the year ended December 31, 2024 further benefited from a year-on-year decline in the total premiums ceded under our third-party reinsurance treaties. transactions.
Paragraph 119 · 31% changed
Net deferred policy acquisition costs increased at December 31, 2025 due to the deferral of certain costs associated with the origination of new policies between the respective balance sheet dates and was partially policies, largely offset by the recognition of previously deferred policy acquisition costs. costs during the year ended December 31, 2025.
Paragraph 27 · 31% changed
Net premiums written increased 12% 9% and 4%, 12%, respectively, and net premiums earned increased 11% 7% and 7%, 11%, respectively, during the years ended December 31, 2024 2025 and 2023, 2024, primarily driven by growth in our monthly IIF and direct monthly pay premiums receipts. The sequential increase in net premiums earned during each successive year was premium receipts, partially offset by a decline in the contribution from single premium policy cancellations period-to-period. impact of ceded premiums written and earned under our third-party reinsurance transactions.
Paragraph 151 · 30% changed
NMIC’s principal sources of liquidity include (i) premium receipts on its insured portfolio and new business production, (ii) interest income on its investment portfolio and principal repayments on maturities therein, and (iii) existing cash and cash equivalent holdings. At December 31, 2024, 2025, NMIC had $2.6 $3.0 billion of cash and investments, including $10.2 $15.0 million of cash and cash equivalents. NMIC's principal liquidity demands include funds for the payment of (i) reimbursable holding company expenses, (ii) premiums ceded under our reinsurance transactions transactions, (iii) claims payments, and (iv) taxes as due or otherwise deferred through the purchase of tax and loss bonds. NMIC’s cash inflow is generally significantly in excess of its cash outflow in any given period. During the twelve-month period ended December 31, 2025, NMIC generated $414 million of cash flow from operations and received an additional $425 million of cash flow on the maturities, redemptions and sales of securities held in its investment portfolio. NMIC is not a party to any contracts (derivative or otherwise) that require it to post an increasing amount of collateral to any counterparty and NMIC’s principal liquidity demands (other than claims payments) generally develop along a
Paragraph 80 · 42% changed
10-K Feb 14, 2025
Under the PMIERs, approved insurers must maintain available assets that equal or exceed minimum required assets, which is an amount equal to the greater of (i) $400 million or (ii) a total risk-based required asset amount. The risk-based required asset amount is a function of the risk profile of an approved insurer's RIF, assessed on a loan-by-loan basis and considered against certain risk-based factors derived from tables set out in the PMIERs, which is then adjusted on an aggregate basis for reinsurance transactions approved by the GSEs, such as with respect to our ILN Transactions, XOL Transactions and QSR Transactions. The aggregate gross risk-based required asset amount for performing, primary insurance is subject to a floor of 5.6% of performing primary adjusted RIF.
10-K Feb 12, 2026
Under the PMIERs, approved insurers must maintain available assets that equal or exceed minimum required assets, which is an amount equal to the greater of (i) $400 million or (ii) a total risk-based required asset amount.
Paragraph 121 · 40% changed
10-K Feb 14, 2025
Reinsurance recoverable increased year-on-year as a result of an increase in ceded losses recoverable under our QSR Transactions.
10-K Feb 12, 2026
Reinsurance recoverable increased at December 31, 2025 as a result of an increase in ceded losses recoverable under our QSR Transactions tied to an increase in our gross reserve for insurance claims and claim expenses during the year ended
Paragraph 130 · 40% changed
10-K Feb 14, 2025
Net cash provided by operating activities increased in each successive year primarily due to an increase in our net premium receipts and growth in our investment income, partially offset by an increase in the purchase of tax and loss bonds from period-to-period. Cash provided by operating activities for the year ended December 31, 2024, was further impacted by an increase in cash taxes paid and the settlement of previously accrued short-term employee incentive awards. Cash provided by operating activities for the year ended December 31, 2023, was also impacted by a decline in short-term employee incentive payments.
10-K Feb 12, 2026
Net cash provided by operating activities increased year-on-year primarily due to an increase in our net premium receipts, growth in our investment income and a reduction in the purchase of tax and loss bonds, partially offset by an increase in cash taxes paid, an increase in the interest payments made on the 2024 Notes and an increase in net claims paid during the year.
Paragraph 101 · 37% changed
10-K Feb 14, 2025
Underwriting and operating expenses increased during the year ended December 31, 2024, primarily reflecting an increase in employee compensation costs and an adjustment to the pace of amortization of deferred policy acquisition costs, partially offset by an increase in ceding commissions received under our QSR Transactions and a decline in certain technology expenses.
10-K Feb 12, 2026
Underwriting and operating expenses increased marginally during the year ended December 31, 2025 primarily due to an increase in certain technology expenses and premium taxes, largely offset by a decrease in employee compensation costs, amortization and depreciation expenses, and certain contract and professional fees.
Paragraph 96 · 32% changed
10-K Feb 14, 2025
Net premiums earned increased sequentially during each successive year, primarily driven by growth in our monthly IIF and monthly pay premium receipts, partially offset by a decline in the contribution from single premium policy cancellations. Net premiums earned for the year ended December 31, 2024 further benefited from a year-on-year decline in the total premiums ceded under our reinsurance treaties.
10-K Feb 12, 2026
Net premiums earned increased during the year ended December 31, 2025 primarily due to growth in our monthly IIF and direct monthly pay premium receipts, partially offset by the impact of ceded premiums under our third-party reinsurance transactions.
Paragraph 119 · 31% changed
10-K Feb 14, 2025
Net deferred policy acquisition costs increased due to the deferral of certain costs associated with the origination of new policies between the respective balance sheet dates and was partially offset by the recognition of previously deferred policy acquisition costs.
10-K Feb 12, 2026
Net deferred policy acquisition costs increased at December 31, 2025 due to the deferral of certain costs associated with the origination of new policies, largely offset by the recognition of previously deferred policy acquisition costs during the year ended December 31, 2025.
Paragraph 27 · 31% changed
10-K Feb 14, 2025
Net premiums written increased 12% and 4%, respectively, and net premiums earned increased 11% and 7%, respectively, during the years ended December 31, 2024 and 2023, primarily driven by growth in our monthly IIF and monthly pay premiums receipts. The sequential increase in net premiums earned during each successive year was partially offset by a decline in the contribution from single premium policy cancellations period-to-period.
10-K Feb 12, 2026
Net premiums written increased 9% and 12%, respectively, and net premiums earned increased 7% and 11%, respectively, during the years ended December 31, 2025 and 2024, primarily driven by growth in our monthly IIF and direct monthly pay premium receipts, partially offset by the impact of ceded premiums written and earned under our third-party reinsurance transactions.
Paragraph 151 · 30% changed
10-K Feb 14, 2025
NMIC’s principal sources of liquidity include (i) premium receipts on its insured portfolio and new business production, (ii) interest income on its investment portfolio and principal repayments on maturities therein, and (iii) existing cash and cash equivalent holdings. At December 31, 2024, NMIC had $2.6 billion of cash and investments, including $10.2 million of cash and cash equivalents. NMIC's principal liquidity demands include funds for the payment of (i) reimbursable holding company expenses, (ii) premiums ceded under our reinsurance transactions (iii) claims payments, and (iv) taxes as due or otherwise
10-K Feb 12, 2026
NMIC’s principal sources of liquidity include (i) premium receipts on its insured portfolio and new business production, (ii) interest income on its investment portfolio and principal repayments on maturities therein, and (iii) existing cash and cash equivalent holdings. At December 31, 2025, NMIC had $3.0 billion of cash and investments, including $15.0 million of cash and cash equivalents. NMIC's principal liquidity demands include funds for the payment of (i) reimbursable holding company expenses, (ii) premiums ceded under our reinsurance transactions, (iii) claims payments, and (iv) taxes as due or otherwise deferred through the purchase of tax and loss bonds. NMIC’s cash inflow is generally significantly in excess of its cash outflow in any given period. During the twelve-month period ended December 31, 2025, NMIC generated $414 million of cash flow from operations and received an additional $425 million of cash flow on the maturities, redemptions and sales of securities held in its investment portfolio. NMIC is not a party to any contracts (derivative or otherwise) that require it to post an increasing amount of collateral to any counterparty and NMIC’s principal liquidity demands (other than claims payments) generally develop along a
A paragraph is matched with the one last year that shares the most of its words; under half in common makes it new. The paragraphs shown are the 8 reworded the most in each section.
The paragraph that changed most in each section
The redline
Marked against last year's 10-K: cut words struck through, new words highlighted.
Risk Factors173 words changed in this paragraph; it is 63% similar to last year's version.
We have adopted information security procedures and controls to safeguard our systems and the information that we process, transmit and store, including multi-factor authentication and a new biometrics solution to authenticate employee login. Despite these efforts, we may not be able to anticipate or implement effective preventive measures against all cyber threats, or detect and contain a breach in a timely manner, including because employees or contractors may not follow the controls we have implemented, the invasive techniques used change frequently or are not recognized until launched, and because security attacks can originate from a wide variety of sources and methods. Further, the sophistication, availability and use of artificial intelligence by threat actors may present an increased level of risk. Our remote or hybrid working arrangements may exacerbate these risks. Our employees, contractors, customers or other users of our systems are are, from time-to-time time to time, subject to fraudulent inducements by parties attempting to gain access to our data or that of our customers. Although we seek to have appropriate information security policies and systems in place, there is no assurance that our information security policies and systems in place can prevent unauthorized use or disclosure of confidential information, including nonpublic personal information. Any compromise of the security of our IT systems may result in loss of personally identifiable information, financial losses, loss of customers and the inability to transact business; could be costly and time-consuming to address and resolve; could expose us to liability for further compromise, damages, harm our reputation; and may subject us to regulatory scrutiny and/or expose us to civil litigation or regulatory action. If any of these were to occur, our business, financial condition and operating results could be materially adversely affected. Further, the technology errors and omissions, and insurance coverage we maintain may be unavailable or inadequate to fully cover claims and/or costs associated with incidents that may occur in the future.
Source: Item 1A, 10-K 0001547903-26-000011 vs Item 1A, 10-K 0001547903-25-000026
Accounting Policies172 words changed in this paragraph; it is 44% similar to last year's version.
NMIC entered into quota share reinsurance treaties effective September 1, 2016 and as modified April 1, 2019 (the 2016 QSR Transaction), January 1, 2018 (the 2018 QSR Transaction), April 1, 2020 and as amended January 1, 2024 (the 2020 QSR Transaction), January 1, 2021 (the 2021 QSR Transaction), October 1, 2021 (the 2022 QSR Transaction), July 1, 2022 (the 2022 Seasoned QSR Transaction), January 1, 2023 (the 2023 QSR Transaction), and January 1, 2024 (the 2024 QSR Transaction), and January 1, 2025 (the 2025 QSR Transaction), which we refer to collectively as the QSR Transactions. We earn profit and ceding commissions in connection with the QSR Transactions (see Note 6, “Reinsurance”). Profit commissions represent a percentage of the profits recognized by reinsurers that are returned to us, based on the level of claims and claim expenses that we cede. We recognize any profit commissions we earn as a decrease to ceded earned premiums. Ceding commissions are calculated as a percentage of ceded written premiums under the 2016 QSR Transaction or as a percentage of ceded earned premiums under the 2018, 2020, 2021, 2022, 2022 Seasoned, 2023 and 2024 QSR Transactions, and are intended to cover our costs of acquiring and servicing direct policies. We recognize any ceding commissions generated under the QSR Transactions in a manner consistent with our recognition of earnings on the underlying reinsured policies. We account for ceding commissions earned as a reduction to underwriting and operating expenses.
Source: Item 8, Note 2 – Summary of Accounting Principles, 10-K 0001547903-26-000011 vs Item 8, Note 2 – Summary of Accounting Principles, 10-K 0001547903-25-000026
MD&A106 words changed in this paragraph; it is 52% similar to last year's version.
On July 31, 2023, our Board of Directors authorized a $200 million repurchase program (the 2023 Repurchase Program), effective through December 31, 2025. On February 5, 2025, our Board of Directors authorized a new $250 million share repurchase program (excluding associated costs and applicable taxes, the (the 2025 Repurchase Program) Program), effective through December 31, 2027. 2027, and extended the effectiveness of the 2023 Repurchase Program through December 31, 2027 to align its remaining tenor with that of the 2025 Repurchase Program. The authorization provides us authorizations provide NMIH with the flexibility, based on market and business conditions, stock price and other factors, to repurchase stock stock, from time to time time, through open market repurchases, privately negotiated transactions, or other means, including pursuant to Rule 10b5-1 trading plans. Concurrent with the new authorization, our Board of Directors also approved an extension of our existing share repurchase programs through December 31, 2027 to align its remaining tenor with that of the new $250 million program.
Source: Item 7, 10-K 0001547903-26-000011 vs Item 7, 10-K 0001547903-25-000026
Legal Proceedings80 words changed in this paragraph; it is 73% similar to last year's version.
Source: Item 3, 10-K 0001547903-26-000011 vs Item 3, 10-K 0001547903-25-000026
Sentences and paragraphs added, removed or reworded
Every change, by type
Sentences and paragraphs of NMIH's Risk Factors and MD&A, 10-K Feb 12, 2026 against 10-K Feb 14, 2025. Each links to the text at sec.gov.
Quiet changes are sentences kept from last year with one to four words changed, at least one of them a hedge, a modal or a qualifier (may, could, will, not, significant, material…). A year or date rolling forward is not counted.
The full word list
adverse, adversely, all, although, anticipate, anticipates, any, approximately, believe, believes, can, cannot, certain, could, expect, expects, generally, however, if, intend, intends, largely, likely, many, material, materially, may, might, most, must, never, no, not, possible, primarily, probable, should, significant, significantly, some, substantial, substantially, unlikely, will, would
AddedRisk Factors
risk) in a loan materially increases the likelihood of a default on such a loan unless, and to the extent, there are other characteristics to mitigate the layered risk.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedRisk Factors
insurance due to house price appreciation, policy goals, other risk appetite decisions or otherwise, we could experience increased and unexpected turnover in our IIF, which could negatively impact our future revenues.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedRisk Factors
one or more of the PMIERs requirements, some of which do not have materiality thresholds. We certified to the GSEs by April 15, 2025 that NMIC was in full compliance with the PMIERs as of December 31, 2024.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedRisk Factors
current pricing and business practices. Further, failure to comply with the applicable regulations could lead to enforcement or disciplinary action, including the imposition of penalties and the revocation of our authorization to operate.
Read it in 10-K Feb 12, 2026 at sec.gov
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
Show the other 48
RewordedRisk Factors
If the GSEs and other mortgage investors change their view on the timing of cancellation of mortgage insurance due to house price appreciation, policy goals, other risk appetite decisions or otherwise, we could experience increased and unexpected turnover in our IIF, which could negatively impact our future revenues.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedRisk Factors
After a loan meets the conditions for rescission relief, we are contractually prohibited from exercising our rights of rescission for material underwriting defects and certain misrepresentations (including borrower fraud) made in connection with the origination of the insured loan and placement of our mortgage insurance.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedRisk Factors
In the fourth quarter of 2020, the CFPB released a series of final rules to (i) eliminate the temporary QM category, typically referred to as the "QM Patch", “QM Patch”, (ii) amend the definition of a General QM, and (iii) provide for a new, Seasoned QM category.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedRisk Factors
As a result of their size and market share, these entities originate a significant majority of high-LTV mortgages in the U.S. and, therefore, influence the size and pricing of the MI market.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedRisk Factors
In particular, in the current remote and hybrid working arrangements environment, our employees and vendors rely on the use of portable computers and mobile devices, which can be stolen, lost or misused, making information accessible through such devices more vulnerable to unauthorized access, including by employee malfeasance.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedRisk Factors
Our employees, contractors, customers or other users of our systems are are, from time-to-time time to time, subject to fraudulent inducements by parties attempting to gain access to our data or that of our customers.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedRisk Factors
While we believe our capital, premiums and investment earnings will provide a pool of resources sufficient to cover expected loss payments and we have made estimates regarding loss payments and potential claims, we cannot predict with certainty the ultimate number and magnitude of claims we experience.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedRisk Factors
Further, our business would be negatively impacted if we are unable to enhance our platform when necessary to support our primary business functions, including to match or exceed the technological capabilities of our competitors over time. time (including with respect to new and complex information technology such as artificial intelligence).
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedRisk Factors
NMIC also has an ongoing obligation to immediately notify the GSEs in writing upon discovery of its failure to meet one or more of the PMIERs requirements, some of which do not have materiality thresholds.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedRisk Factors
As a result of the higher mortgage interest rates in 2022 and 2023, we observed lower refinancing activities in the mortgage market compared to what we had observed in recent years prior to 2022, and therefore decreased turnover in our IIF.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedRisk Factors
If any indebtedness under the senior unsecured credit facilities or our senior notes is accelerated, we cannot assure you that our assets would be sufficient to repay such amounts in full, and the lenders and/or noteholders could foreclose on the collateral securing the obligations under the senior unsecured credit facilities and the senior notes, including, subject to regulatory approval, the stock of NMIC and Re One.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedRisk Factors
See Part II, Item 7, "Management's “Management's Discussion and Analysis of Financial Condition and Results of Operations - – Key Factors Affecting Our Results – Insurance Claims and Claim Expenses.
Read it in 10-K Feb 12, 2026 at sec.gov
Quiet changesRisk Factors
As one or more of the alternatives described above, or new alternatives that may enter the market, are chosen over MI, our revenues could be adversely impacted.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedMD&A
(5) Represents the settlement of reinsurance recoverables in conjunction with the termination and amendment of certain QSR transactions.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedMD&A
Our claims severity for the years ended December 31, 2025, 2024 and 2023 was 76%, 61% and 55%, respectively. The increase in claims severity for the year ended December 31, 2025, was primarily due to an increase in the proportion of claims related to loans originated in more recent years. These loans generally have less accumulated equity than loans from earlier vintages, which typically results in higher claims payments and an increase in claims severity.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedMD&A
Available assets reflect the financial resources of a mortgage insurer available to pay claims, and includes the most readily liquid assets held, such as cash, investments and other items as stipulated in the PMIERs. The credit provided for such assets is subject to adjustment based on several factors, including asset class, credit rating and portfolio concentration.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedMD&A
Effective April 1, 2025, we renewed and extended our existing seven-year IT service agreement with TCS, dated March 31, 2020, through March 31, 2032. Under the agreement, TCS provides IT services across such functions as application development and support, infrastructure support, and information security. Our engagement with TCS has enhanced our ability to provide innovative IT solutions for our internal and external constituents, and has allowed us to realize cost efficiencies by leveraging TCS’s global platform.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedMD&A
Comparisons between the years ended December 31, 2024 and 2023 have been omitted within “Consolidated Results of Operations” from this Form 10-K, but can be found in Part II, Item 7, “Management's Discussion and Analysis of Financial Condition and Results of Operations” in our Annual Report on Form 10-K for the year ended December 31, 2024, filed with the SEC.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedMD&A
For the years ended December 31, $ Change % Change Non-GAAP financial measures (5) 2025 2024 2025 vs. 2024 ($ In Thousands, except for per share data) Adjusted income before tax $ 499,372 $ 470,354 $ 29,018 6% Adjusted net income 388,584 365,591 22,993 6 Adjusted diluted EPS 4.92 4.50 0.42 9
Read it in 10-K Feb 12, 2026 at sec.gov
AddedMD&A
Net software and equipment decreased at December 31, 2025 due to the amortization of previously capitalized amounts, partially offset by the capitalization of certain software and equipment expenditures during the year ended December 31, 2025.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedMD&A
December 31, 2025, partially offset by the settlement of loss recoverable in conjunction with the termination and amendment of certain QSR transactions.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedMD&A
We are subject to certain covenants under the 2024 Revolving Credit Facility, including: a maximum debt-to-total capitalization ratio of 35%, a minimum consolidated net worth requirement (as defined therein), and a requirement to maintain compliance with the financial standards prescribed by the PMIERs (subject to any GSE approved waivers). We were in compliance with all covenants at December 31, 2025.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedMD&A
Available assets reflect the financial resources of a mortgage insurer available to pay claims, and includes the most readily liquid assets held, such as cash, investments and other items as stipulated in the PMIERs. The credit provided for such assets is subject to adjustment based on several factors, including asset class, credit rating and portfolio concentration.
Read it in 10-K Feb 12, 2026 at sec.gov
AddedMD&A
We believe that we have sufficient liquidity available at both NMIH and NMIC to meet our operating cash and capital obligations over the next 12 months.
Read it in 10-K Feb 12, 2026 at sec.gov
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RewordedMD&A
Net cash provided by operating activities increased in each successive year year-on-year primarily due to an increase in our net premium receipts and receipts, growth in our investment income, partially offset by an increase income and a reduction in the purchase of tax and loss bonds from period-to-period. bonds, partially offset by an increase in cash taxes paid, an increase in the interest payments made on the 2024 Notes and an increase in net claims paid during the year.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedMD&A
Accounts payable and accrued expenses increased decreased at December 31, 2025 primarily due to a reduction in accrued and unpaid interest on the 2024 Notes, which is payable semi-annually beginning in February 2025, as well as a decrease in taxes payable and the settlement of previously accrued compensation expenses, partially offset by an increase in reinsurance premiums payable, partially offset by the settlement of certain contractual payables payable during the year ended December 31, 2024. 2025.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedMD&A
Net investment income increased sequentially during each successive year, the year ended December 31, 2025 primarily driven by due to growth in the size of our total invested asset base, as well as an increase in the book yield of our investment portfolio tied to the deployment of new cash flows and reinvestment of rolling maturities at incrementally higher rates, as well as growth in the size of our total invested asset base. rates.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedMD&A
On February 5, 2025, our Board of Directors authorized a new $250 million share repurchase program (excluding associated costs and applicable taxes, the (the 2025 Repurchase Program) Program), effective through December 31, 2027. 2027, and extended the effectiveness of the 2023 Repurchase Program through December 31, 2027 to align its remaining tenor with that of the 2025 Repurchase Program.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedMD&A
NIW increased 6% and 14%, respectively, for the year years ended December 31, 2024 increased 14% compared to the year ended December 31, 2023, 2025 and 2024, primarily due to growth in our customer franchise and market presence tied to the increased penetration of existing customer accounts and new customer activations. activations as well as an increase in the size of the total mortgage insurance market.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedMD&A
Percentage of portfolio's fair value December 31, 2024 2025 December 31, 2023 2024 Corporate debt securities 64% 67% 61% Municipal debt securities 19 23 25 Cash, cash equivalents, and short-term investments 5 5 U.S. treasury securities and obligations of U.S. government agencies 10 4 7 Cash, cash equivalents, and short-term investments 4 5 Asset-backed securities 2 1 2 U.S agency mortgage-backed securities 1 — Total 100% 100%
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedMD&A
Net premiums earned increased sequentially during each successive year, the year ended December 31, 2025 primarily driven by due to growth in our monthly IIF and direct monthly pay premium receipts, partially offset by a decline in the contribution from single premium policy cancellations. impact of ceded premiums under our third-party reinsurance transactions.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedMD&A
Net premiums written increased 12% 9% and 4%, 12%, respectively, and net premiums earned increased 11% 7% and 7%, 11%, respectively, during the years ended December 31, 2024 2025 and 2023, 2024, primarily driven by growth in our monthly IIF and direct monthly pay premium receipts, partially offset by the impact of ceded premiums receipts. written and earned under our third-party reinsurance transactions.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedMD&A
At December 31, 2024, 2025, we had issued 2,086 2,193 Master Policies and established 1,621 active customer relationships, Policies, compared to 1,974 2,086 and 1,503, respectively, 1,974, as of December 31, 2023 2024 and 1,875 and 1,434, respectively, as of December 31, 2022. 2023, respectively.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedMD&A
Average reserve per default increased from December 31, 2022 2024 to December 31, 2023, 2025, primarily due to changes in the composition of our default inventory as measured by the size, vintage and current estimated LTV of defaulted loans, as well as the proportion of such loans benefiting from a forbearance program granted in response to a financial hardship related to COVID-19. between measurement dates.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedMD&A
Insurance claims and claim expenses increased during each successive year, the year ended December 31, 2025 primarily driven by due to an increase in the number of newly defaulted loans that emerged in each successive period during the year and the establishment of initial reserves against such loans, as well as an increase in the average case reserve held against previously defaulted loans that aged in their delinquency status through the periods, and was status, partially offset by the release of a portion of the reserves we established for anticipated claims payments in prior periods in connection with cure activity and the ongoing analysis of recent loss development trends.
Read it in 10-K Feb 12, 2026 at sec.gov
RewordedMD&A
Sources
The two latest 10-Ks on EDGAR, section by section. Each change links to the text at sec.gov.
Also
New risk factors: paragraphs with nothing like them last year, quoted in full.
Work with it
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/NMIH/export.csv") into a cell.