Form 10-K for the Year Ended December 31, 2022
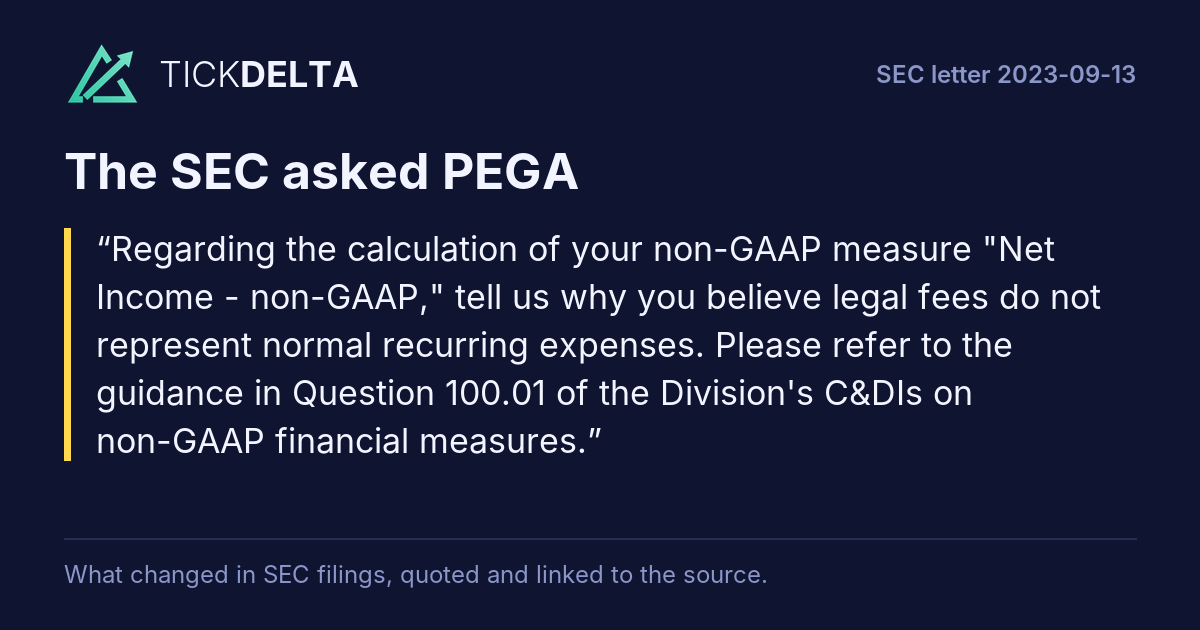
Regarding the calculation of your non-GAAP measure "Net Income - non-GAAP," tell us why you believe legal fees do not represent normal recurring expenses. Please refer to the guidance in Question 100.01 of the Division's C&DIs on non-GAAP financial measures.
The Company respectfully acknowledges the Staff’s comment. As stated in Question 100.01, “When evaluating what is a normal, operating expense, the staff considers the nature and effect of the non-GAAP adjustment and how it relates to the company’s operations, revenue generating activities, business strategy, industry and regulatory environment.”Read in the reply
All legal costs determined to be normal recurring cash expenses necessary to operate the Company’s business are included when calculating Net Income - non-GAAP financial measures consistent with Question 100.01.Rest of the answer
In 2022, $3.4 million in legal expenses were included in Net Income - non-GAAP, as these were determined to be normal operating expenses.
The legal fees adjustment excluded from Net Income - non-GAAP are related to the Appian litigation and associated legal proceedings as these matters were no longer normal, recurring, cash operating expenses as of the fourth quarter of 2021. When the Company originally began incurring costs for these matters, they were assessed to be ordinary routine business litigation expenses incidental to its business and another instance of ongoing routine litigation between the parties dating back to 2015. However, the nature of these claims were reassessed beginning with the submission by Appian of a damages report on November 24, 2021 in which Appian asserted the Company was liable for $5.6 billion in Company profits over the time period covered by Appian’s claims.
In determining whether expenses directly related to these matters constitute normal, recurring, cash operating expenses necessary to operate a registrant’s business, the Company considered the following factors:
•The Company’s customary practice is to include the cost of litigation in its non-GAAP financial results. The Company has included, and continues to include, legal expenses that are normal, recurring, cash operating expenses necessary to operate the Company’s business. As previously noted, in 2022, the Company incurred legal expenses of $3.4 million that were included in Net Income – non-GAAP. The legal expenses excluded from Net Income - non-GAAP are only a subset of the Company’s legal expenses.
•The Company began excluding Appian-related litigation expenses from non-GAAP income when the case fundamentally changed in nature. When Appian commenced litigation against the Company in Virginia in May 2020, the asserted damages were limited to $90 million. On November 24, 2021, however, Appian submitted an initial damages report asserting the Company was liable for $5.6 billion in Company profits over the time period covered by Appian’s claims. The November 24, 2021 damages report represented a change in the nature of the case and was the first indication to the Company that the Appian-related litigation expenses were not ordinary, routine business litigation incidental to the Company’s business. In February 2022, the court allowed an amendment of the complaint to assert a claim for $3 billion. The Company believed, and continues to believe, that it would prevail at trial and now on appeal, because of its strong defenses, including that the information allegedly misappropriated by the Company was widely available and any damages were not supported by the necessary legal standard of proximate cause, among other defenses.
•The adjustment for litigation expense provides meaningful information to investors. The Company believes that the adjustment would be beneficial for users of the Company’s financial statements and investors because the Appian related litigation expenses are not related to the Company’s underlying or ongoing business operational performance. Adjusting for the impact of these expenses improves period-to-period comparability of the Company’s results from business operations and provides useful supplemental information to understand underlying financial results and performance. For example, in the quarter ended March 31, 2022, the Company expended $17.4 million in legal fees related to the Appian litigation, while in the quarter ended March 31, 2021, the Company expended $2 million. Without the identification and exclusion of these expenses, the Company believes that the comparability of its financial results from period to period would be substantially diminished, and that exclusion of these expenses enhances the understanding of trends in operating the business.
•While the Appian-related litigation expenses have been incurred over an extended period of time, they relate to a single, discrete matter. While impacting more than one fiscal period, the Company has not viewed the Appian-related litigation expenses as recurring because they are related to a single, discrete matter.
•The claims asserted at trial did not impact the ability of the Company or its customers to use the Company’s products or services. The claims asserted at trial did not affect the current or future ability of the Company to use, sell or develop its products or services, or the current or future ability of its customers to use the Company’s products or services. Accordingly, the expenses incurred were not normal expenses necessary to permit the Company to operate its business, but rather extraordinary expenses related to legal proceedings unrelated to the ongoing operation of the Company’s business.
For each of these reasons, the Company believes that the adjustment with respect to Appian-related legal fees does not cause Net Income - non-GAAP to be misleading or inconsistent with the guidance in Question 100.01 of the Non-GAAP Financial Measures Compliance and Disclosure Interpretations. The Company believes that presenting Net Income - non-GAAP adjusted for these costs, when read in conjunction with the Company’s GAAP measures, provides investors with useful information about the Company’s operating performance and does not obscure trends in the underlying business.
First report after the company's reply of Sep 27, 2023: 10-Q filed Oct 25, 2023 ↗, against the 10-Q filed Jul 26, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Your calculation of free cash flow differs from the typical calculation of this measure (i.e., cash flows from operations less capital expenditures). In order to avoid potential confusion, please revise the title of your non-GAAP measure to adjusted free cash flow or something similar. Refer to Question 102.07 of the Division's Non-GAAP Compliance and Disclosure Interpretations.Rest of the question
Please also apply this comment to your future quarterly earnings releases filed under Form 8-K.
The Company respectfully acknowledges the Staff’s comment and will define Free Cash Flow as cash flow from operations less capital expenditures in future filings.Read in the reply
First report after the company's reply of Sep 27, 2023: 10-Q filed Oct 25, 2023 ↗, against the 10-Q filed Jul 26, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Tell us and disclose why you believe it is appropriate to present Free Cash Flow as a performance measure rather than a liquidity measure.
The Company respectfully acknowledges the Staff’s comment, and upon further consideration, the Company will consider it a liquidity measure and define Free Cash Flow as cash flows from operations less capital expenditures in future filings.Read in the reply
First report after the company's reply of Sep 27, 2023: 10-Q filed Oct 25, 2023 ↗, against the 10-Q filed Jul 26, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
We note that your measure of free cash flows excludes legal fees, interest on convertible senior notes, capital advisory fees, and sales and marketing event cancellation fees. Tell us how you considered Item 10(e)(ii)(A) of Regulation S-K, which prohibits the exclusion of charges or liabilities that require, or may require, cash settlement from a liquidity measure. Please explain or revise to remove such adjustments.
The Company respectfully acknowledges the Staff’s comment and will define Free Cash Flow as cash flow from operations less capital expenditures in future filings.Read in the reply
First report after the company's reply of Sep 27, 2023: 10-Q filed Oct 25, 2023 ↗, against the 10-Q filed Jul 26, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Regarding your presentation of free cash flow margin, disclose with equal or greater prominence, the most directly comparable financial measure calculated and presented in accordance with GAAP. Refer to Item 10(e)(i)(A) of Regulation S-K and Question 102.10 of the Division's C&DIs on non-GAAP financial measures.Rest of the question
You should also provide a reconciliation with this directly comparable GAAP financial measure pursuant to Item 10(e)(i)(B) of Regulation S-K.
The Company respectfully acknowledges the Staff’s comment and the guidance in Item 10(e)(i)(A) of Regulation S-K, Item (10)(e)(i)(B) of Regulation S-K, and Question 102.10 of the Compliance and Disclosure Interpretations and will, in future filings, show Operating Cash Flow Margin with equal or greater prominence to Free Cash Flow Margin.Read in the reply
First report after the company's reply of Sep 27, 2023: 10-Q filed Oct 25, 2023 ↗, against the 10-Q filed Jul 26, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Explain for us how "an increase in consultant availability" decreased the gross profit percentage of your already narrow consulting gross margin.
The Company respectfully acknowledges the Staff’s comment and advises the Staff that consultant availability refers to consultants not assigned to revenue-generating projects. Consultant compensation (i.e. salaries and benefits) is fixed. An increase in consultant availability reduces the Company's consulting gross margin since there is no associated revenue.Read in the reply
First report after the company's reply of Sep 27, 2023: 10-Q filed Oct 25, 2023 ↗, against the 10-Q filed Jul 26, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Based upon the disclosure in Note 4, it appears you classified within current assets unbilled receivables of $213,719 based upon an expected billing date of 1 year or less. While your expectation of billing may be within one year, the expected timing of collection is not clear. Please clarify your disclosure and advise us.Rest of the question
Also, if applicable, explain why the anticipated timing of collection of unbilled receivables is not your basis for classification within current assets.
The Company respectfully acknowledges the Staff’s comment and plans to update its disclosure in future filings. The "Unbilled receivables by expected billing date" table in Note 4 is presented based on the contractually agreed upon due date of the invoice, which is also the expected collection date. The Company issues customer invoices before the contractually agreed upon due date based on contractual payment terms.Read in the replyRest of the answer
The Company’s policy is to reclassify receivables from unbilled to accounts receivable on the contractually agreed upon due date of the invoice, which is the service period start date. An invoice is expected to be collected at the time it is due. As shown in the table below, the service period start date, invoice due date, and expected collection date are the same.
Example:
Payment Terms Invoice Issuance Date Service Period Start Date Contractually Agreed Upon Due Date/Expected Collection Date
Net 30 1-Dec-22 1-Jan-23 1-Jan-23
Net 60 1-Nov-22 1-Jan-23 1-Jan-23
Net 90 2-Oct-22 1-Jan-23 1-Jan-23
In future filings, the Company will label the table heading on page 48 as "Unbilled receivables by expected collection date:".
First report after the company's reply of Sep 27, 2023: 10-Q filed Oct 25, 2023 ↗, against the 10-Q filed Jul 26, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Indicate on the face of your balance sheet that accounts receivable and unbilled receivables are net of an allowance for doubtful accounts or advise us. You should disclose the allowance amounts, if applicable. Refer to Rule 5-02.4 of Regulation S-X.
The Company respectfully acknowledges the Staff’s comment and advises the Staff that the Company considers the guidance in ASC 326 “Measurement of Credit Losses on Financial Instruments” on an ongoing basis; however, it historically has not, nor does it expect to record a material allowance for doubtful accounts (credit losses) on its accounts receivable and unbilled receivables.Read in the reply
In future filings, the Company will include “, net” within the “Accounts receivable” and “Unbilled receivables” captions on the face of the balance sheet.Rest of the answer
If the allowance for doubtful accounts becomes material in the future, the Company will disclose these amounts.
First report after the company's reply of Sep 27, 2023: 10-Q filed Oct 25, 2023 ↗, against the 10-Q filed Jul 26, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Please clarify what performance obligations are satisfied but not billed and advise us. You should expand the disclosure in the table on page 44, under the heading "When payment is typically due," to fully address all types of unbilled revenues.Rest of the question
Also, indicate in the disclosure at the bottom of page 44 and elsewhere, where applicable, the nature of the revenues where "recognition timing differs from the timing of payment due to extended payment terms or fees that are non-proportional to the associated usage of software licenses."
to the second part of your comment, the Company believes the table presented on page 44 of the Form 10-K fulfills the requirements outlined within ASC 606-10 paragraph 50-9, which states, “An entity shall explain how the timing of satisfaction of its performance obligations (see paragraph 606-10-50-12(a)) relates to the typical timing of payment (see paragraph 606-10-50-12(b)) and the effect that those factors have on the contract asset and the contract liability balances.Read in the replyRest of the answer
The explanation provided may use qualitative information.” Specifically, 606-10-50-12(a) is satisfied in column 3 of this table labeled “When performance obligation is typically satisfied,” and 606-10-50-12 (b) is satisfied in column 4 of this table labeled “When payment is typically due” and paragraph titled “Significant financing components” on page 44 of the Form 10-K.
In response to the third part of the comment, the Company’s instances where “recognition timing differs... due to extended payment terms” are infrequent and immaterial. These instances most commonly include multi-year Pega Cloud or term license agreements in which the timing of payment is not proportional to the associated usage of the license and the Company has evaluated for the existence of a separate financing component. This is disclosed in the section “Significant financing components” on page 44 of the Form 10-K.
First report after the company's reply of Sep 27, 2023: 10-Q filed Oct 25, 2023 ↗, against the 10-Q filed Jul 26, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Tell us and clarify in your disclosure how you changed your ACV calculation methodology for maintenance and all contracts less than 12 months. Explain how the new methodology aligns with other contract types. Quantify how previously disclosed ACV amounts have been updated.
In 2023, the Company revised its ACV methodology for maintenance and all contracts less than 12 months as its overall client renewal rate exceeds 90%. This simplification, made possible by improvements to the Company’s financial systems, ensures that ACV for all contract types and lengths is consistently calculated as the total contract value divided by the duration in years. Previously, ACV for maintenance was calculated as the maintenance revenue for the quarter then ended, multiplied by four, and ACV for contracts less than 12 months was equal to the contract’s total value.Read in the replyRest of the answer
The Company believes the simplified methodology better represents the current value of its contracts and better aligns its definition with comparable companies.
The impact of the change was less than $3 million or 0.3% of Total ACV for all quarters in 2022:
(in millions)
First report after the company's reply of Sep 27, 2023: 10-Q filed Oct 25, 2023 ↗, against the 10-Q filed Jul 26, 2023 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: closing letter, 2023-10-17