tickdelta
Sign in

Tickdelta is free for now. Sign up and get Pro free

← Screener

PMPhilip Morris International

Consumer staples · Tobacco · NYSE

Philip Morris International Inc. is a Virginia holding company incorporated in 1987. 10-K, Item 1

Employees
84,900
Headquarters
Stamford, CT
Next results
around Feb 5, 2027
Compare with peers → Embed

When the SEC's staff reviews a filing, it writes to the company with numbered questions, and the company answers each one in a letter. SEC publishes the exchange once the review is over, at least 20 business days later. Below: what the staff asked PM, and the company's answer to each question, quoted from the letters. A question is not an accusation; most reviews end with the company adding detail to its next filing.

Form 10-K for the Year Ended December 31, 2022

2023-06-29 to 2023-07-13 · 6 questions · 1 letter from the SEC, 1 from the company
Review closed 2023-07-13
Results discussion (MD&A)InventoryRisk factorsLiquidity and cashRevenueNon-GAAP measures
Risk Factors · A sustained period of elevated inflation, page 13
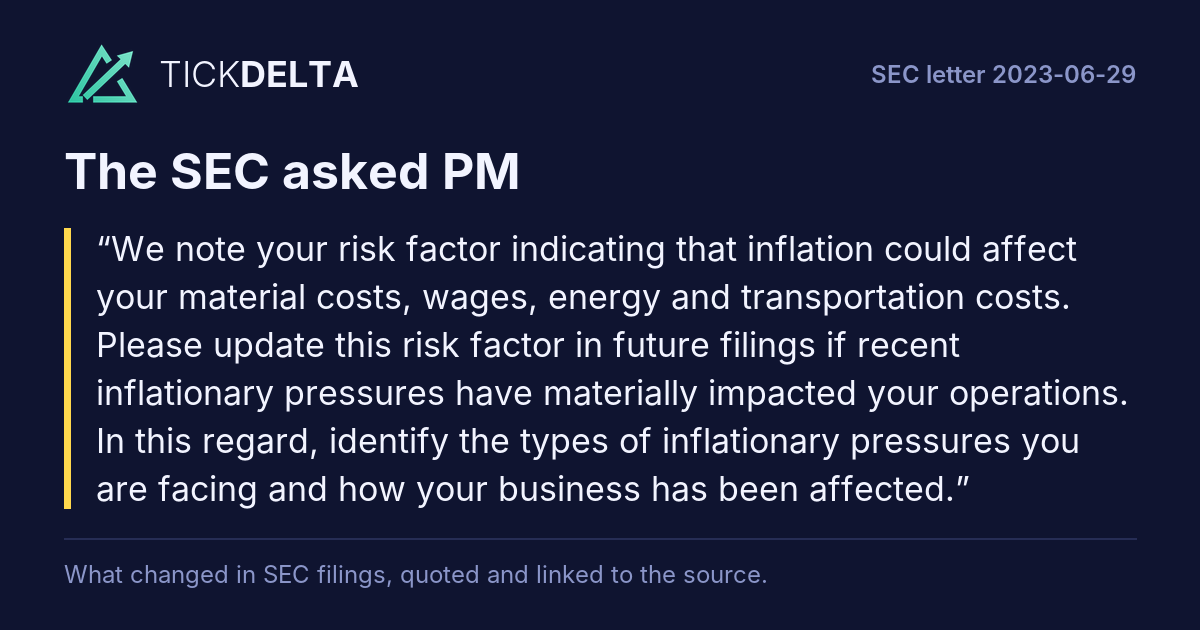
SEC asked (1)
We note your risk factor indicating that inflation could affect your material costs, wages, energy and transportation costs. Please update this risk factor in future filings if recent inflationary pressures have materially impacted your operations. In this regard, identify the types of inflationary pressures you are facing and how your business has been affected.
PM answered
We acknowledge the Staff’s comment and respectfully note that we have experienced and disclosed inflationary pressures in our Form 10-K, including: growing pressures on the cost of certain direct materials, wages, energy, transportation, and logistics as well as an increased cost of capital due to interest rate increases driven by the response to increased inflation.
Rest of the answer

While the net result of the inflationary impacts and our efforts to mitigate these impacts were not material to the Company during the covered periods, in future filings the Company will update its risk factors to describe the material impact of inflationary pressures on the Company’s operations, if any, including by identifying the types of any such inflationary pressures and how the business may have been affected.

Read in the reply ↗
In its next report

First report after the company's reply of 2023-07-12: 10-Q filed 2023-07-27 ↗, against the 10-Q filed 2023-04-26 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.
PMI Shipment Volume, page 34
SEC asked (2)
We note your statement that following the deconsolidation of RBH, you continue to report the volume of brands sold by RBH in which other PMI subsidiaries own the trademark. Please revise to quantify the amounts of volume of RBH included in your tables.
PM answered
As discussed in Item 8, Note 18. Contingencies - CCAA Proceedings and Stay of Tobacco-Related Cases Pending in Canada - of our 2022 Form 10-K, our subsidiary, Rothmans, Benson & Hedges Inc. (“RBH”), sought protection in the Ontario Superior Court of Justice under the Companies’ Creditors Arrangement Act (“CCAA”) on March 22, 2019. CCAA is a Canadian federal law that permits a Canadian business to restructure its affairs while carrying on its business in the ordinary course.
Rest of the answer

As a result, RBH's financial results have been deconsolidated from our consolidated financial statements since March 22, 2019.

Following the deconsolidation of RBH, we have continued to report the volume and corresponding revenues (primarily royalty revenues) of brands sold by RBH for which other PMI subsidiaries are the trademark owners. These include HEETS, Next, Philip Morris and Rooftop.

The volume of these brands sold by RBH is not significant to the volume of the consolidated Company (i.e., cigarettes and heated tobacco units combined). Specifically, the volume of these brands sold by RBH represented approximately 0.4%, 0.5% and 0.5% of our total consolidated cigarettes and heated tobacco units volume for the years ended 2022, 2021 and 2020, respectively. For this reason, we respectfully believe that separate disclosure of the unit volume of these brands sold by RBH in our tabular disclosure or as a footnote to our tabular disclosure is not warranted. Going forward, we will continue to monitor the significance of this volume to the consolidated Company to determine whether additional disclosures should be provided.

In future filings, we will expand the disclosure referenced by the Staff to include the language underlined below:

Following the deconsolidation of our Canadian subsidiary, we continue to report the volume and corresponding royalty revenues of brands sold by RBH for which other PMI subsidiaries are the trademark owners. These include HEETS, Next, Philip Morris and Rooftop. The volume and corresponding royalty revenues for these brands sold by RBH were not material to the Company for all periods presented.

Read in the reply ↗
In its next report

First report after the company's reply of 2023-07-12: 10-Q filed 2023-07-27 ↗, against the 10-Q filed 2023-04-26 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Management's Discussion and Analysis of Financial Condition and Results of Operations · Financial Summary, page 39
SEC asked (3)
Your disclosure indicates that you have faced significant inflationary forces and that such inflationary pressures are growing and could continue in upcoming quarters. In this regard, please disclose any known trends or uncertainties that have had or are reasonably likely to have a material impact on your cash flows, liquidity, capital resources, cash requirements, financial position, or results of operations
Rest of the question

arising from, related to, or caused by inflation. Trends or uncertainties may include the combined impact of inflation on cost of sales, gross profit, inventory and taxes.

PM answered
We acknowledge the Staff’s comment and in future filings, the Company will include additional disclosures regarding the principal factors contributing to inflationary pressures and the resulting impact to the Company if there are any known trends or uncertainties that have had or are reasonably likely to have a material impact on our financial results which have not been previously disclosed.

As we have previously reported, our 2022 financial results were impacted by inflationary forces, despite specific actions taken to mitigate them.
Rest of the answer

Such forces principally consisted of the inflationary pressures described in the Form 10-K and our response to Comment 1. While we expect certain inflationary elements to ease over the course of the year, we anticipate that our 2023 results will likely continue to be impacted by inflationary forces (particularly related to tobacco leaf given the impact of longer inventory durations and higher prices of direct materials, as discussed below in our response to Comment 4), which in the aggregate could be material to our business and financial results.

While the net result of the inflationary impacts and our mitigation efforts were not material to the Company's financial results during the covered periods, as noted above, additional disclosures will be included in future filings to the extent any of the above items or other known trends or uncertainties have had or are reasonably likely to have a material impact on our financial results.

Read in the reply ↗
In its next report

First report after the company's reply of 2023-07-12: 10-Q filed 2023-07-27 ↗, against the 10-Q filed 2023-04-26 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Management's Discussion and Analysis of Financial Condition and Results of Operations · Financial Summary, page 39
SEC asked (4)
In a related matter, please expand your disclosure in future filings to identify the principal factors contributing to the inflationary pressures you have experienced and clarify the resulting impact to the company. In addition, update your disclosure in future filings to identify actions planned or taken, if any, to mitigate inflationary pressures.
PM answered
We acknowledge the Staff’s comment and respectfully advise the Staff that, in future filings, the Company will include appropriate additional disclosures regarding the principal factors contributing to inflationary pressures and clarify the resulting impact to the Company including actions planned or taken to mitigate inflationary pressures.
Rest of the answer

To illustrate, below is an example of how we are planning to disclose such impacts in our upcoming filings:

Inflationary impacts driven by higher wages have resulted from merit increases that reflect local inflation as we continuously evaluate our compensation and benefit offerings to be competitive with the current market. Increased transportation costs resulted from increased shipping rates for all modes of transportation (air, ocean and inland) due to ocean and air capacity constraints. Increases in cost of sales resulted from higher cost of direct materials due to the pass on of energy, transportation, labor and commodity price increases from suppliers as well as increases in utility costs, including gas and electricity prices, primarily in Europe resulting from the war in Ukraine. Raw materials such as tobacco leaf have longer inventory durations which resulted in insignificant inflationary impacts to our cost of sales in 2022; however tobacco leaf purchases in both 2022 and 2023 have been at higher prices due to inflationary impacts on fertilizer prices and labor costs, thus resulting in increases in the cost of inventory with corresponding impacts on our financial results expected in 2023. In addition, our cash flow from operations was impacted by the net working capital investment related to the procurement of tobacco leaf inventory and higher cost of direct materials, which is expected to continue in 2023.

Mitigation efforts have included (i) indexation clauses related to commodity costs and energy pricing within contracts, (ii) tactical inventory purchases, (iii) identification of new suppliers in different geographical locations for incremental sourcing, (iv) increasing tobacco leaf inventory durations to secure additional volumes at favorable prices, (v) optimizing the mix of tobacco leaf origins and suppliers, (vi) continuous evaluation of shipping routes and methods of shipment, (vii) supplier negotiations, (viii) variable contract durations for energy costs, (ix) hedging strategies, and (x) other pricing, productivity and procurement initiatives.

Read in the reply ↗
In its next report

First report after the company's reply of 2023-07-12: 10-Q filed 2023-07-27 ↗, against the 10-Q filed 2023-04-26 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Item. 8 Financial Statements and Supplementary Data · Consolidated Statement of Earnings, page 70
SEC asked (5)
We note your presentation of revenues, including excise taxes on the face of your statement of earnings. We also note that you have elected to present revenue on net basis of these excise taxes. Please tell us why you believe the gross presentation of revenues does not represent a non-GAAP measure.
PM answered
We acknowledge the Staff’s comment and note that, as disclosed in Item 8, Note 2. Summary of Significant Accounting Policies of our Form 10-K, we have elected to present revenues on a net of excise tax basis by excluding excise taxes collected from customers from the measurement of the transaction price.
Rest of the answer

Excise taxes and related revenues, including excise taxes on the face of the statement of earnings, are presented in accordance with our interpretation of the SEC rules stated in Item 10(e)(5) of Regulation S-K and Item 5-03 of Regulation S-X, pursuant to which we believe that the gross presentation of revenues does not represent a non-GAAP financial measure.

Regulation S-K Item 10(e)(5) states that “non-GAAP financial measures exclude financial measures required to be disclosed by GAAP, [SEC] rules, or a system of regulation of a government or governmental authority or self-regulatory organization that is applicable to the registrant.” Additionally, for the purpose of the presentation of revenues in PMI’s Consolidated Statements of Earnings, we have considered the guidance provided in Regulation S-X Item 5-03(1) “Net sales and gross revenues” which states: “If the total of sales and revenues reported under this caption includes excise taxes in an amount equal to 1 percent or more of such total, the amount of such excise taxes shall be shown on the face of the statement parenthetically or otherwise”.

We interpret Regulation S-X Item 5-03(1) to require the presentation of gross revenue, necessitating the presentation of excise taxes on the face of the statement of earnings. We also believe that including excise taxes within the statement promotes comparability with other filers from excise paying industries.

We respectfully note that revenues including excise taxes are not used by management as a non-GAAP measure to evaluate PMI’s financial performance or as a metric used in determining management compensation. Consequently, we believe that Regulation S-K Item 10(e)(1)(i)(C) does not apply, which states “[t]he registrant must include the following in the filing: [a] statement disclosing the reasons why the registrant's management believes that presentation of the non-GAAP financial measure provides useful information to investors regarding the registrant's financial condition and results of operations.”

In consideration of the above, we believe that revenues including excise taxes is not a non-GAAP measure. This measure is added to the face of the statement of earnings to comply with the SEC excise taxes disclosure regulations and to promote transparent disclosure and comparability with other filers from excise paying industries.

Notwithstanding the above, in accordance with the Staff's comment, in future filings we will remove revenues including excise taxes from the face of the statement of earnings and present excise taxes parenthetically or in a footnote to the statement of earnings.

Read in the reply ↗
In its next report

First report after the company's reply of 2023-07-12: 10-Q filed 2023-07-27 ↗, against the 10-Q filed 2023-04-26 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Note 2. Summary of Significant Accounting Policies · Inventories, page 80
SEC asked (6)
You disclose that inventories are stated at the lower of cost or market. Please clarify if you recognize inventory at the lower of cost or market, or the lower of cost or net realizable value, and revise your disclosures accordingly. See ASC 330-10-351B and ASC 905-330-30-1.
PM answered
We acknowledge the Staff's comment and confirm that our inventories are stated at the lower of cost or net realizable value in accordance with ASC 330-10-35-1B. The Company will revise its disclosure in future periodic reports, beginning with our Form 10-K for the fiscal year ending December 31, 2023. Read in the reply ↗
In its next report

First report after the company's reply of 2023-07-12: 10-Q filed 2023-07-27 ↗, against the 10-Q filed 2023-04-26 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Also in this review: closing letter, 2023-07-13
Form 10-K

2022-07-27 to 2022-10-12 · 12 questions · 2 letters from the SEC, 2 from the company
Review closed 2022-10-12
ClimateResults discussion (MD&A)Risk factorsLegal and contingencies
After reviewing your response to these comments, we may have additional comments. General
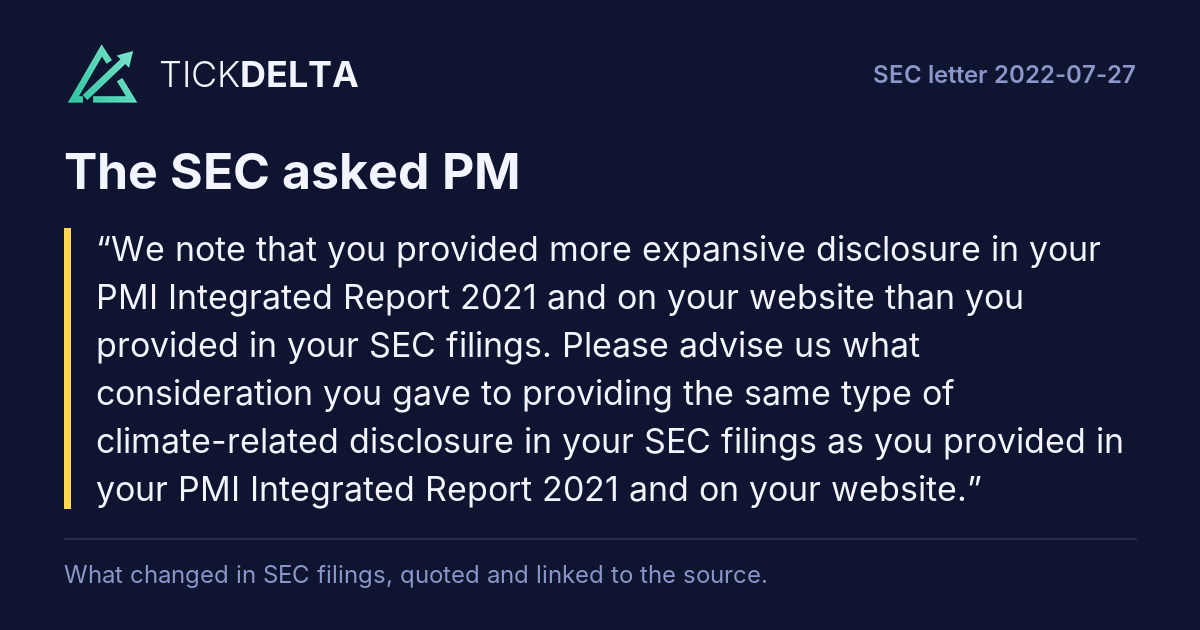
SEC asked (1)
We note that you provided more expansive disclosure in your PMI Integrated Report 2021 and on your website than you provided in your SEC filings. Please advise us what consideration you gave to providing the same type of climate-related disclosure in your SEC filings as you provided in your PMI Integrated Report 2021 and on your website.
PM answered
We respectfully advise the Staff that PMI regularly considers climate-related matters and trends, including those addressed in the Company’s 2021 Integrated Report (the “Report”) and in other materials available on our website, for inclusion in our SEC filings. We determine what to disclose in our SEC filings in accordance with applicable SEC rules and regulations. We also consider the SEC's Guidance Regarding Disclosure Related to Climate Change, Interpretive Release No.
Rest of the answer

33-9106 (February 8, 2010) (the “SEC Guidance”) and assess the quantitative and qualitative materiality of the information under consideration.

While the Report and our website contain more expansive climate-related disclosures than what was disclosed in our SEC filings, they were intended to communicate an array of matters to a broad set of stakeholders, and our sustainability materiality assessment conducted in connection with the Report and our website is distinct from our materiality assessment conducted in connection with our SEC filings. As we noted on page 45 of our 2022 Proxy Statement, as well as in the Report, the disclosures provided in the Report reflect concepts of materiality defined in the sustainability standards we utilized when preparing the Report and related materials, which is distinct from the concept of materiality under the U.S. securities laws and/or disclosures required by the SEC. Specifically, the Report was informed by principles, standards, and guidance from sources such as the Global Reporting Initiative, the Sustainability Accounting Standards Board, the Task Force on Climate-related Financial

Disclosures (“TCFD”), the United Nations (“UN”) Global Compact, the UN Sustainability Development Goals, and the Integrated Reporting Framework. We provide expansive information in our Report and on our website as part of our commitment to furthering public discourse on sustainability, but inclusion of information in the Report or on our website is not intended to reflect a determination that such disclosures are material to the Company under the U.S. securities laws.

Our sustainability team is an integral part of our SEC disclosure process, and our legal, regulatory and other compliance teams are integral parts of our voluntary sustainability reporting process. When we prepared our Form 10-K, we considered whether to voluntarily include additional climate-related information. Some of the considerations we took into account as part of this process are further described below in response to Comments 2 through 9. We also assessed the qualitative importance of climate-related information discussed in the Report and considered whether there were any topics or trends noted in the Report that require material capital expenditures or operating expenses or cause a significant operational challenge or risk to the Company’s business or results of operations. Following such considerations, we determined that the information provided appropriately balanced our desire to provide the public with information regarding our climate change-related initiatives with the requirements of the U.S. securities laws.

As an example, while we prioritize reducing emissions and switching to renewable energy, one component of our climate strategy is compensation for unavoidable carbon emissions related to our direct operations by investing in offsetting and insetting projects. In the Report we highlighted our creation in 2021 of a Portfolio of Climate Investments (“PCI”) dedicated to managing this aspect of our strategy in a way that is cost-effective, transparent, consistent, and of high quality. In 2021, as we disclosed in the Report, the PCI directed over $4 million to carbon credits related to projects in Brazil, Laos, Malawi, Mozambique, and Uganda, with a focus on forest protection, reforestation, and the enhancement of quality of life through activities such as the provision of clean water access. While the PCI is a component of our decarbonization strategy, we determined that the level of investment is not material to our consolidated financial results as it represents only approximately 0.02% of our consolidated cost of sales and marketing, administration and research costs (our “Total Costs”) for fiscal 2021.

PMI understands the threat that climate change poses to society and that climate-related issues are of interest and concern to a range of our stakeholders, including, but not limited to, our consumers, employees, regulators, supply chain partners, civil society, and shareholders. In recognition of these concerns, we voluntarily set greenhouse gas (“GHG”) emission reduction targets as well as goals to achieve carbon neutrality in our direct operations (scope 1 and 2) and net zero emissions in our value chain (scope 1, 2, and 3) using a methodology consistent with the World Resource Institute and World Business Council for Sustainable Development Greenhouse Gas Protocol’s Corporate Accounting and Reporting Standard – Revised Edition (“GHG Protocol”). Moreover, our GHG absolute reduction and net zero targets have been validated by the Science Based Targets initiative. As a result, we have begun providing additional information to our stakeholders regarding our climate-related initiatives, such as information about our carbon footprint, our strategies to achieve our announced targets, and our progress toward achieving them. Information that is of interest and concern to some of our stakeholders, however, is distinguishable from information that is material to an investor’s understanding of our business, financial condition, and results of operations or otherwise is required to be disclosed in our SEC filings.

We continue to believe that the more expansive disclosure included in the Report and on our website noted by the Staff does not require disclosure in PMI’s SEC reports pursuant to the SEC’s rules, regulations and interpretive guidance. Consistent with our obligations under the U.S. securities laws, we will continue to assess climate-change related matters as part of the disclosure process for our SEC filings and will provide additional information as may be required. We also appreciate the interest many of our stakeholders have in information about climate change, and we expect to continue providing information about the actions we are taking to tackle climate change as well as other environmental, social, and governance topics on a voluntary basis through various other public disclosures, including our website and the Report.

Read in the reply ↗
In its next report

First report after the company's reply of 2022-09-02: 10-Q filed 2022-10-27 ↗, against the 10-Q filed 2022-04-28 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Risk Factors, page 6
SEC asked (2)
It appears that you have identified transitioning to a “low-carbon economy” as a transition risk related to climate change. Tell us how you considered providing expanded disclosure regarding your low-carbon transition plan and the potential effects on your business, financial condition, and results of operations.
Rest of the question

In addition, describe the material effects of other transition risks related to climate change you have considered, such as policy and regulatory changes that could impose operational and compliance burdens, market trends that may alter business opportunities, credit risks, or technological changes.

PM answered
As part of our standard procedures for preparing our Form 10-K and Quarterly Reports on Form 10-Q, we take steps to identify and consider risks that may affect our business, financial condition, and results of operations. This process leverages our enterprise risk management practices and personnel from across our organization to identify risks, assess the materiality of such risks to our business and confirm the accuracy and completeness of our disclosures in light of their materiality and the applicable disclosure requirements and guidance, including the SEC Guidance.

PMI’s enterprise risk
Rest of the answer

management practices utilize an interconnected three-step assessment process to identify, assess, and manage and/or mitigate risks that can have a substantive financial or strategic impact on our operations. We define substantive strategic or financial impacts as those identified and prioritized by management based on four risk dimensions: the impact a risk could have on the organization if it occurs, the likelihood a risk will occur, the velocity with which a risk will affect the organization if it occurs, and the interconnectivity of a risk with other risks. To coordinate our risk assessments and practices, PMI has established a Corporate Risk Governance Committee (“CRGC”) made up of senior executive officers, including the Chief Financial Officer, Senior Vice President and General Counsel, Chief Digital & Information Officer, Vice President & PMI Controller, Global Head of Risk & Controls, Chief Information Security Officer, Vice President and Chief Ethics & Compliance Officer, and Vice President, Corporate Audit among others. In addition, the Chief Executive Officer and Vice President, Associate General Counsel & Corporate Secretary are informed of the risk management observations and insights shared with the CRGC. Ownership of each of the prioritized risks is assigned to a member of senior management, and oversight of the management of each risk is assigned to a particular Committee of our Board of Directors or to the full Board.

In conjunction with our integrated risk management process, we periodically conduct a climate change risks and opportunities assessment to fully understand PMI’s impact across our entire value chain. This work seeks to align with international expectations such as those of the Paris Climate Agreement to mitigate and adapt to climate impacts, as well as the recommendations of the TCFD. Using this framework to assess our climate change risks, we have mapped different categories of climate-related risks that could be relevant for our business. Considering that PMI is subject to international, national, and local environmental and climate-related laws and regulations in the countries where we operate, many of which have become more stringent in recent years, regulations and their impact on our operations are considered in PMI’s climate-related risk assessment process. We also identify midand long-term transition risks for PMI’s business. For instance, PMI is subject to risks related to market changes, such as shifts in supply and demand for certain commodities, products, and services. These include risks of increasing costs of sourcing (including materials such as water and fuel) and increasing costs for suppliers. Climate-related reputational risk is also included in PMI’s risk assessment. Finally, we also consider acute and chronic physical risks, including the risk that extreme weather events related to climate change will impact our operations, buildings, and suppliers.

Our assessments have not determined that the transition to a “low-carbon economy” presents a material risk to PMI. We have voluntarily set ambitious goals and targets for decarbonizing our direct operations and our value chain that we communicated in our Low-Carbon Transition Plan (“LCTP”), published in October 2021, because we believe that transparency drives action, accountability, and change. The LCTP is directed to those stakeholders who have interest in understanding our carbon footprint and related efforts to transition to a low carbon economy. It provides a transparent and detailed view of how we plan to achieve our climate ambitions, how we define success, and how we will measure and report on progress. Nevertheless, our LCTP is not material to our business, financial condition, or results of operations. As described in further detail in our responses to Comments 5 and 8, the costs associated with our LCTP have not been material and are not expected to become material. Therefore, in light of our determination that the costs related to our LCTP are not material, we did not believe that additional disclosure of our LCTP in SEC filings was warranted. We will continue to monitor these costs and will update disclosures accordingly in future filings if such activity has a material impact on our business, financial condition or results of operations.

Based on our assessments, we have determined that the risk that climate change could influence weather patterns in ways that negatively impact the quality or cost of the tobacco or other agricultural products used to manufacture our products may be material to our business and profitability and therefore we have included discussion of this risk in the Risk Factors section of our Form 10-K under the caption “Government mandated prices, production control programs, shifts in crops driven by economic conditions and the impact of climate change may increase the cost or reduce the quality of the tobacco and other agricultural products used to manufacture our products.”

At this time, we have determined that other risks related to climate change, including transition risks, are not among our material risks. We will, however, continue to evaluate and assess these and other risks to our business in connection with future filings.

Read in the reply ↗
In its next report

First report after the company's reply of 2022-09-02: 10-Q filed 2022-10-27 ↗, against the 10-Q filed 2022-04-28 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Risk Factors, page 6
SEC asked (3)
Disclose any material litigation risks related to climate change and explain the potential impact to the company.
PM answered
As part of the risk assessment processes described in the response to Comment 2, PMI evaluates risks in light of their materiality and the SEC’s disclosure requirements. In our Form 10-K, we disclosed all material litigation risks that we believed existed as of December 31, 2021. As part of this process, PMI considered the category of material risks that requires disclosure in accordance with the SEC’s disclosure rules and guidance and concluded that as of the date of the report, there were no material risks related to climate change litigation.

As part of this process, PMI took into account
Rest of the answer

that it had not been involved in any material litigation or other material legal proceedings related to climate change, nor was it aware of any material pending or threatened litigation or other legal proceedings related to climate change applicable to us that required disclosure. In considering disclosure of the risk of climate change-related litigation, we considered the likelihood of climate change-related litigation that could be brought in the future, and whether any such litigation could reasonably be expected to have a material effect on us.

We will continue to identify, assess, and manage risks that may have a material financial or strategic impact on our operations through the corporate risk management practices described in the response to Comment 2 and to evaluate and consider providing disclosures regarding material litigation risks related to climate change as circumstances evolve.

Read in the reply ↗
In its next report

First report after the company's reply of 2022-09-02: 10-Q filed 2022-10-27 ↗, against the 10-Q filed 2022-04-28 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Management's Discussion and Analysis of Financial Condition and Results of Operations, page
SEC asked (4)
There have been significant developments in federal and state legislation and regulation and international accords regarding climate change that you have not discussed in your filing. Please revise your disclosure to identify material pending or existing climate change-related legislation, regulations, and international accords and describe any material effect on your business, financial condition, and results of
Rest of the question

operations.

PM answered
As discussed in our Form 10-K, we operate globally in a heavily regulated industry and are subject to numerous laws and regulations in the jurisdictions in which we operate. In the ordinary course of our business, we monitor and comply with the laws and regulations of local, state, national, and international bodies and jurisdictions, and we monitor proposed changes and additions to laws and regulations that are expected to impact our operations.
Rest of the answer

Like other types of regulation that may impact our business, we consider, and will continue to consider, international, national, and local environmental and climate-related laws and regulations in the countries where we operate as such laws and regulations develop. As described in more detail in our response to Comment 2, consideration of environmental and climate-related laws and regulations is an integral aspect of PMI’s climate-related risk assessment process. Effective and proposed laws, regulations, and international accords we actively monitor for this purpose include, but are not limited to, the EU Emissions Trading System, the UK 2050 net zero target, the Brazilian Business Commitment to Water Security, the 2015 Paris Climate Agreement, recommendations of the TCFD, France’s Corporate Duty of Vigilance of 2017, UN Sustainable Development Goals (“SDGs”), UN Guiding Principles on Business and Human Rights, Business Ambition for 1.5°C, UNFCC Race to Zero, 2021, the SEC’s proposed rules regarding climate-related disclosures, the Taskforce on Nature-related Financial Disclosures, European Commission proposal for a Corporate Sustainability Reporting Directive, the International Sustainability Standards Board proposed standards, CDP, the GHG Protocol, and carbon tax programs in Europe and Canada.

We consider such laws, regulations, and international accords, both in effect and proposed, as part of our standard procedures for preparing our filings with the SEC. As further described in our response to Comment 8, the effect of climate-related laws and regulations on PMI have not been material to our business, results of operations or financial conditions. In addition, because we voluntarily set aggressive goals and targets for achieving carbon neutrality, as of the date of the period reported in the Form 10-K, we believed that we were prepared to comply with current and proposed climate-related legislation and regulation without material new investments, compliance-related costs or changes in business strategy. Therefore, we respectfully believe that disclosure in our SEC reports of pending or existing climate change-related legislation, regulations, and international accords, as well as any effects on our business, financial condition, and results of operations resulting from such legislation, regulations, and international accords, was not warranted. Notwithstanding the foregoing, PMI acknowledges that future legislation or regulation related to climate change could affect our business, financial condition, and results of operations. For this reason, in future disclosures we will include a list of the significant pending or existing climate change-related legislation, regulations and international accords we actively monitor and we will continue to evaluate and consider providing disclosures regarding related impacts on PMI as circumstances evolve.

Read in the reply ↗
In its next report

First report after the company's reply of 2022-09-02: 10-Q filed 2022-10-27 ↗, against the 10-Q filed 2022-04-28 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Management's Discussion and Analysis of Financial Condition and Results of Operations, page
SEC asked (5)
Disclosure on page 5 of your Form 10-K states that your environmental expenditures have not been and are not expected be material. Please tell us about and quantify capital expenditures for climate-related projects for the periods covered by your Form 10-K and amounts you expect to incur in future periods.
PM answered
In the fiscal years ended December 31, 2019, 2020 and 2021, PMI’s total annual capital expenditures were $0.9 billion, $0.6 billion, and $0.7 billion, respectively. PMI’s capital expenditures for climate-related projects, which we define as capital expenditures made with the direct or indirect purpose of reducing carbon emissions, primarily consisted of expenditures on energy saving initiatives and environmental expenditures in our manufacturing processes.
Rest of the answer

During the three fiscal years ended December 31, 2021, our climate-related capital expenditures ranged from approximately 1% to 2.7% of total annual capital expenditures, which we considered to be immaterial. Under PMI’s current plans, climate change-related capital expenditures for the fiscal year ending December 31, 2022, are expected to be approximately 2% of total capital expenditures. We will continue to monitor our climate-change related expenditures and will update disclosures accordingly in future filings if such activity has a material impact on our business, financial condition or results of operations.

Read in the reply ↗
In its next report

First report after the company's reply of 2022-09-02: 10-Q filed 2022-10-27 ↗, against the 10-Q filed 2022-04-28 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Management's Discussion and Analysis of Financial Condition and Results of Operations, page
SEC asked (6)
To the extent material, discuss the indirect consequences of climate-related regulation or business trends, such as the following: • decreased demand for goods or services that produce significant greenhouse gas emissions or are related to carbon-based energy sources; • increased demand for goods that result in lower emissions than competing products; • increased competition to develop innovative new products that
Rest of the question

result in lower emissions; • increased demand for generation and transmission of energy from alternative energy sources; and • any anticipated reputational risks resulting from operations or products that produce material greenhouse gas emissions.

PM answered
We respectfully advise the Staff that, while we considered numerous actual and potential trends and scenarios in connection with our risk and disclosure assessments, some of which may relate to climate change, we do not believe that we have experienced any known indirect consequences of climate-related regulation or business trends that have been material to PMI for the periods reported in the Form 10-K.

For example, during 2020 and 2021, PMI carried out eleven large-scale surveys with approximately 15,500 of our consumers addressing the sustainability of our products.
Rest of the answer

Results indicated that environmental considerations were highly appreciated, with consumers responding positively to a number of environmentally conscious initiatives, including device repair, refurbishment, reuse, and recycling; post-consumer waste management programs; and packaging reduction. While some of these initiatives are related directly or indirectly to climate-change, based on our extensive sales experience we believe that the aspects of our products most important in increasing or decreasing consumer demand include product quality, taste, brand loyalty, brand recognition, product innovation, and retail price. Consistent with these observations and results, as of the period reported in the Form 10-K, we had not seen a material decrease in demand for goods or services that produce significant greenhouse gas emissions or are related to carbon-based energy sources. We had also not seen materially increased demand for goods that result in lower emissions than competing products.

Product innovation is a central component of our business strategy. As stated in the Letter from the Board of Directors included in our 2022 Proxy Statement, our purpose as a company is “to deliver a smoke-free future by focusing [PMI’s] resources on developing, scientifically substantiating, and responsibly commercializing smoke-free products that are less harmful than smoking, with the aim of completely replacing cigarettes as soon as possible.” Further, smoke-free products constitute a growing but very competitive market that is experiencing significant innovation. However, competitive innovation of these products has focused on product quality and features, taste, and retail price, points of competition that are similar to traditional combustible tobacco products. We have not seen increased innovation to develop products with lower greenhouse gas emissions that is material to our business or strategy and have not identified competitive innovation for lower emission products as a significant risk through the risk assessment processes described in the response to Comment 2. Nevertheless, we are working to reduce the carbon footprint of new versions of our smoke-free products compared with previous ones through improved manufacturing processes, extending the usable life of our electronic devices, and decreasing the total carbon footprint through smart materials selection and sustainable design practices. For PMI, sustainability is more than just a means to minimize negative externalities and mitigate risks while maximizing operational efficiency and resource optimization. We see it as an opportunity for innovation, growth, and purpose-led, impact-driven, long-term value creation.

As of the period reported in the Form 10-K, we had not observed material increased consumer demand for generation and transmission of energy from alternative sources compared to traditional sources as it relates to our products or services. Nevertheless, consistent with our corporate values, in 2021, we voluntarily accelerated our decarbonization ambitions and now aim to achieve carbon neutrality in our operations (scope 1+2) by 2025 and net zero emissions across our entire value chain (scope 1+2+3) by 2040. To deliver on those ambitious goals, we prioritize reducing absolute carbon emissions. This requires PMI to optimize efficiency and reduce consumption, while simultaneously minimizing the use of fossil fuels and promoting the switch to renewable energy (by procuring green electricity and installing technology to self-produce or store green energy).

Our decarbonization targets and commitments, as described above, are ambitious, designed to exceed or meet the expectations of stakeholders, and are presented in the Report and other forums to ensure that our stakeholders are aware of our strategy. While our enterprise risk assessment process has identified climate-related reputational risk as relevant, we do not believe that reputational risk related to greenhouse gas emissions of our products is material to PMI.

For all of the reasons discussed above, PMI does not believe that it has experienced any indirect consequences of climate-related regulation to date that have been material to PMI. To the extent determinable, we will continue to monitor climate-change related consequences and will update disclosures accordingly in future filings if material to our business, financial condition or results of operations.

Read in the reply ↗
In its next report

First report after the company's reply of 2022-09-02: 10-Q filed 2022-10-27 ↗, against the 10-Q filed 2022-04-28 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Management's Discussion and Analysis of Financial Condition and Results of Operations, page
SEC asked (7)
If material, discuss the physical effects of climate change on your operations and results. This disclosure may include the following: • severity of weather, such as floods, hurricanes, sea levels, arability of farmland, extreme fires, and water availability and quality; • quantification of material weather-related damages to your property or operations; • potential for indirect weather-related impacts that have
Rest of the question

affected or may affect your customers; and • any weather-related impacts on the cost or availability of insurance. Your response should include quantitative information for each of the periods for which financial statements are presented in your most recent Form 10-K and explain whether changes are expected in future periods.

PM answered
should include quantitative information for each of the periods for which financial statements are presented in your most recent Form 10-K and explain whether changes are expected in future periods.

Response

We respectfully advise the Staff that for the periods reported in the Form 10-K, the impact from the physical effects of climate change has not been material to PMI’s business, financial condition or results of operations.

Our physical properties include office, research & development, and factory facilities, and we rely on agricultural products sourced from suppliers.
Rest of the answer

These properties and suppliers are distributed around the world, though we do not have significant properties located in areas that we believe could reasonably be impacted by sea level change. As of the period reported in the Form 10-K, increasing severity and frequency of weather-related events had not materially impacted our operations. During the three fiscal years ended December 31, 2021, weather-related losses were below 0.01% of our Total Costs each year. Additionally, while we monitor fire events, we have had no material damage or interruption of operations attributable to extreme fires. For the reasons discussed above, we have not considered the physical effects of climate change related to weather events, sea levels, or extreme fires to be material to our operations or results.

Concerning the arability of farmland and water availability and quality, climate change is expected to affect rainfall patterns worldwide, placing pressure on water supplies and potentially restricting water availability for agriculture and certain industry sectors. Given the global reach of PMI’s value chain, water scarcity which may be, in part, climate change-driven, could, if not managed properly, negatively impact our business objectives in the midto long-term, though the impact has not been significant to date. Consequently, properly managing land and water resources is a priority for PMI as we seek to increase the resilience of our production systems and minimize operational risks. We conduct a global water risk assessment annually in tobacco-growing regions to identify potential hotspots for physical water risks that require adaptation measures. In the past two years, we strengthened our water stewardship strategy, developing guidance for applying a landscape approach to water optimization projects, protecting natural resources and recharge areas, and improving the efficiency of irrigation systems to integrate better farm water management. Although our active assessment and management of water risks is a key reason why this physical effect of climate change has not had a material effect on our operations and results, the costs associated with our active management of water scarcity have not been material.

We do not believe there have been any material weather-related impacts on the cost or availability of our insurance as of the period reported in the Form 10-K. The cost of PMI’s insurance premiums is directly tied to the cost of insurance in the overall insurance market, and we do not believe that any of PMI’s insurance costs include weather-related premiums specific to our operations. We note that, generally, insurance premiums may rise in a given year due to many reasons, including as a result of weather-related impacts (such as a cyclone, hurricane, flood, drought or other weather-related event), which are not specific to PMI. Additionally, our aggregate property and marine insurance premiums have not increased significantly during the years covered by the Form 10-K and are below 0.1% of our Total Costs, an expense level we consider immaterial. Furthermore, PMI is unaware of any weather-related impact on its availability of insurance. For those reasons, we do not believe any weather-related impacts on the cost or availability of insurance have caused or are reasonably likely to cause a material impact on our financial condition or results of operations.

Notwithstanding the foregoing, we recognize that risks related to the physical effects of climate change exist and note that we include disclosure in our Risk Factors, on page 10 of our Form 10-K, about climate change risks related to weather patterns and their potential to negatively impact the quality or cost of the tobacco or other agricultural products used to manufacture our products, which may be material to our business and profitability. In this risk factor, we provide information about risks arising from weather pattern variations and its influence on crop quality, including but not limited to weather pattern variations that are a direct result of climate change. However, as of the period reported in the Form 10-K, these conditions had not had a material impact on PMI, and for the other reasons noted above, we do not believe that additional disclosure regarding the physical effects of climate change on our operations and results is warranted. Should circumstances change, we will evaluate updating our disclosures accordingly.

Read in the reply ↗
In its next report

First report after the company's reply of 2022-09-02: 10-Q filed 2022-10-27 ↗, against the 10-Q filed 2022-04-28 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Management's Discussion and Analysis of Financial Condition and Results of Operations, page
SEC asked (8)
On page 5 of your Form 10-K you state that the effect of compliance with government regulations, including environmental regulations, has not been material. Tell us about and quantify any compliance costs related to climate change for the last three fiscal years and explain whether increased amounts are expected to be incurred in future periods.
PM answered
PMI’s primary costs for compliance with environmental regulations, which are described in additional detail in the following paragraph, are related to and consistent with normal course maintenance, regulatory permitting, and facility management for manufacturing facilities. Over each of the three fiscal years included in our Form 10-K, we did not incur any material costs related to environmental remediation fees or projects related to climate change, nor did we face any significant fines or fees for non-compliance with environmental regulations or standards related to climate change.
Rest of the answer

To date, we do not expect a material increase in such amounts in the current fiscal year.

Where we have assets or facilities, PMI has taken measures to comply with the applicable environmental permitting and compliance requirements of the jurisdictions, both local and federal. These environmental compliance costs can be summarized as expenses for internal environmental engineering services, consultant services, and government permitting or licensing fees. The annual total global environmental compliance cost for our facilities manufacturing cigarettes and heated tobacco units was less than 0.05% of our Total Costs in 2021. To date, we do not expect for such costs to materially increase in the current or in future periods.

Where appropriate, PMI uses capital expenditures and undertakes initiatives to offset any potential rise in costs due to regulatory fees or taxes related to climate change, while also offsetting increased energy costs, increasing our environmental sustainability, and enhancing alignment with our policies and public statements. Examples include the installation of new air filtration systems in our Brazilian plant, ongoing efforts to reduce installed electrical capacity below 20Mw within key entities, and many more efforts to achieve PMI’s carbon neutral goals. Voluntarily, PMI utilizes its Global Certification ISO 14001 to ensure compliance with environmental and climate change regulations at an annual cost of $250,000 and has partnered with the Alliance for Water Stewardship Program and International Water Resource Association, at a cost of approximately $2 million per year, to continue mitigation of climate change impact and expenditures. Overall, due to offsets and efficiency gains, PMI does not currently expect materially increased compliance costs due to climate change.

We will continue to monitor our climate-change compliance costs and will update disclosures accordingly in future filings if such costs have a material impact on our business, financial condition or results of operations.

Read in the reply ↗
In its next report

First report after the company's reply of 2022-09-02: 10-Q filed 2022-10-27 ↗, against the 10-Q filed 2022-04-28 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Management's Discussion and Analysis of Financial Condition and Results of Operations, page
SEC asked (9)
If material, provide disclosure about your purchase or sale of carbon credits or offsets and any material effects on your business, financial condition, and results of operations. Include quantitative information regarding any such transactions during the last three years and subsequent periods as part of your response.
PM answered
We respectfully advise the Staff that, as noted in the Report, we have a three-pronged approach to decarbonization: 1) reduce consumption and optimize efficiency, 2) minimize the use of fossil fuels and promote the switch to renewable energy, and 3) for any remaining and unavoidable emissions, compensate via offsetting or insetting with instruments, investments, and activities (such as the purchase of carbon credits). The use of carbon credits is not the core approach in our decarbonization journey.
Rest of the answer

As discussed in our response to Comment 1, with the creation of a PCI in 2021, we invested approximately $4 million in carbon credits. Moreover, the PCI focused on securing high-quality offsets to support PMI’s decarbonization journey and provided the required carbon offsets for the five manufacturing sites that achieved carbon neutrality certification during the calendar year. For 2019 and 2020 combined, the purchase of carbon credits was less than $1 million. In 2022, we expect to invest a comparable amount to 2021.

During the three years ended December 31, 2021, we did not sell any carbon credits or offsets. In 2022, we do not expect to sell any carbon credits for offsetting purposes.

PMI has determined its purchase of carbon credits and offsets as of the period reported in the Form 10-K was not material and had not had a material effect on our business, financial condition, or results of operations. Accordingly, we do not believe that disclosure related to our purchase and sale of carbon credits and offsets is warranted in our SEC filings, although we will continue to evaluate the materiality of such activity in future periods.

Read in the reply ↗
In its next report

First report after the company's reply of 2022-09-02: 10-Q filed 2022-10-27 ↗, against the 10-Q filed 2022-04-28 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Risk Factors, page 6
SEC asked (1)
We note your response to prior comment two and reissue in part. Describe the material effects of other transition risks related to climate change you have considered, such as policy and regulatory changes that could impose operational and compliance burdens, market trends that may alter business opportunities, credit risks, or technological changes.
Rest of the question

Your response should describe how you considered providing disclosure regarding the effects of the transition risks most relevant to your business, such as the risks of increasing costs of sourcing and increasing costs for suppliers due to market changes.

PM answered
As discussed in our response to comment number two in the Initial Comment Letter, when preparing the Form 10-K, we leveraged our enterprise risk management practices and personnel from across our organization to (i) evaluate potential material risks, including transition risks related to climate change, (ii) assess whether such risks are material to our business, and (iii) confirm the accuracy and completeness of our disclosures in light of the applicable disclosure requirements and guidance.
Rest of the answer

In our October 2021 Low-Carbon Transition Plan ("LCTP"), we indicated that the primary climate change related transition risks identified through these processes were (i) the impact of evolving international, national, and local environmental and climate-related laws and regulations in the countries where we operate and (ii) risks related to market changes, such as shifts in supply and demand for certain commodities, products, and services that could lead to increased costs of sourcing and increased costs for suppliers. These and the other climate change related transition risks mentioned by the Staff, and how we considered providing disclosure about these transition risks, are discussed individually below.

First, we face the possible adoption and implementation of carbon-pricing mechanisms in countries where we operate, such as the European Union emissions trading scheme, which could lead to an increase in our operating costs in the future if not sufficiently mitigated. We manage and mitigate this risk both through our overall corporate decarbonization targets, which aim to achieve carbon neutrality in our operations (scope 1+2) by 2025 and net zero emissions across our entire value chain (scope 1+2+3) by 2040, and by incorporating carbon emissions impact analysis in the planning for our internal projects, which allows us to better understand the potential impact of external carbon pricing on profitability and prioritize investments that accelerate emissions reduction. Based on this risk management approach, and the enterprise risk management practices outlined above and in the Initial Comment Letter, we concluded that this particular climate change related transition risk did not give rise to a material risk to our business or results that required inclusion in the Risk Factors section of our Form 10-K.

Second, with respect to transitional market changes, our business relies on an agricultural supply chain and therefore faces the risk that climate change could influence weather patterns in ways that negatively impact the quality or cost of the agricultural products used to manufacture our products. For instance, climate change is expected to affect rainfall patterns worldwide, placing pressure on water supplies and potentially restricting water availability for agriculture, while also leading to flooding and other excess rainfall events that adversely impact the quantity or quality of crops in impacted areas. Given the global reach of our value chain, properly managing land and water resources and utilizing a geographically diversified sourcing strategy for agricultural products are priorities for PMI as we seek to increase the resilience of our production systems and minimize operational risks. We conduct a global water risk assessment annually in tobacco-growing regions to identify potential hotspots for physical water risks that require adaptation measures. Our water stewardship strategy includes guidance for applying a landscape approach to water optimization projects, protecting natural resources and recharge areas, and improving the efficiency of irrigation systems to integrate better farm water management. These business practices are intended to mitigate the risk of changing weather patterns on our agricultural supply chain. Although we did not experience impacts material to our business or profitability related to this risk during the periods reported in the Form 10-K, as discussed in the Initial Response Letter when addressing comment number two, we determined that this risk could, in the future, impact us in ways that may be material to our business and profitability and therefore we included discussion of this risk in the Risk Factors section of our Form 10-K under the caption “Government mandated prices, production control programs, shifts in crops driven by economic conditions and the impact of climate change may increase the cost or reduce the quality of the tobacco and other agricultural products used to manufacture our products.”

In addition to the climate change related transition risks discussed above, we analyzed other climate change related transition risks and determined that these risks did not constitute primary climate related risks to our business. For example, the use of climate risk metrics by credit rating agencies and general trend of investors decarbonizing their investment portfolio create investment market and credit risks. As discussed above and in the Initial Response Letter, we have voluntarily set ambitious goals and targets for decarbonizing our direct operations and our value chain. We believe that this strategy will significantly mitigate these risks to PMI and, for the periods reported in the Form 10-K, these risks did not materially impact our business or profitability.

Additionally, we face midand long-term transition risks related to technology, specifically technology improvements, as existing equipment becomes non-compliant with evolving energy regulations, too expensive to run due to the higher fuel costs, or inconsistent with our decarbonization goals and targets. In order to achieve our decarbonization strategy, we will need to invest in new technology, implement technological advancements, and avoid investing in technologies whose emissions characteristics are inconsistent with our goals and targets. These investments are an important component of our decarbonization strategy, as explained in more detail in the LCTP. However, as discussed in our response to comment number five in the Initial Comment Letter, our capital expenditures for climate-related projects have been, and are expected to continue to be, immaterial to PMI. We believe we can mitigate this risk through our planned investments without materially adversely impacting our business or profitability. For these reasons, we have not identified technology-related risks as a primary current or future climate change related transition risk.

Relying on the risk identification processes described above and in the Initial Response Letter, in preparing the Form 10-K we determined that, except as described above, transition risks related to climate change, are not among our material risks. We will, however, continue to evaluate and assess these and other risks to our business in connection with future filings.

Read in the reply ↗
In its next report

First report after the company's reply of 2022-10-05: 10-Q filed 2022-10-27 ↗, against the 10-Q filed 2022-04-28 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Management's Discussion and Analysis of Financial Condition and Results of Operations, page
SEC asked (2)
We note your response to prior comment seven and reissue in part. Please discuss the potential for indirect weather-related impacts that have affected or may affect your customers.
PM answered
We respectfully inform the Staff that while we are unable to predict with specificity the nature or the extent of the potential for indirect weather-related impacts that have or may affect our customers, due to the diversified nature of our business, the potential for weather-related impacts on our customers has not been material to PMI’s business, financial condition or results of operations, and, because we anticipate maintaining a diversified customer base, we do not currently expect this to change in future periods.
Rest of the answer

PMI is a global organization with customers in approximately 180 markets distributed across our six geographic business segments: the European Union Region, the Eastern Europe Region, the Middle East & Africa Region, the South & Southeast Asia Region, the East Asia & Australia Region, and the Americas Region. Our customers are a mix of distributors, wholesalers, retailers, and individuals depending on the market and product sold. As disclosed in the Form 10-K, while we have significant sales to individual distributors in some markets where the loss of the distributor could cause temporary disruption in that market, we believe that none of our geographical business segments is dependent upon a single customer or a few customers, the loss of which would have a material adverse effect on our consolidated results of operations. For the periods reported in the Form 10-K, weather-related impacts on our customers were not material to PMI’s business, financial condition or results of operations, and because of the diversity, both geographically and by channel, of our customer base, we do not believe that they will become material in future periods.

Read in the reply ↗
In its next report

First report after the company's reply of 2022-10-05: 10-Q filed 2022-10-27 ↗, against the 10-Q filed 2022-04-28 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Management's Discussion and Analysis of Financial Condition and Results of Operations, page
SEC asked (3)
We note your response to prior comment eight and the amount incurred for fiscal year 2021. Please quantify any compliance costs related to climate change for fiscal years 2019 and 2020.
PM answered
As discussed in more detail in our response to comment number eight in the Initial Comment Letter, PMI’s primary costs for compliance with environmental regulations are related to our manufacturing facilities. For each of fiscal 2019 and fiscal 2020, the annual total global environmental compliance cost for our facilities manufacturing cigarettes and heated tobacco units was less than 0.05% of our consolidated cost of sales and marketing, administration, and research costs.

We will continue to monitor our climate-change compliance costs and will update disclosures accordingly in future
Rest of the answer

filings if such costs have a material impact on our business, financial condition or results of operations.

Read in the reply ↗
In its next report

First report after the company's reply of 2022-10-05: 10-Q filed 2022-10-27 ↗, against the 10-Q filed 2022-04-28 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Also in this review: closing letter, 2022-10-12

Form 10-K for the Year Ended December 31, 2017

2018-09-10 to 2018-10-01 · 2 questions · 1 letter from the SEC, 1 from the company
Review closed 2018-10-01
Results discussion (MD&A)InventoryRevenue
Management’s Discussion and Analysis of Financial Condition and Results of Operations · Consolidated Operating Results, page 22
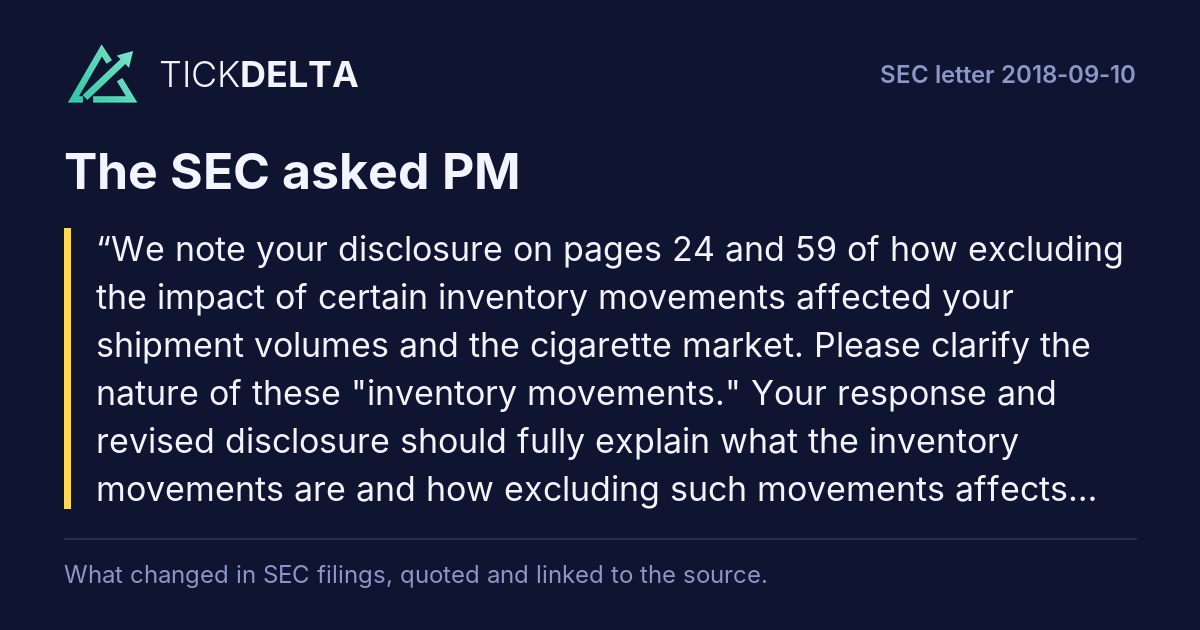
SEC asked (1)
We note your disclosure on pages 24 and 59 of how excluding the impact of certain inventory movements affected your shipment volumes and the cigarette market. Please clarify the nature of these "inventory movements." Your response and revised disclosure should fully explain what the inventory movements are and how excluding such movements affects your reported results.
PM answered
The distribution of cigarettes and other nicotine-containing products, as well as IQOS heating devices and related accessories, to PMI’s customers is tailored to the characteristics of each market and includes PMI’s own direct sales to retailers, distribution through independent or dedicated distributors, distribution through national or regional wholesalers, and e-commerce.

The distribution of such products in any given market may require the creation and maintenance of certain levels of inventory tailored to particular market-specific factors, such as changes to the manufacturing supply
Rest of the answer

chain, shipment methods, consumer demand, timing of excise tax increases or other influences that may affect the timing of sales to customers. In the case where distribution is through direct sales to retailers, PMI builds its own inventories to respond to these market-specific factors. In the case where distribution is indirect, such as through a third-party distributor (e.g., in Japan), it is the third party that builds inventories to respond to these market-specific factors.

Regardless of the distribution model, direct or indirect, PMI recognized revenue prior to January 1, 2018 when title and risk of loss passed to customers, typically either upon shipment or delivery of goods. Under ASC 606, which PMI adopted on January 1, 2018, PMI recognizes revenue once control is transferred to the customer, typically either upon shipment or delivery of goods. Consequently, increases and decreases in PMI's own inventories do not affect PMI's reported net revenues and shipment volumes. Conversely, increases and decreases of inventories by the distributor do affect PMI’s reported net revenues and shipment volumes.

In its Management’s Discussion and Analysis of Financial Condition and Results of Operations ("MD&A"), PMI discloses its own shipment volumes on a reported basis. PMI also discloses certain estimated total industry/market volumes on a reported basis (using latest available data from a number of internal and external sources). With respect to PMI’s own shipment volumes, in some circumstances, distributor inventory movements, in response to the market-specific factors described above, can significantly distort reported shipment trends and, as a result, fail to provide the most meaningful disclosure of PMI’s business performance to investors. Similarly, with respect to estimated total industry/market volumes, in some circumstances, estimated trade inventory movements in various trade channels in response to the market-specific factors described above can significantly distort reported estimated total industry/market volumes and, as a result, fail to provide the most meaningful disclosure of the estimated total industry/market performance to investors. Consequently, in such circumstances, management believes additional disclosure that excludes the impact of either favorable or unfavorable distributor inventory movements on PMI’s reported shipment volumes, and/or the impact of either favorable or unfavorable estimated trade inventory movements on the total industry/market, provides investors a better understanding of underlying volume performance and trends.

While changes to the inventory levels of PMI’s distributors result in changes to PMI’s shipment volumes and therefore PMI’s reported net revenues, the additional disclosure of the exclusion of the impact of their inventory movements on PMI’s shipment volume has no impact on revenue recognition described above.

To further explain the nature of these inventory movements and how their exclusion affects PMI’s reported results, PMI will add the following clarifying language to the MD&A in its future 10-Q and 10-K filings:

"From time to time, PMI’s shipment volumes are subject to the impact of distributor inventory movements, and estimated total industry/market volumes are subject to the impact of inventory movements in various trade channels that include estimated trade inventory movements of PMI’s competitors arising from market-specific factors that significantly distort reported volume disclosures. Such factors may include changes to the manufacturing supply chain, shipment methods, consumer demand, timing of excise tax increases or other influences that may affect the timing of sales to customers. In such instances, in addition to reviewing PMI shipment volumes and certain estimated total industry/market volumes on a reported basis, management reviews these measures on an adjusted basis that excludes the impact of distributor and/or estimated trade inventory movements. Management also believes that disclosing PMI shipment volumes and estimated total industry/market volumes in such circumstances on a basis that excludes the impact of distributor and/or estimated trade inventory movements improves the comparability of performance and trends for these measures over different reporting periods."

Read in the reply ↗
In its next report

First report after the company's reply of 2018-09-21: 10-Q filed 2018-10-25 ↗, against the 10-Q filed 2018-07-26 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Note 18. New Accounting Standards, page 36
SEC asked (2)
We note from your disclosure in Note 7, that net revenues refers to your operating revenues from the sale of products, including shipping and handling charges billed to customers, net of sales and promotion incentives, and excise taxes.
Rest of the question

In light of the fact that the incentives appear to represent variable consideration, please tell us and revise to disclose the nature of all variable consideration and how you estimate the variable consideration, including whether this estimate is typically constrained. See ASC 606-1050-12(c) and 606-10-50-20. In this regard, we also note from your earnings calls that you may have loyalty programs associated with the IQOS products, which also may be sold with discounts. Please note that these programs should be considered in your variable consideration analysis.

PM answered
When PMI recognizes revenue, the net amount reflects the transaction price billed to customers, less sales and promotion incentives, where applicable. Such sales and promotion incentives relate principally to volume-based customer discounts, rebates or prompt payment discounts. As it relates to IQOS products, PMI does, in certain markets, offer discounts to its customers, primarily related to IQOS devices.
Rest of the answer

While PMI has begun to operate loyalty programs in certain markets, the related accounting impacts are currently inconsequential (less than $1 million annualized).

In situations where PMI sells directly to consumers and the discount is applied at the point of sale, the consideration is not variable as it does not change after the sale transaction. In markets where PMI sells through a third-party distributor or the level of pricing or consumer discounts is dependent on future events (for example the volume of sales to a customer in a particular period) this is variable consideration, as the amount to which PMI is entitled in exchange for transferring the goods is variable. In determining the transaction price, PMI estimates any relevant variable consideration based on the most likely amount PMI expects to be entitled to under the terms of the contract taking into consideration historical experience of discount or rebate redemption where relevant. Based on the evaluation of the factors set out in ASC 606-10-32-12, in the context of the PMI discount and incentive programs, PMI concluded that the potential reversal of any significant variable consideration is not probable and therefore such variable consideration is not constrained.

PMI will continue to monitor such sales and promotional incentives, as well as any loyalty programs, which may vary in significance with the continued growth in its reduced-risk product portfolio. In recognition of the expected increased significance, PMI will update, in future filings, the disclosures of revenue recognition as follows (by adding the underlined text):

"PMI recognizes revenue primarily through the manufacture and sale of cigarettes and other nicotine-containing products, including reduced-risk products. The majority of PMI revenues are generated by sales through direct and indirect distribution networks with short-term payment conditions and where control is typically transferred to the customer either upon shipment or delivery of goods. PMI evaluates the transfer of control through evidence of the customer’s receipt and acceptance, transfer of title, PMI’s right to payment for those products and the customer’s ability to direct the use of those products upon receipt. Typically, PMI’s performance obligations are satisfied and revenue is recognized either upon shipment or delivery of goods. In certain instances, PMI facilitates shipping and handling activities after control has transferred to the customer. PMI has elected to record all shipping and handling activities as costs to fulfill a contract. The shipping and handling costs that have not been incurred at the time revenue is recognized are accrued. The transaction price is typically based on the amount billed to the customer and includes estimated variable consideration where applicable. Such variable consideration is typically not constrained and is estimated based on the most likely amount that PMI expects to be entitled to under the terms of the contracts with customers, historical experience of discount or rebate redemption, where relevant, and the terms of any underlying discount or rebate programs, which may change from time to time as the business and product categories evolve."

Read in the reply ↗
In its next report

First report after the company's reply of 2018-09-21: 10-Q filed 2018-10-25 ↗, against the 10-Q filed 2018-07-26 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Also in this review: closing letter, 2018-10-01

From the SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), 11 letters filed since 2018-09-11. Questions and answers are matched by their numbers; topics come from words in each question. The reports are compared word for word (same form, before the first SEC letter against the first report after the company's reply). No AI.

Work on PM in a spreadsheet: Excel workbook (a sheet per section, ten years by column, charts, links to the filings) · CSV. For a Google Sheet that stays up to date, paste =IMPORTDATA("https://tickdelta.com/company/PM/export.csv") into a cell.