Form 10-K for the Fiscal Year Ended September 30, 2022
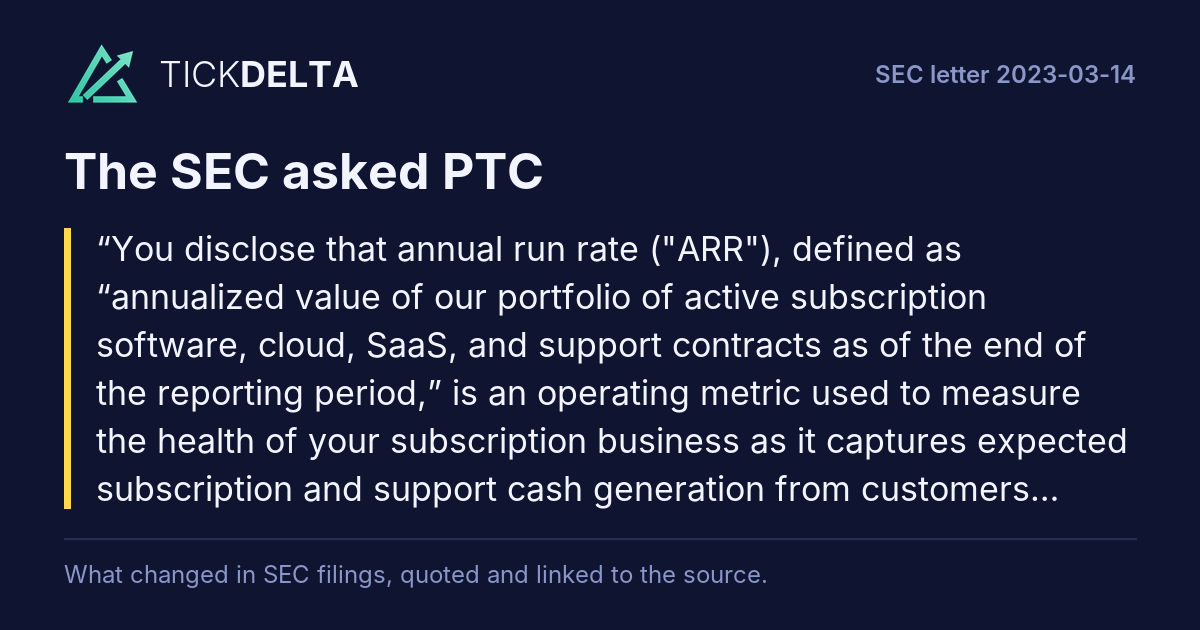
You disclose that annual run rate ("ARR"), defined as “annualized value of our portfolio of active subscription software, cloud, SaaS, and support contracts as of the end of the reporting period,” is an operating metric used to measure the health of your subscription business as it captures expected subscription and support cash generation from customers.Rest of the question
We also note that subscription revenue includes on-premises term-based license revenue, for which revenue is recognized at a point-in-time. Please address the following: • Clarify how this measure is calculated. Specifically address how the up-front revenue received from term licenses is factored into your ARR calculation and provide examples to help explain such calculations. Clarify whether you annualize revenue recognized or invoiced amounts. • Tell us the length of a typical subscription contract term and explain how you consider contract renewals in your ARR calculations. • Explain how multi-year contracts are factored into your calculations and tell us the amount of revenue recognized from multi-year contracts for each period presented and the typical terms of such arrangements. • Explain how any software exchanges, additions to current customer subscriptions, and new customer subscriptions acquired are factored into your calculation. Please provide an example to explain these calculations. • Clarify whether ARR reflects any actual or anticipated reductions of revenue due to contract non-renewals or cancellations, and discuss any limitations present as a result. • Revise to describe how ARR differs from GAAP revenue and specifically address the timing of revenue recognition related to the license performance obligation. Additionally, please consider disclosing any of the above information to the extent material. • Provide us with proposed disclosure responsive to the concerns noted above. Refer to SEC Release 33-10751.
No reply letter found.
First report after the SEC's letter of 2023-03-14: 10-Q filed 2023-05-03 ↗, against the 10-Q filed 2023-02-09 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: closing letter, 2023-03-31