Form 8-K
2020-05-04 to 2020-05-18 · 1 question
· 1 letter from the SEC, 1 from the company
Non-GAAP measures
Exhibit 99, page 1
SEC asked
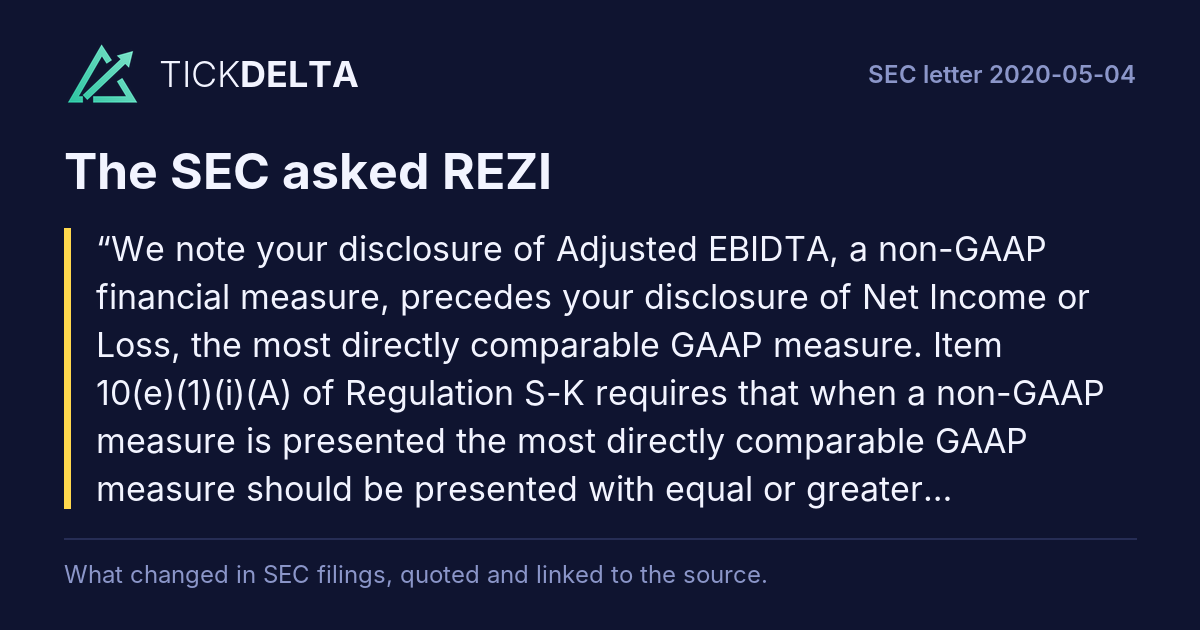
We note your disclosure of Adjusted EBIDTA, a non-GAAP financial measure, precedes your disclosure of Net Income or Loss, the most directly comparable GAAP measure. Item 10(e)(1)(i)(A) of Regulation S-K requires that when a non-GAAP measure is presented the most directly comparable GAAP measure should be presented with equal or greater prominence.Rest of the question
Please revise your presentation in future earnings releases accordingly.
REZI answered
The Company respectfully acknowledges the Staff’s comment. In response to the Staff’s comment, the Company made the adjustments to the earnings release furnished on May 6, 2020 to present comparable GAAP measures with equal or greater prominence to non-GAAP measures in accordance with the C&DI and will continue to do so in future filings.Read in the reply
* * *
We hope that this letter responds adequately to the Staff’s concerns.Rest of the answer
Please feel free to contact Robert Ryder, Interim Chief Financial Officer, at (737) 471-0271, AnnMarie Geddes, Interim Chief Accounting Officer, at (512) 726-3518, or Jeannine Lane, EVP, General Counsel and Corporate Secretary, at (516) 508-3762 should you have any further questions regarding this matter.