Added10-Q Nov 3, 2026 vs 10-K Feb 24, 2026
Integrating Grande Lakes Orlando may be more difficult, costly or time consuming than expected.
Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Feb 21, 2025. A box jumps to the paragraph as filed, below.
7 paragraphs in Risk Factors of the 10-K filed Feb 24, 2026 with nothing like them in the 10-K filed Feb 21, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.
reduce our profits and ultimately impair our ability to make distributions to our stockholders. In addition, the efforts and ability of our senior executives are important elements of maintaining our competitive position and driving future growth, and the loss of the services of one or more of our senior executives could result in challenges executing our business strategies or other adverse effects on our business.
Our financial and operating results may suffer if we are unsuccessful in integrating JW Marriott Desert Ridge with our existing assets, and integrating JW Marriott Desert Ridge may be more difficult, costly or time-consuming than expected.
If we are unable to successfully integrate JW Marriott Desert Ridge with our other assets in an efficient and effective manner, the anticipated benefits of the JW Marriott Desert Ridge transaction may not be fully realized, or at all, or may take longer to realize than expected and may not meet estimated growth projections or expectations. Further, we may not achieve the projected efficiencies and synergies once we have fully integrated JW Marriott Desert Ridge into our operations, which may lead to additional costs not anticipated at the time of the JW Marriott Desert Ridge transaction. An inability to realize the full extent of the anticipated benefits of the JW Marriott Desert Ridge transaction or any delays encountered in the integration process could have an adverse effect on our results of operations, cash flows and financial position.
The ongoing integration of JW Marriott Desert Ridge with our other assets requires the dedication of significant management resources, which may distract management’s attention from day-to-day operations. Phoenix, Arizona is a new market for us, and our relative unfamiliarity with the market may result in our having to devote additional time and expense to gain familiarity with the market and effectively manage this asset. Many of these factors will be outside of our control and any one of them could result in delays, increased costs, decreases in revenue and diversion of management’s time and energy from ongoing business concerns, which could materially affect our results of operations, cash flows and financial position.
managers to operate our hotel properties and certain attractions, we have limited control over defending lawsuits of this type or other claims.
taxed at individual rates to perceive investments in REITs to be relatively less attractive than investments in the stocks of non-REIT corporations that pay dividends, which could adversely affect the value of our stock.
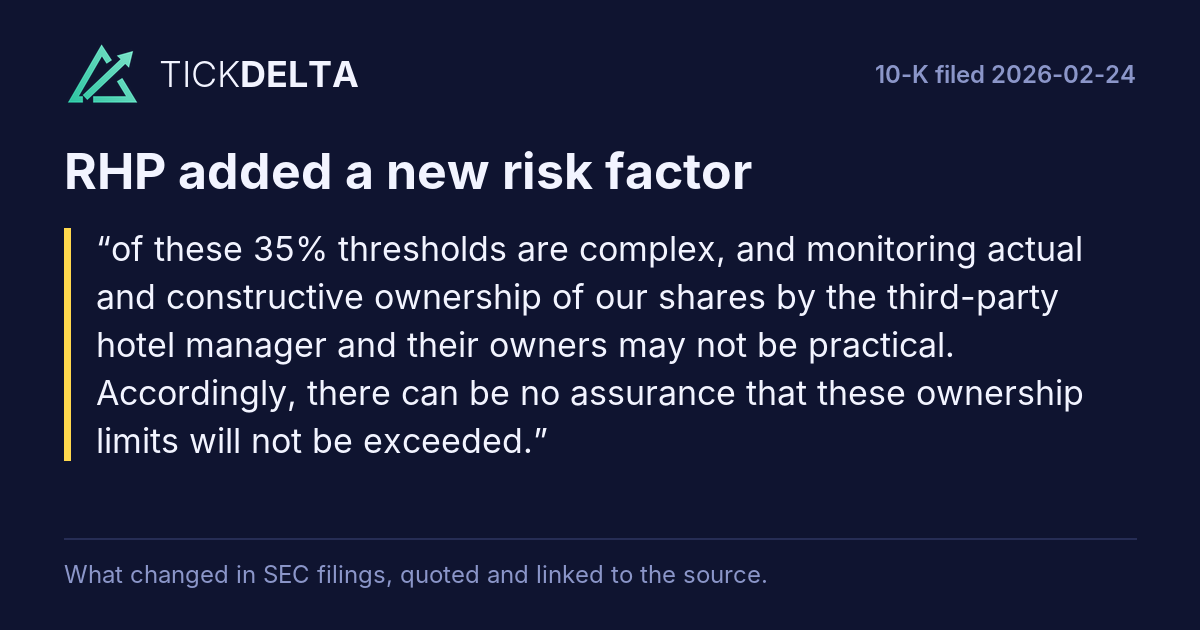
of these 35% thresholds are complex, and monitoring actual and constructive ownership of our shares by the third-party hotel manager and their owners may not be practical. Accordingly, there can be no assurance that these ownership limits will not be exceeded.
New in the latest 10-Q
20 paragraphs in the 10-Q filed Nov 3, 2026 with nothing like them in the 10-Q filed Aug 7, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.
The Company’s revenues disaggregated by major source are as follows (in thousands):
Read in the 10-Q
The Company has the intent and ability to hold these bonds to maturity. The Company’s quarterly assessment of credit losses considers the estimate of projected tax revenues that will service the bonds over their remaining terms. These tax revenue projections are updated each quarter to reflect updated industry projections as to future anticipated operations of the hotel. As a result of previously reduced tax revenue projections over the life of the bonds as well as certain cumulative priority payments due to others, the Series B bond is fully reserved. The Series A bond is of higher priority than other tranches which fall between the Company’s two issuances.
Read in the 10-Q
In October 2026, the insurance carriers representing the defendants reached a confidential settlement with one of the injured guests and the guest’s family. This settlement will resolve all claims of this plaintiff. The applicable settlement payment will be funded directly by the insurance companies under the policies maintained by Marriott and the contractors. The Company has no payment obligation and will not recognize a charge related to this settlement.
Read in the 10-Q
In August 2026, the Company completed an underwritten public offering of approximately 5.9 million shares of its common stock, par value $0.01 per share, at a price to the public of $117.00 per share. Net proceeds to the Company, after deducting underwriter discounts and commissions and other expenses paid by the Company, were approximately $659.2 million. The Company used these proceeds to fund a portion of the purchase price to acquire Grande Lakes Orlando as discussed in Note 3.
Read in the 10-Q
Purchased Grande Lakes Orlando in September 2026 – Note 3, “Grande Lakes Orlando Transaction”
Read in the 10-Q
(1) Diluted outstanding shares for the 2026 periods include the issuance of approximately 5.9 million shares of our common stock in August 2026.
Read in the 10-Q
Period Ended September 30, ───────────────────────────────────────────────────────────────── 2026 Revenues: Rooms $ 9,480 Food and beverage 9,279 Other hotel revenue 3,232 Total revenue 21,991 Operating expenses: Rooms 3,136 Food and beverage 6,957 Other hotel expenses 7,881 Management fees, net 814 Depreciation and amortization 5,054 Total operating expenses 23,842 Operating loss $ (1,851) Performance metrics: Occupancy 63.1% ADR $ 314.64 RevPAR $ 198.49 Total RevPAR $ 460.45
Read in the 10-Q
Loss on sale of assets during the three and nine months ended September 30, 2025 includes the sale of miscellaneous assets.
Read in the 10-Q
Impairment charges during the three and nine months ended September 30, 2026 include charges associated with our September 2026 decision to cease operations of the General Jackson Showboat by December 31, 2026.
Read in the 10-Q
Other gains and (losses), net for each of the three and nine months ended September 30, 2026 and 2025 includes the receipt of $3.4 million and $3.3 million, respectively, from a fund associated with the Gaylord National bonds to reimburse us for certain marketing and maintenance expenses.
Read in the 10-Q
pavilion and event lawn; the rooms renovation at Gaylord Texan; and ongoing maintenance capital expenditures for each of our existing properties.
Read in the 10-Q
On September 1, 2026, we acquired Grande Lakes Orlando. We are currently in the process of assessing Grande Lakes Orlando’s internal control over financial reporting and integrating the entity’s internal control over financial reporting with our existing internal control over financial reporting. As permitted by SEC regulations, we intend to exclude Grande Lakes Orlando from our assessment of internal control over financial reporting as of December 31, 2026.
Read in the 10-Q
Our financial and operating results may suffer if we are unsuccessful in integrating Grande Lakes Orlando with our existing assets.
Read in the 10-Q
If we are unable to successfully integrate Grande Lakes Orlando with our other assets in an efficient and effective manner, the anticipated benefits of the Grande Lakes Orlando transaction may not be fully realized, or at all, or may take longer to realize than expected and may not meet estimated growth projections or expectations. Further, we may not achieve the projected efficiencies and synergies once we have fully integrated Grande Lakes Orlando into our operations, which may lead to additional costs not anticipated at the time of the Grande Lakes Orlando transaction. An inability to realize the full extent of the anticipated benefits of the Grande Lakes Orlando transaction or any delays encountered in the integration process could have an adverse effect on our results of operations, cash flows and financial position.
Read in the 10-Q
Integrating Grande Lakes Orlando may be more difficult, costly or time consuming than expected.
Read in the 10-Q
The integration of Grande Lakes Orlando with our other assets will require the dedication of significant management resources, which may distract management’s attention from day-to-day business operations. The Ritz-Carlton brand is a new brand for us, and our relative unfamiliarity with the brand may result in our having to devote additional time and expense to gain familiarity with the brand and effectively manage this asset. Many of these factors will be outside of our control and any one of them could result in delays, increased costs, decreases in revenues and diversion of management’s time and energy from ongoing business concerns, which could materially affect our results of operations, cash flows and financial position.
Read in the 10-Q
Each of our Gaylord Hotels properties, JW Marriott Hill Country, JW Marriott Desert Ridge and Grande Lakes Orlando operate under a brand owned by Marriott; therefore, we are subject to risks associated with concentrating our hotel portfolio in brands owned by Marriott.
Read in the 10-Q
Each of our hotel properties are managed by Marriott under Marriott-owned brands. As a result, our success is dependent in part on the continued success of Marriott and, in particular, the Gaylord Hotels, JW Marriott and Ritz-Carlton brands. Consequently, if market recognition or the positive perception of Marriott is reduced or compromised, the goodwill associated with the Gaylord Hotels properties, JW Marriott Hill Country, JW Marriott Desert Ridge and Grande Lakes
Read in the 10-Q
Orlando may be adversely affected, which could negatively impact our results of operations, cash flows, financial position and our ability to service debt and make distributions to our stockholders.
Read in the 10-Q
Certain schedules and similar attachments have been omitted in reliance on Item 601(a)(5) of Regulation S-K. The Company will provide, on a supplemental basis, a copy of any omitted schedule or attachment to the Securities and Exchange Commission or its staff upon request.
Read in the 10-Q
Item 1A of the 10-Q filed Nov 3, 2026 against Item 1A of the 10-K filed Feb 24, 2026.
A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed.
Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed,
Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal
(cut words struck through, new words highlighted).
Text on the page, not a score; each links to the filing at sec.gov.
What the 10-Q itself says about its risk factors:Except as otherwise described herein, there have been no material changes from the risk factors disclosed in Part I, Item 1A, “Risk Factors,” of our Annual Report on Form 10-K for the year ended December 31, 2025.
Read in the 10-Q
Two-word phrases in Risk Factors of the 10-K filed Feb 24, 2026 that are in none of the 1 earlier 10-Ks stored, back to Feb 21, 2025
Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.
4 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.
Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.
10-K change: what was reworded or cut, section by section.
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/RHP/export.csv") into a cell.