Paragraph 192 · 49% changed
Every version of it
Screener
/
SEC EDGAR
/CIK 0001802768
/10-K filed Feb 11, 2026, compared with Feb 12, 2025
/Numbers from the XBRL of the 10-Ks
Nasdaq
Health care · Pharmaceuticals
Royalty Pharma plc RPRX
The 10-K against last year's
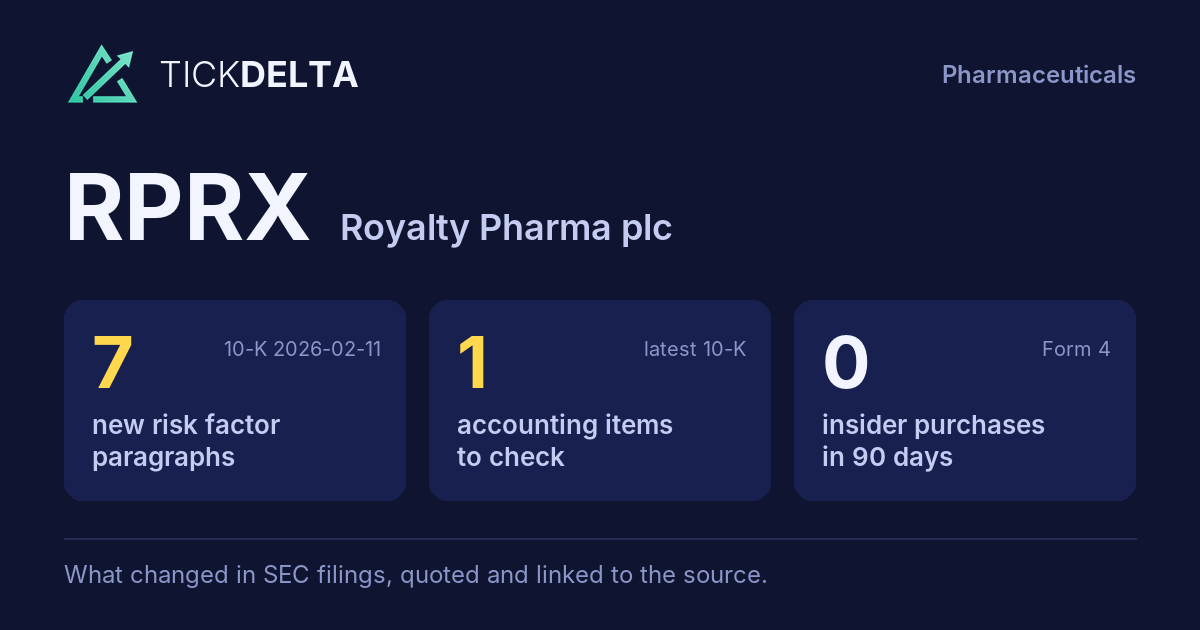
329 changes: 59 added, 84 removed, 176 reworded, 10 quiet changes
10-K Feb 11, 2026 vs Feb 12, 2025
Risk Factors
12.4%
of the text changed · 20,391 words now · 7 new paragraphs, 33 gone
MD&A
33.1%
of the text changed · 14,055 words now · 52 new paragraphs, 51 gone
Legal Proceedings
48.0%
of the text changed · 689 words now
Accounting Policies
16.6%
of the text changed · 6,206 words now
10-K 0001802768-26-000003 (Feb 11, 2026) vs 10-K 0001802768-25-000010 (Feb 12, 2025)
Every paragraph, and how much of it changed
One bar per paragraph, in the order of the 10-K. Height and colour show the share of its words not in the closest paragraph a year earlier; the tallest bars are new paragraphs.
Risk Factors
216 paragraphs · 7 new · 76 reworded · 33 gone · 10-K Feb 11, 2026 against Feb 12, 2025
New paragraph
Reworded (5% of its words or more)
Same or nearly
Paragraph 136 · 46% changed
Every version of it
Paragraph 69 · 42% changed
Every version of it
Unsuccessful attempts to acquire new royalties could result in significant costs costs, divert management attention and negatively impact subsequent attempts adversely affect our ability to locate and acquire pursue other assets. investment opportunities.
Paragraph 4 · 41% changed
Every version of it
•uncertainties related to the acquisition of acquiring interests in development-stage biopharmaceutical product candidates and our strategy to add interests in development-stage product candidates to our product portfolio; candidates;
Paragraph 8 · 40% changed
Every version of it
Paragraph 212 · 40% changed
Every version of it
We may be subject to become involved in a wide variety of legal claims and proceedings. Regardless of their merit, these claims can proceedings, which could require significant time and expense to investigate investigate, defend and defend. resolve and could divert management’s attention from our business. Since litigation is inherently uncertain, there is no guarantee that we will be successful in defending ourselves against such claims or proceedings, proceedings or in obtaining favorable outcomes in claims that our we may bring. Our assessment of the materiality likelihood and estimated magnitude of these matters, any potential gains or losses associated with legal claims or proceedings, including any reserves taken established in connection therewith, will is subject to significant judgment and may prove to be consistent with the ultimate outcome of such matters. The resolution of, or increase in the reserves taken in connection with, one or more of these matters could adversely affect our business, financial condition or results of operations. incorrect.
Paragraph 149 · 37% changed
Every version of it
These and other factors may cause significant fluctuations in the market price or trading volume of and demand for our Class A ordinary shares to fluctuate significantly, shares, which may limit or prevent our shareholders from reselling shareholders’ ability to sell their Class A ordinary shares at prices they consider satisfactory or above the purchase price. at all.
Paragraph 103 · 37% changed
Every version of it
We are a holding company with no operations and rely on cash generated by our subsidiaries to provide us with the funds necessary to meet our financial obligations and to pay dividends. obligations.
Paragraph 192 · 49% changed
Every version of it
10-K Feb 12, 2025We expect to be classified as a PFIC for U.S. federal income tax purposes, which could subject U.S. holders of our Class A ordinary shares to adverse U.S. federal income tax consequences. Distributions that we pay to individual and other non-corporate U.S. holders will not be eligible for taxation at reduced rates, which could potentially adversely affect the value of our Class A ordinary shares.
10-K Feb 11, 2026
Since 2020, we have been classified as a PFIC for U.S. federal income tax purposes, and we expect to be classified as a PFIC for U.S. federal income tax purposes for the year ended December 31, 2025. Whether we are classified as a PFIC is generally only relevant for taxable U.S. holders of our Class A ordinary shares. Our PFIC classification is unrelated to our corporate tax status.
Paragraph 136 · 46% changed
Every version of it
10-K Feb 12, 2025If we internalize the Manager, we would become exposed to new and additional costs and risks. For example, while we would no longer bear the cost of the management fee paid to the Manager, our direct overhead would increase because we would be responsible for 100% of the compensation and benefits of our officers and other employees and our other operating expenses. While Mr. Legorreta has agreed to provide the Board with a reasonable opportunity to review and comment on future awards or modifications of Equity Performance Awards, Equity Performance Awards on existing and future investments would continue on the current terms. Our general and administrative expenses after the Internalization could also be higher than our current expectations.
10-K Feb 11, 2026
We may not realize the anticipated benefits of the Internalization, such as cash savings, enhanced alignment with shareholders, increased investment returns, management continuity, transparency and governance, or greater structure simplification. Since our Internalization on May 16, 2025, we have become exposed to new costs and risks. Although we no longer pay a management fee, our direct overhead has increased because we are responsible for all compensation and benefits of our employees and other operating expenses. As an employer, we are subject to the liabilities and risks commonly faced by employers, such as workers’ compensation claims, labor disputes and other employee-related grievances, and the costs of employee benefit plans. Our overhead may increase further in the future as a result of our becoming internally managed as the responsibility for overhead relating to management of our business has become our own responsibility. In addition, while Mr. Legorreta has agreed to provide the board of directors with a reasonable opportunity to review and comment on future awards or modifications of Equity Performance Awards, Equity Performance Awards on existing and future investments will continue on their current terms and are ultimately controlled by Mr. Legorreta.
Paragraph 69 · 42% changed
Every version of it
10-K Feb 12, 2025
Unsuccessful attempts to acquire new royalties could result in significant costs and negatively impact subsequent attempts to locate and acquire other assets.
10-K Feb 11, 2026
Unsuccessful attempts to acquire new royalties could result in significant costs, divert management attention and adversely affect our ability to pursue other investment opportunities.
Paragraph 4 · 41% changed
Every version of it
10-K Feb 12, 2025
•uncertainties related to the acquisition of interests in development-stage biopharmaceutical product candidates and our strategy to add interests in development-stage product candidates to our product portfolio;
10-K Feb 11, 2026
•uncertainties related to acquiring interests in development-stage biopharmaceutical product candidates;
Paragraph 8 · 40% changed
Every version of it
10-K Feb 12, 2025The Manager may be the subject of a change of control resulting in a disruption in our operations that could adversely affect our business, financial condition or results of operations.
10-K Feb 11, 2026
•legal claims and proceedings that could adversely affect our business, financial condition or results of operations.
Paragraph 212 · 40% changed
Every version of it
10-K Feb 12, 2025
We may be subject to a wide variety of legal claims and proceedings. Regardless of their merit, these claims can require significant time and expense to investigate and defend. Since litigation is inherently uncertain, there is no guarantee that we will be successful in defending ourselves against such claims or proceedings, or that our assessment of the materiality of these matters, including any reserves taken in connection therewith, will be consistent with the ultimate outcome of such matters. The resolution of, or increase in the reserves taken in connection with, one or more of these matters could adversely affect our business, financial condition or results of operations.
10-K Feb 11, 2026
We may become involved in a wide variety of legal claims and proceedings, which could require significant time and expense to investigate, defend and resolve and could divert management’s attention from our business. Since litigation is inherently uncertain, there is no guarantee that we will be successful in defending against such claims or proceedings or in obtaining favorable outcomes in claims that we may bring. Our assessment of the likelihood and estimated magnitude of any potential gains or losses associated with legal claims or proceedings, including any reserves established in connection therewith, is subject to significant judgment and may prove to be incorrect.
Paragraph 149 · 37% changed
Every version of it
10-K Feb 12, 2025
These and other factors may cause the market price of and demand for our Class A ordinary shares to fluctuate significantly, which may limit or prevent our shareholders from reselling their Class A ordinary shares at or above the purchase price.
10-K Feb 11, 2026
These and other factors may cause significant fluctuations in the market price or trading volume of our Class A ordinary shares, which may limit our shareholders’ ability to sell their Class A ordinary shares at prices they consider satisfactory or at all.
Paragraph 103 · 37% changed
Every version of it
10-K Feb 12, 2025
We are a holding company with no operations and rely on our subsidiaries to provide us with the funds necessary to meet our financial obligations and to pay dividends.
10-K Feb 11, 2026
We are a holding company and rely on cash generated by our subsidiaries to meet our financial obligations.
MD&A
201 paragraphs · 52 new · 88 reworded · 51 gone · 10-K Feb 11, 2026 against Feb 12, 2025
New paragraph
Reworded (5% of its words or more)
Same or nearly
Paragraph 105 · 50% changed
•Trodelvy. In January 2024, November 2025, Gilead announced that the Phase 3 EVOKE-01 ASCENT-07 study evaluating investigating Trodelvy compared to docetaxel as a first-line (“1L”) treatment for HR+/HER2-negative metastatic breast cancer patients did not meet its the primary endpoint of overall progression-free survival. Overall survival in patients with previously treated metastatic non-small cell lung cancer. is a key secondary endpoint and was not mature at the time of the primary analysis.
Paragraph 113 · 50% changed
•Myqorzo. In September 2024, Johnson and Johnson December 2025, Cytokinetics announced the FDA approval of Tremfya Myqorzo (formerly known as aficamten) for the treatment of adults with moderately to severely active ulcerative colitis. symptomatic obstructive hypertophic cardiomyopathy.
Paragraph 115 · 50% changed
•Skytrofa. In September 2024, Johnson and Johnson July 2025, Ascendis announced the FDA approval of Tremfya approved Skytrofa for the once-weekly treatment of adults with moderately to severely active ulcerative colitis. growth hormone deficiency.
Paragraph 89 · 49% changed
Paragraph 151 · 49% changed
Paragraph 51 · 48% changed
Income from financial royalty assets decreased increased by $48.3 $111.7 million, or 2.2%, 5.2%, in 2024 2025 as compared to 2023, 2024, primarily due to a significant milestone receipt in 2023 related to Pfizer’s Zavzpret. The March 2023 FDA approval the addition of Zavzpret resulted in our receipt of a $475.0 million milestone payment, for Voranigo which we recognized interest income acquired in August of $153.6 million, as reflected within other products in the above table and which was non-recurring. The decrease was 2024 upon FDA approval, partially offset by the increase in lower income from Evrysdi attributable due to the incremental royalties that we acquired a decline in the fourth quarter of 2023 and second quarter of 2024. sell-side equity research analysts’ consensus sales forecasts.
Paragraph 137 · 48% changed
•In September 2024, August 2025, we acquired a synthetic royalty on Yorvipath interest in Amgen’s Imdelltra from Ascendis Pharma A/S BeOne for an upfront payment of $150 $885 million. Yorvipath BeOne had the option to sell to us additional royalties on Imdelltra for up to $65 million within twelve months from the acquisition date and in November 2025, BeOne elected to sell to us $26 million of those additional royalties. Imdelltra is approved for the treatment of hypoparathyroidism in adults. extensive-stage small cell lung cancer.
Paragraph 135 · 47% changed
•In September 2024, November 2025, we acquired a synthetic royalty on Yorvipath interest in Alnylam’s Amvuttra from Ascendis Pharma A/S Blackstone for $310 million. Amvuttra is an upfront payment of $150 million. Yorvipath is approved ribonucleic acid interference (“RNAi”) therapeutic for the treatment of hypoparathyroidism in adults. transthyretin (“TTR”) amyloidosis with cardiomyopathy and for hereditary TTR amyloidosis with polyneuropathy.
Paragraph 105 · 50% changed
10-K Feb 12, 2025
•Trodelvy. In January 2024, Gilead announced that the Phase 3 EVOKE-01 study evaluating Trodelvy compared to docetaxel did not meet its primary endpoint of overall survival in patients with previously treated metastatic non-small cell lung cancer.
10-K Feb 11, 2026
•Trodelvy. In November 2025, Gilead announced the Phase 3 ASCENT-07 study investigating Trodelvy as a first-line (“1L”) treatment for HR+/HER2-negative metastatic breast cancer patients did not meet the primary endpoint of progression-free survival. Overall survival is a key secondary endpoint and was not mature at the time of the primary analysis.
Paragraph 113 · 50% changed
10-K Feb 12, 2025
In September 2024, Johnson and Johnson announced the FDA approval of Tremfya for the treatment of adults with moderately to severely active ulcerative colitis.
10-K Feb 11, 2026
•Myqorzo. In December 2025, Cytokinetics announced the FDA approval of Myqorzo (formerly known as aficamten) for the treatment of adults with symptomatic obstructive hypertophic cardiomyopathy.
Paragraph 115 · 50% changed
10-K Feb 12, 2025
In September 2024, Johnson and Johnson announced the FDA approval of Tremfya for the treatment of adults with moderately to severely active ulcerative colitis.
10-K Feb 11, 2026
•Skytrofa. In July 2025, Ascendis announced the FDA approved Skytrofa for the once-weekly treatment of adults with growth hormone deficiency.
Paragraph 89 · 49% changed
10-K Feb 12, 2025•Erleada – Royalty Receipts from Erleada, which is marketed by Johnson & Johnson for the treatment of patients with prostate cancer, increased by $11.6 million in 2024 as compared to 2023, primarily driven by continued share gains and market growth in metastatic castration-sensitive prostate cancer. We acquired an incremental royalty on Erleada in the second quarter of 2023 and began receiving the additional royalty in the third quarter of 2023.
10-K Feb 11, 2026
•Imdelltra – Royalty Receipts from Imdelltra, which is marketed by Amgen for the treatment of extensive-stage small cell lung cancer were $9.6 million in 2025, primarily driven by its strong global launch as it establishes a new standard of care in second-line extensive stage small cell lung cancer (“ES-SCLC”). We acquired the Imdelltra royalty in the third quarter of 2025 and began receiving Royalty Receipts in the fourth quarter of 2025.
Paragraph 151 · 49% changed
10-K Feb 12, 2025Our subsidiary, RP Holdings, as borrower, initially entered into the Amended and Restated Credit Agreement (the “Credit Agreement”) on September 15, 2021, which provides for an unsecured revolving credit facility (the “Revolving Credit Facility”). Amendment No. 3 to the Credit Agreement, which was entered into on December 22, 2023, increased the borrowing capacity to $1.8 billion for general corporate purposes with $1.69 billion of the revolving commitments maturing on December 22, 2028 and the remaining $110.0 million of revolving commitments maturing on October 31, 2027. On January 24, 2024, we entered into Amendment No. 4 to the Credit Agreement to make certain technical modifications. As of December 31, 2024, we have a borrowing capacity of $1.8 billion under the Revolving Credit Facility.
10-K Feb 11, 2026
In August 2025, we entered into an uncommitted line of credit agreement with Société Générale (the “Uncommitted Credit Facility”) which provides for an aggregate borrowing capacity of up to $350.0 million for general corporate purposes within a quarter. As of December 31, 2025, there were no outstanding borrowings under the Uncommitted Credit Facility.
Paragraph 51 · 48% changed
10-K Feb 12, 2025
Income from financial royalty assets decreased by $48.3 million, or 2.2%, in 2024 as compared to 2023, primarily due to a significant milestone receipt in 2023 related to Pfizer’s Zavzpret. The March 2023 FDA approval of Zavzpret resulted in our receipt of a $475.0 million milestone payment, for which we recognized interest income of $153.6 million, as reflected within other products in the above table and which was non-recurring. The decrease was partially offset by the increase in income from Evrysdi attributable to the incremental royalties that we acquired in the fourth quarter of 2023 and second quarter of 2024.
10-K Feb 11, 2026
Income from financial royalty assets increased by $111.7 million, or 5.2%, in 2025 as compared to 2024, primarily due to the addition of Voranigo which we acquired in August of 2024 upon FDA approval, partially offset by lower income from Evrysdi due to a decline in sell-side equity research analysts’ consensus sales forecasts.
Paragraph 137 · 48% changed
10-K Feb 12, 2025
•In September 2024, we acquired a synthetic royalty on Yorvipath from Ascendis Pharma A/S for an upfront payment of $150 million. Yorvipath is approved for the treatment of hypoparathyroidism in adults.
10-K Feb 11, 2026
•In August 2025, we acquired a royalty interest in Amgen’s Imdelltra from BeOne for an upfront payment of $885 million. BeOne had the option to sell to us additional royalties on Imdelltra for up to $65 million within twelve months from the acquisition date and in November 2025, BeOne elected to sell to us $26 million of those additional royalties. Imdelltra is approved for the treatment of extensive-stage small cell lung cancer.
Paragraph 135 · 47% changed
10-K Feb 12, 2025
•In September 2024, we acquired a synthetic royalty on Yorvipath from Ascendis Pharma A/S for an upfront payment of $150 million. Yorvipath is approved for the treatment of hypoparathyroidism in adults.
10-K Feb 11, 2026
•In November 2025, we acquired a royalty interest in Alnylam’s Amvuttra from Blackstone for $310 million. Amvuttra is an approved ribonucleic acid interference (“RNAi”) therapeutic for the treatment of transthyretin (“TTR”) amyloidosis with cardiomyopathy and for hereditary TTR amyloidosis with polyneuropathy.
A paragraph is matched with the one last year that shares the most of its words; under half in common makes it new. The paragraphs shown are the 8 reworded the most in each section.
The paragraph that changed most in each section
The redline
Marked against last year's 10-K: cut words struck through, new words highlighted.
Accounting Policies182 words changed in this paragraph; it is 58% similar to last year's version.
•Analyst coverage. Forecasts of expected Expected future cash flows are developed derived from sales projections of for the underlying biopharmaceutical products as published in products, based primarily on sell-side equity research analyst reports. In projecting future cash flows, our consensus forecasts. These forecasts incorporate market research on global economic conditions, industry trends and product life cycles. Our policy is to rely on sell-side research analysts’ consensus sales forecasts to derive annual sales projections for each financial royalty asset over the periods for which we are entitled to royalties or milestones. These forecasts are based on market research that analyzes factors such as growth in global economies, industry trends and product life cycles. We generally utilize statistical curves to When analyst estimates do not extend through the full royalty term, we project future sales for a portion of the royalty duration when sell-side equity research coverage ends or when estimates are not available for the duration of the royalty. The using statistical curves which are modelled from using a combination of historical product trends and available sell-side equity research analyst consensus sales estimates. Based Depending on the level of detail details provided in sell-side equity research analyst models, management can also be required to may apply additional assumptions to the sales forecasts to estimate the quarterly and geographical allocation from allocate annual sales projections and, for franchised products, to estimate the quarterly periods and by geographic regions, determine product mix and pricing mix, mix for franchises, or to exclude from projections sales forecasts for unapproved products. Our contractual Contractual royalty terms, rates, terms and any milestones are then applied to the adjusted sales projections to calculate estimate the expected royalty or milestone payments over the term of the financial royalty asset’s life, forming the basis for our forecast of expected future cash flows used to calculate in calculating and measure measuring interest income.
Source: Item 8, Note 2 – Summary of Significant Accounting Policies, 10-K 0001802768-26-000003 vs Item 8, Note 2 – Summary of Significant Accounting Policies, 10-K 0001802768-25-000010
MD&A182 words changed in this paragraph; it is 58% similar to last year's version.
•Analyst coverage. Forecasts of expected Expected future cash flows are developed derived from sales projections of for the underlying biopharmaceutical products as published in products, based primarily on sell-side equity research analyst reports. In projecting future cash flows, our consensus forecasts. These forecasts incorporate market research on global economic conditions, industry trends and product life cycles. Our policy is to rely on sell-side research analysts’ consensus sales forecasts to derive annual sales projections for each financial royalty asset over the periods for which we are entitled to royalties or milestones. These forecasts are based on market research that analyzes factors such as growth in global economies, industry trends and product life cycles. We generally utilize statistical curves to When analyst estimates do not extend through the full royalty term, we project future sales for a portion of the royalty duration when sell-side equity research coverage ends or when estimates are not available for the duration of the royalty. The using statistical curves which are modelled from using a combination of historical product trends and available sell-side equity research analyst consensus sales estimates. Based Depending on the level of detail details provided in sell-side equity research analyst models, management can also be required to may apply additional assumptions to the sales forecasts to estimate the quarterly and geographical allocation from allocate annual sales projections and, for franchised products, to estimate the quarterly periods and by geographic regions, determine product mix and pricing mix, mix for franchises, or to exclude from projections sales forecasts for unapproved products. Our contractual Contractual royalty terms, rates, terms and any milestones are then applied to the adjusted sales projections to calculate estimate the expected royalty or milestone payments over the term of the financial royalty asset’s life, forming the basis for our forecast of expected future cash flows used to calculate in calculating and measure measuring interest income.
Source: Item 7, 10-K 0001802768-26-000003 vs Item 7, 10-K 0001802768-25-000010
Risk Factors171 words changed in this paragraph; it is 45% similar to last year's version.
Source: Item 1A, 10-K 0001802768-26-000003 vs Item 1A, 10-K 0001802768-25-000010
Legal Proceedings40 words changed in this paragraph; it is 55% similar to last year's version.
We have commitments to advance funds to counterparties through our investment in the Avillion Entities. Entities and R&D arrangements. Please refer to Note 8–Non-Consolidated 10-Non-Consolidated Affiliates and Note 11-Research and Development Funding Expense for details of these arrangements. We also have requirements to make Operating and Personnel Payments (defined below) over the life of the Management Agreement as described in Note 15–Related Party Transactions.
Source: Item 3, via Note 15 – Commitments and Contingencies, 10-K 0001802768-26-000003 vs Item 3, via Note 14 – Commitments and Contingencies, 10-K 0001802768-25-000010
Sentences and paragraphs added, removed or reworded
Every change, by type
Sentences and paragraphs of RPRX's Risk Factors and MD&A, 10-K Feb 11, 2026 against 10-K Feb 12, 2025. Each links to the text at sec.gov.
Quiet changes are sentences kept from last year with one to four words changed, at least one of them a hedge, a modal or a qualifier (may, could, will, not, significant, material…). A year or date rolling forward is not counted.
The full word list
adverse, adversely, all, although, anticipate, anticipates, any, approximately, believe, believes, can, cannot, certain, could, expect, expects, generally, however, if, intend, intends, largely, likely, many, material, materially, may, might, most, must, never, no, not, possible, primarily, probable, should, significant, significantly, some, substantial, substantially, unlikely, will, would
AddedRisk Factors
•our ability to generate increasing royalty receipts and to achieve attractive returns on our investments, including maintaining attractive internal rates of return and consistent returns on invested capital and returns on invested equity;
Read it in 10-K Feb 11, 2026 at sec.gov
AddedRisk Factors
•we may not realize the anticipated benefits of the Internalization and we may be exposed to new risks and costs;
Read it in 10-K Feb 11, 2026 at sec.gov
AddedRisk Factors
We may not realize the anticipated benefits of the Internalization or we may be exposed to new risks and costs.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedRisk Factors
• analyst or media reports or other adverse publicity about us, our industry or related sectors;
Read it in 10-K Feb 11, 2026 at sec.gov
AddedRisk Factors
Whether we are a PFIC is a complex legal and factual question. We regularly review whether we expect to be classified as a PFIC in the current year or are likely to be classified as a PFIC in a future year. We may reach the conclusion in future years that we should not be classified as a PFIC.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedRisk Factors
Beginning in the second quarter of 2025, we did not receive from Vertex the full amount of royalty receipts on Alyftrek net sales to which we believe that we are contractually entitled. Accordingly, we commenced the dispute resolution procedures contemplated by the agreements relating to our royalties on Vertex’s cystic fibrosis products. Any amounts receivable by us, if any, in connection with this dispute will be recognized only upon the resolution of the matter in our favor.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedRisk Factors
The resolution of, or increase in the reserves taken in connection with, one or more of these matters could adversely affect our business, financial condition or results of operations. In addition, adverse publicity or market reaction arising from legal claims or proceedings could harm our reputation, relationships with counterparties or ability to pursue future business opportunities.
Read it in 10-K Feb 11, 2026 at sec.gov
RemovedRisk Factors
Show the other 69
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RewordedRisk Factors
RewordedRisk Factors
It is not clear at this time unclear whether the Treaty may could be implicated in the findings produced as a result of this order, any such review or whether any “protective measures” measures that may be recommended that adopted could impact affect our ability to qualify for the Treaty benefits of the Treaty or reduce or eliminate or otherwise reduce the benefits of the Treaty. those benefits.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedRisk Factors
Since litigation is inherently uncertain, there is no guarantee that we will be successful in defending ourselves against such claims or proceedings, proceedings or in obtaining favorable outcomes in claims that our assessment of the materiality of these matters, including any reserves taken in connection therewith, will be consistent with the ultimate outcome of such matters. we may bring.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedRisk Factors
Biopharmaceutical product sales may be lower than expected due to a number of reasons, including pricing pressures, insufficient demand, product competition, failure of clinical trials, delays or failures in obtaining marketing approval in one or more jurisdictions or for additional product indications, lack of market acceptance, changes in the marketer’s strategic priorities, obsolescence, lack of acceptance coverage or insufficient reimbursement by healthcare programs or insurance plans, loss of patent protection, government regulations or and other factors, and development-stage product candidates may fail to reach the market. factors.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedRisk Factors
As part of the ongoing release implementation of the Pillar Two rules by various jurisdictions, the Finance (No. 2) Act 2023 (the “UK Act”) was enacted on July 11, 2023, and implements United Kingdom has adopted the OECD’s BEPS Pillar Two income inclusion rule, including a multinational top-up tax and a domestic top-up tax to the minimum effective tax rate of 15% for relevant accounting periods beginning on or after December 31, 2023. periods.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedRisk Factors
RewordedRisk Factors
These and other factors may cause significant fluctuations in the market price or trading volume of and demand for our Class A ordinary shares to fluctuate significantly, shares, which may limit or prevent our shareholders from reselling shareholders’ ability to sell their Class A ordinary shares at prices they consider satisfactory or above the purchase price. at all.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedRisk Factors
Under arrangements with Pharmakon, the Manager subleases office space to Pharmakon, and the parties we may provide research, business development, legal, compliance, financial and administrative services to one another. another, and each party reimburses the other to the extent it provides materially more services than it receives.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedRisk Factors
For example, initiatives toward “most favored nation” (MFN) drug pricing in the United States could lead to decreased drug pricing or the drug pricing provisions of the Inflation Reduction Act (“IRA”) requires which require manufacturers of select drugs to engage in a process with the U.S. to establish negotiated Medicare prices.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedRisk Factors
Our subsidiaries are legally distinct from us and may be prohibited subject to contractual, legal, regulatory, financial or restricted from providing loans, paying dividends or otherwise making other restrictions that limit their ability to provide funds available to us under certain conditions. us.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedRisk Factors
RewordedRisk Factors
Quiet changesRisk Factors
We may acquire more royalties on development-stage product candidates that have not yet received marketing approval by any regulatory authority or been commercialized.
Read it in 10-K Feb 11, 2026 at sec.gov
Quiet changesRisk Factors
Uncertainty relating to development-stage product candidates makes it more difficult to develop accurate assumptions for our internal models, which can may result in reduced royalties compared to our estimates.
Read it in 10-K Feb 11, 2026 at sec.gov
Quiet changesRisk Factors
The diversion of our management’s attention and any delay or difficulties encountered in connection with any future acquisitions we may consummate could result in the disruption of our on-going business operations.
Read it in 10-K Feb 11, 2026 at sec.gov
Quiet changesRisk Factors
To service our indebtedness and meet our other ongoing liquidity needs, we will require a significant amount of cash.
Read it in 10-K Feb 11, 2026 at sec.gov
Quiet changesRisk Factors
If we cannot generate the required cash, we may not be able unable to make the required payments under our indebtedness.
Read it in 10-K Feb 11, 2026 at sec.gov
Quiet changesRisk Factors
Absent sufficient cash flow and the ability to refinance, we could also may be forced to sell assets to make up for any shortfall in our payment obligations.
Read it in 10-K Feb 11, 2026 at sec.gov
Quiet changesRisk Factors
The risks relating to these assumptions may be are exacerbated for development-stage product candidates due to the uncertainties around their development, labeling, regulatory approval, commercialization timing, anticipated pricing, manufacturing and supply, competing products or related factors.
Read it in 10-K Feb 11, 2026 at sec.gov
Quiet changesRisk Factors
Quiet changesRisk Factors
The market price of our Class A ordinary shares has been and may be volatile and could be subject to wide fluctuations.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedMD&A
RP Holdings is owned by Royalty Pharma plc and, indirectly, by various partnerships (the “Continuing Investors Partnerships”) and, in addition, post-Internalization (as defined below), by the Holders of RP Holdings Class E Interests (as defined below). RP Holdings is the sole owner of Royalty Pharma Investments 2019 ICAV (“RPI 2019 ICAV”), which is an Irish collective asset management vehicle and is the successor to Royalty Pharma Investments, an Irish unit trust. In 2022, we became an indirect owner of an 82% economic interest in Royalty Pharma Investments ICAV, which was previously owned directly by Royalty Pharma Investments. In connection with the Internalization, Royalty Pharma Investments distributed all of its assets to Royalty Pharma Investments 2011 ICAV (together with Royalty Pharma Investments ICAV, “Old RPI”).
Read it in 10-K Feb 11, 2026 at sec.gov
AddedMD&A
On January 10, 2025, we entered into an agreement (as amended, the “Purchase Agreement”) with RPM, Royalty Pharma Manager, LLC, a Delaware limited liability company (“RP Manager”) and the sellers named therein (the “Sellers”). Pursuant to the Purchase Agreement, RPM contributed substantially all of its assets and liabilities to RP Manager and we agreed to acquire all of the equity interests of RP Manager from the Sellers (the “Internalization”). The Sellers included our founder, chief executive officer and chairman, Pablo Legorreta, RPM I, LLC and RP MIP Holdings, LLC (“RP MIP Holdings”). The equity interest holders of RP MIP Holdings include our named executive officers and certain employees of the Legacy Manager, who became employees of Royalty Pharma, LLC, a wholly-owned subsidiary of RP Holdings, in connection with the Internalization. We completed the acquisition of RP Manager on May 16, 2025.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedMD&A
Equity Performance Awards (“EPAs”) represent 20% of the Net Economic Profit (as defined below) generated from investments made during each two-year investment period (each, a “Portfolio”). Net Economic Profit is defined as the aggregate cash receipts for all new portfolio investments in a Portfolio less Total Expenses, which is defined as interest expense, operating expense and recovery of acquisition cost related to that Portfolio. Distributions of EPAs occur only upon the satisfaction of specified performance and return thresholds. EPAs are generally settled in RP Holdings’ Class B Interests, which are immediately exchanged upon issuance for Class A ordinary shares. A portion of the EPAs may be paid in cash as a tax advance to cover income tax obligations incurred by the beneficial owners of the RP Holdings Class C Special Interest.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedMD&A
Mr. Legorreta granted ownership units in the entities that hold the RP Holdings Class C Special Interest to certain employees of RPM, who became employees of Royalty Pharma, LLC, a wholly-owned subsidiary of RP Holdings, in connection with the Internalization. These grants allow such employees to participate on a pro rata basis in the economic returns of the EPAs for a specific Portfolio (the “Employee EPAs”). Prior to the Internalization, Founder’s Equity, which included the Employee EPAs, was accounted for as an equity transaction and recorded as non-controlling interest. Following the Internalization, Founder’s Equity, which no longer includes Employee EPAs, continues to be accounted as non-controlling interest.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedMD&A
4. The Sellers’ indirect ownership in RP Holdings through their indirect ownership of RP Holdings’ Class E ordinary shares (the “RP Holdings Class E Interests”). In connection with the Internalization, we issued 24.5 million RP Holdings Class E Interests, subject to vesting conditions, to the Sellers (the “Holders of RP Holdings Class E Interests”) as part of the transaction considerations. Upon vesting, the RP Holdings Class E Interests become exchangeable on a one-for-one basis for Class A ordinary shares, and upon such exchange, the value of this non-controlling interest decreases.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedMD&A
The provision for credit losses on unfunded commitments, a non-cash item, represents the current expected credit losses on the unfunded portions of our funding arrangements with Revolution Medicines. Because we have limited protective rights with respect to each unfunded portion once the committed funding is provided, we are required to recognize an allowance for current expected credit losses based on our estimate of probability of future funding. We estimate this allowance using the probability of default and loss given default method. We are required to reassess our estimate of current expected credit losses as of each reporting date, and any subsequent change to such allowance, which can be income or expense, is reflected within Provision for credit losses on unfunded commitments in the consolidated statements of operations.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedMD&A
Following the Internalization, we no longer pay Management Fees; instead, employee compensation expenses represent the most significant component of G&A expenses. Employee compensation includes cash-based and share-based expenses. Share-based compensation expenses arising from the Internalization primarily include the following:
Read it in 10-K Feb 11, 2026 at sec.gov
AddedMD&A
1.Approximately 22.8 million RP Holdings Class E Interests with an aggregate fair value of approximately $755.4 million, which are expensed over vesting periods on a straight-line basis of generally five to nine years. As of December 31, 2025, we had $646.5 million of unrecognized compensation expense related to 19.5 million RP Holdings Class E Interests that is expected to vest over a weighted average period of 5.5 years.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedMD&A
2.The vesting of the Employee EPAs over their remaining service periods and the subsequent change in their fair value. The fair value of the Employee EPAs is driven by the performance of the investments within the Portfolio and will fluctuate based on the timing and amount of investments made during the investment period as well as the actual and expected returns on the investments.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedMD&A
Additionally, as each new Portfolio commences after the Internalization, any related Employee EPAs will also be recognized as share-based compensation expense over the required service periods of generally four years and included within General and administrative expenses in the consolidated statement of operations. Lastly, G&A expenses include rent, legal fees and other expenses for professional services.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedMD&A
Further, the net income attributable to the continuing non-controlling interests includes EPAs attributable to Founder’s Equity that we began recognizing in the first quarter of 2025 as certain conditions were met.
Read it in 10-K Feb 11, 2026 at sec.gov
AddedMD&A
Other royalty income and revenues were relatively flat in 2025 as compared to 2024.
Read it in 10-K Feb 11, 2026 at sec.gov
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RewordedMD&A
Royalty 2025 Royalty 2024 Royalty 2023 Cystic fibrosis franchise $ (259,353) Evrysdi $ 378,565 Tysabri $ 222,285 Tremfya (77,895) Cystic fibrosis franchise 256,814 Imbruvica 220,127 Xtandi (64,368) Crysvita 164,265 Tremfya 120,733 Promacta 54,772 IDHIFA (75,059) Promacta (41,617) Evrysdi 115,558 Tysabri (158,433) Evrysdi (46,077) Other (38,389) Other 65,894 Other 62,920 Total provision, exclusive of provision for credit losses (269,675) Total provision, exclusive of provision for credit losses 632,046 Total provision, exclusive of provision Provision for current expected credit losses 538,371 (26,163) Provision for current expected credit losses 100,415 Provision for current expected credit losses 22,285 Total provision $ (295,838) Total provision $ 732,461 Total provision $ 560,656
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedMD&A
RewordedMD&A
Through the Exchange Offer, investors which represented 82% of the aggregate limited partnership interests in the various partnerships (the “Legacy Legacy Investors Partnerships”) that owned Royalty Pharma Investments, an Irish unit trust (“Old RPI”), Partnerships exchanged their limited partnership interests in the Legacy Investors Partnerships for limited partnership interests in RPI US Partners 2019, LP, a Delaware limited partnership, or LP and RPI International Holdings 2019, LP, a Cayman Islands exempted limited partnership (together, which are part of the “Continuing Continuing Investors Partnerships”). Partnerships.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedMD&A
In April 2024, 2025, Vertex announced that the European Commission had granted EC approval for the label expansion of Kalydeco Kaftrio in combination with ivacaftor for the treatment of infants down to one month of age with cystic fibrosis patients ages 2 years and older who have certain mutations at least one non-class I mutation in the cystic fibrosis transmembrane conductance regulator (“CFTR”) gene.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedMD&A
In April 2024, July 2025, Vertex announced that the European Commission had granted approval (“EC”) approved Alyftrek for the label expansion of Kalydeco for the treatment of infants down to one month of age people with cystic fibrosis ages 6 years and older who have certain mutations at least one non-class I mutation in the cystic fibrosis transmembrane conductance regulator gene.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedMD&A
The net income attributable to the continuing non-controlling interests includes RP Holdings Class B Interests held by related to the Continuing Investors Partnerships for which and the related future net income will Holders of RP Holdings Class E Interests is expected to decline over time if the investors who indirectly own the RP Holdings Class B Interests and the Holders of RP Holdings Class E Interests, respectively, conduct exchanges for our Class A ordinary shares.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedMD&A
Proceeds from available for sale debt securities(1), (2) 21,226 19,786 1,440 Distributions from equity method investees(2) 105,149 23,641 43,882 Interest paid, net(2) 241,983 113,088 97,564 Development-stage funding payments - ongoing 452,000 2,000 2,000 Development-stage funding payments - upfront and milestone — 50,000 Distributions to legacy non-controlling interests - Portfolio Receipts(2) (354,901) (362,280) (376,987) Payments for Employee EPAs 10,943 — Adjusted EBITDA (non-GAAP) $ 2,966,223 $ 2,565,221 $ 2,805,701 Interest paid, net(2) (241,983) (113,088) (97,564) Portfolio Cash Flow (non-GAAP) $ 2,724,240 $ 2,452,133 $ 2,708,137
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedMD&A
Summarized Combined Balance Sheet As of December 31, 2024 2025 Current assets $ 53,380 27,054 Current interest receivable on intercompany notes due from Non-Guarantor Subsidiaries 23,908 Current intercompany notes receivable due from Non-Guarantor Subsidiaries 242,476 26,932 Non-current assets 3,074 926,732 Non-current intercompany notes receivable due from Non-Guarantor Subsidiaries 2,430,894 3,011,820 Current liabilities 1,100,681 515,312 Current interest payable on intercompany notes due to Non-Guarantor Subsidiaries 23,905 Current intercompany notes payable due to Non-Guarantor Subsidiaries 242,476 26,932 Non-current liabilities 6,613,747 9,147,894 Non-current intercompany notes payable due to Non-Guarantor Subsidiaries 1,609,898 2,208,840
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedMD&A
We recorded provision expense income for changes in expected cash flows for Tysabri, Imbruvica primarily related to the cystic fibrosis franchise, Tremfya, and Tremfya primarily Xtandi due to increases in sell-side equity research analysts’ consensus sales forecasts, partially offset by provision expense related to Evrysdi due to declines in sell-side equity research analysts’ consensus sales forecasts.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedMD&A
We have assembled a portfolio of royalties which entitles us to payments based directly on the top-line sales of many of the industry’s leading therapies, which includes royalties on more than 35 commercial products, including Vertex’s Trikafta, Trikafta and Alyftrek, GSK’s Trelegy, Biogen’s Tysabri and Spinraza, Roche’s Evrysdi, Astellas and Pfizer’s Xtandi, Johnson & Johnson’s Tremfya, Biogen’s Tysabri and Spinraza, AbbVie and Johnson & Johnson’s Imbruvica, Astellas and Pfizer’s Xtandi, Novartis’ Promacta, Pfizer’s Nurtec ODT, Servier’s Voranigo, Gilead’s Trodelvy, Amgen’s Imdelltra and Alnylam’s Amvuttra, among others, and 14 20 development-stage product candidates.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedMD&A
Cash provided by operating activities decreased by $218.8 $279.2 million in 2024 2025 as compared to 2023, 2024, primarily due to $450.0 million of higher payments for development-stage funding agreements and $116.7 million of higher interest payments, partially offset by a decrease $371.3 million increase in cash collections from financial royalty assets of $218.0 million. assets.
Read it in 10-K Feb 11, 2026 at sec.gov
RewordedMD&A
Quiet changesMD&A
R&D funding expense consists of certain development-stage funding payments that we have made to counterparties to acquire royalties or milestones on product candidates.
Read it in 10-K Feb 11, 2026 at sec.gov
Sources
The two latest 10-Ks on EDGAR, section by section. Each change links to the text at sec.gov.
Also
New risk factors: paragraphs with nothing like them last year, quoted in full.
Work with it
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/RPRX/export.csv") into a cell.