Form 10-K for the Fiscal Year Ended December 31, 2023
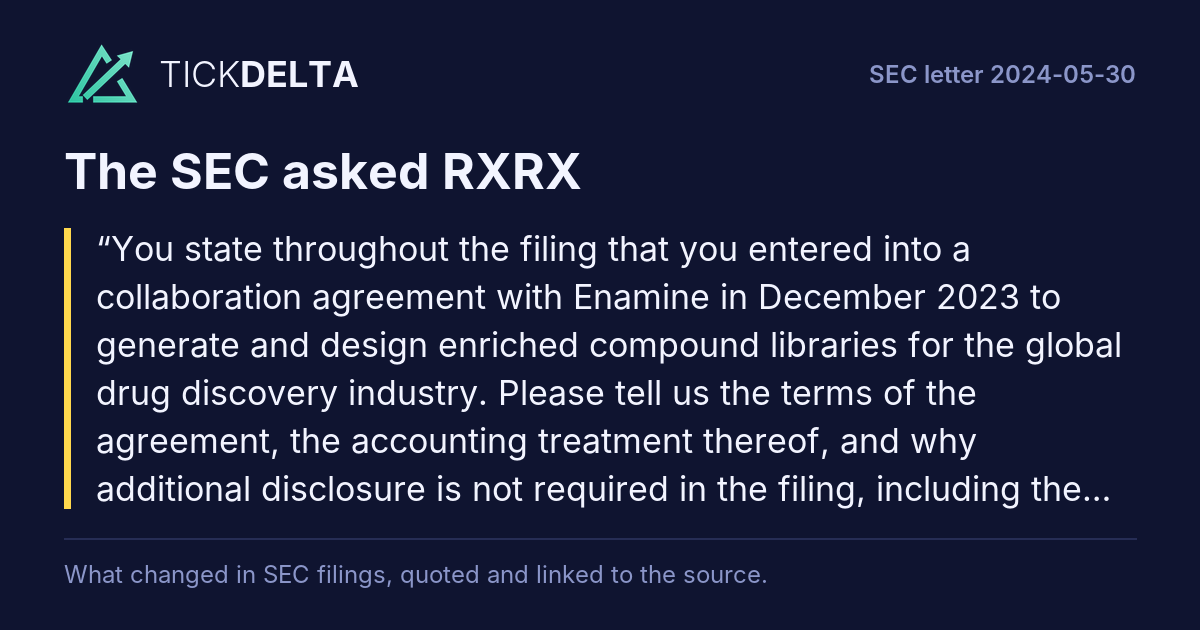
You state throughout the filing that you entered into a collaboration agreement with Enamine in December 2023 to generate and design enriched compound libraries for the global drug discovery industry. Please tell us the terms of the agreement, the accounting treatment thereof, and why additional disclosure is not required in the filing, including the financial statements.
No reply letter found.
First report after the SEC's letter of May 30, 2024: 10-Q filed Aug 8, 2024 ↗, against the 10-Q filed May 9, 2024 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Please confirm to us that the $22.0 million upfront payment for the Tempus agreement, which as disclosed on page 149 was paid with the issuance of 3.2 million shares, was recorded in research and development expense. Confirm to us that you will disclose your accounting policy applicable to such upfront payments in future filings or direct us to existing disclosure.Rest of the question
Also, please clarify to us, and in future filings, what line item the payments made in connection with the Tempus agreement are included in the table on page 157 and why.
No reply letter found.
First report after the SEC's letter of May 30, 2024: 10-Q filed Aug 8, 2024 ↗, against the 10-Q filed May 9, 2024 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
In future filings, please correct the label Comprehensive Loss to reflect that Net Loss and not Comprehensive Loss is added to Accumulated Deficit in all periods presented, or tell us why your current presentation is adequate.
No reply letter found.
First report after the SEC's letter of May 30, 2024: 10-Q filed Aug 8, 2024 ↗, against the 10-Q filed May 9, 2024 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
You disclose on page 69 that in July 2023 you entered into a collaboration agreement with NVIDIA to accelerate the development of your groundbreaking AI foundation models for biology and chemistry using your supercomputer, BioHive-1, and priority access on NVIDIA DGX™ Cloud.Rest of the question
Please tell us the following: • the terms of the collaboration agreement, the accounting treatment thereof, and why disclosure is not required in the filing, including the financial statements, and • why none of the proceeds from the NVIDIA private placement are required to be allocated to the concurrent collaboration agreement under ASC 606-10-25-9.
No reply letter found.
First report after the SEC's letter of May 30, 2024: 10-Q filed Aug 8, 2024 ↗, against the 10-Q filed May 9, 2024 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
In future filings on Form 10-K, please specifically state whether your internal controls over financial reporting are effective at the end of the reporting period. In closing, we remind you that the company and its management are responsible for the accuracy and adequacy of their disclosures, notwithstanding any review, comments, action or absence of action by the staff.
No reply letter found.
First report after the SEC's letter of May 30, 2024: 10-Q filed Aug 8, 2024 ↗, against the 10-Q filed May 9, 2024 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: closing letter, 2024-06-13