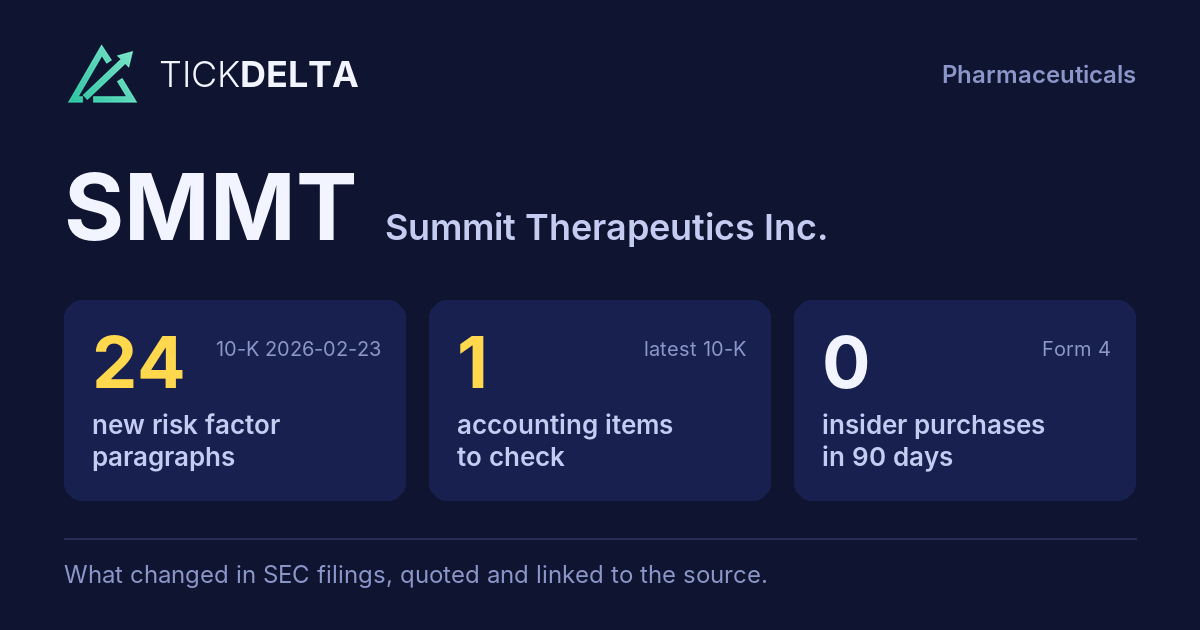
Screener / SEC EDGAR /CIK 0001599298 /10-K filed Feb 23, 2026, compared with Feb 24, 2025 /Numbers from the XBRL of the 10-Ks
Nasdaq Health care · Pharmaceuticals

Summit Therapeutics Inc. SMMT

Compare with peers Embed
SEC comment letters, last 20 years

5 reviews of SMMT's filings by SEC staff

UPLOAD and CORRESP
Reviews 5 latest letter Apr 2, 2026
Questions asked 36 each answered in the company's own letter
No closing letter 3 reviews without a letter saying the staff completed it

When the SEC's staff reviews a filing, it writes to the company with numbered questions, and the company answers each one in a letter. SEC publishes the exchange once the review is over, at least 20 business days later. A question is not an accusation; most reviews end with the company adding detail to its next filing.

How the reviews went

Every review on EDGAR, from the first staff letter to the letter that closes it

  1. 1. Staff letters 8 UPLOAD
  2. 2. Questions in them 36 numbered comments
  3. 3. Company replies 6 CORRESP
  4. 4. Reviews closed 2 of 5 closing letter

Half the closed reviews took 33 days or less from the first letter to the closing letter.

Form 10-K for the fiscal year ended December 31, 2025

2026-04-02 to 2026-04-27 · 1 question · 1 letter from the SEC, 1 from the company
Review closed 2026-04-27
Results discussion (MD&A)
After reviewing your response to this letter, we may have additional comments. Product Pipeline, page 4
SEC asked
Regarding the disclosure on page 6 about collaborating with multiple institutions globally and your investigator-sponsored trials program across several disease areas, please tell us and revise your future filings, beginning with your March 31, 2026 Form 10-Q, to specifically address the collaborations entered into with GSK and Revolution Medicines and provide the significant related terms of each, including any
Rest of the question

consideration exchanged thus far. We note these collaborations were entered into prior to the filing of your Form 10-K and are highlighted in your fourth quarter of 2025 earnings release, earnings call and accompanying slides/presentation. Management’s Discussion and Analysis of Financial Condition and Results of Operations, page Results of Operations, page 73 Your research and development (R&D) expenses increased more then 220% during 2025 and also made up half of your $1.08 billion net loss for the year ended December 31, 2. 2025 and 75% of your $221.3 million net loss for the year ended December 31, 2024. For 2025, oncology clinical trial related costs made up half of your R&D expenses, yet the explanation provided for the 164% increase in these costs during the year appears limited, i.e., you attribute the large change primarily to new clinical trials added and current clinical trials expanded. Given: i) the significance of oncology clinical trial related costs to consolidated R&D and, in turn, the significance of consolidated R&D to your results of operations; ii) the multiple clinical trials which you are currently conducting; and iii) the multiple indications for which you are currently evaluating ivonescimab, please tell us whether your oncology clinical trial related costs can be further disaggregated by indication, trial or some other level and revise future filings as applicable.

SMMT answered
In response to the Staff’s request, the

Company respectfully acknowledges the Staff’s comment and advises the Staff that there has not been any cash consideration exchanged in connection with our collaborations with GSK and Revolution Medicines to date. These are agreements to engage in one or more clinical trials combining ivonescimab with a third-party drug, where Summit is providing ivonescimab for the trial. The third party is acting as the study sponsor and is responsible for the associated costs of the studies beyond the cost of ivonescimab.
Rest of the answer

For these reasons, these collaborations do not include any upfront payments, milestone payments, or royalty sharing provisions.

In future filings, beginning with our Form 10-Q for the quarter ended March 31, 2026, the Company will provide additional disclosure related to the collaborations with GSK and Revolution Medicines and the significant related terms of each collaboration, including whether any cash consideration has been exchanged. The following disclosure will be included in our Form 10-Q for the quarter ended March 31, 2026:

In June 2025, the Company entered into a clinical trial collaboration with Revolution Medicines, Inc.

(“RevMed”) to evaluate ivonescimab in combination with three RevMed RAS(ON) inhibitors (the “RevMed Collaboration”). In January 2026, the Company entered into a clinical trial collaboration with GSK plc to evaluate ivonescimab in combination with GSK’s novel B7-H3, risvutatug rezetecan, in multiple solid tumors (the “GSK Collaboration”). Neither the RevMed Collaboration nor the GSK Collaboration include upfront payments, milestone payments, or royalty sharing provisions. For the quarter ended March 31, 2026, there was no cash consideration exchanged in connection with either the RevMed Collaboration or the GSK Collaboration.

Read in the reply
In its next report

First report after the company's reply of Apr 16, 2026: 10-Q filed Apr 30, 2026 ↗, against the 10-Q filed Oct 20, 2025 ↗.

The part of the filing the question names could not be found in both reports. Read them on sec.gov.
Also in this review: closing letter, 2026-04-27
Form 10-K

2024-12-19 to 2025-01-21 · 1 question · 1 letter from the SEC, 1 from the company
Review closed 2025-01-21
Non-GAAP measures
Form 8-K Filed February 20, 2024 · Exhibit 99.1, page 1
SEC asked
1. Certain of your non-GAAP measures include an adjustment for payments made to acquire in-process research and development (IPR&D) from Akeso, beginning in 2023. We note the company’s focus on the discovery, development, and commercialization of medicinal therapies.
Rest of the question

In this regard, it appears that costs for licenses that will be utilized to further the company’s focus and mission would be normal in the course of the company’s operations. Please tell us how you determined that the adjustments to exclude IPR&D are consistent with Question 100.01 of the C&DI on Non-GAAP Financial Measures.

SMMT answered
The Company acknowledges the Staff’s comment and advises the Staff that in its future filings that include non-GAAP financial measures, for all periods presented, the Company will no longer adjust for in-process research and development expenses. The Company will recast prior period information to conform to this revised presentation and will provide a footnote to the non-GAAP reconciliation tables addressing the change as compared to previously furnished information.
Read in the reply
In its next report

First report after the company's reply of Jan 6, 2025: 10-K filed Feb 24, 2025 ↗, against the 10-K filed Feb 20, 2024 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Also in this review: closing letter, 2025-01-21

Form S-3

2023-01-12 to 2023-01-20 · 4 questions · 1 letter from the SEC, 1 from the company
No closing letter
Risk factors
SEC asked (1)
Please revise to explain why the Board formed a Special Committee and identify the members of that committee.
SMMT answered
In response to the Staff’s comment, the Company has revised its disclosure on page 41 of the Registration Statement.
Read in the reply
SEC asked (2)
We note your disclosure that in determining the Subscription Price the Special Committee considered the average price for the 30-day period prior to the filing of the preliminary proxy statement on November 29, 2022.
Rest of the question

With a view to disclosure and with reference to your risk factor disclosure at the top of page 31, please tell what consideration, if any, the Special Committee or Board has given or will give to revising the Initial Price to reflect more recent market trading. In this regard, we note that the stock price increased significantly beginning in early December. To the extent that the Initial Price will be set at a significant discount to the current market price, please revise the cover page to highlight the size of the discount and the attendant risks to shareholders.

SMMT answered
In response to the Staff’s comment, the Company has revised its disclosure on the cover page, page 3, page 10, page 31 and page 41 of the Registration Statement.

also advise the Staff supplementally that on December 6, 2022, the Company publicly released information regarding its: (i) entrance into the Collaboration and License Agreement with Akeso, Inc.; (ii) entrance into a Note Purchase Agreement and promissory notes pursuant to which the Company agreed to sell to each of Mr. Robert W. Duggan and Dr.
Rest of the answer

Maky Zanganeh unsecured promissory notes in the aggregate amount of $520 million; and (iii) approval by the Board of a $500 million rights offering to its stockholders, including the pricing of such rights offering (specifically including the Initial Price and Alternate Price). The disclosure of this information, including the proposed rights offering and pricing, occurred immediately prior to the significant increase in stock price in early December referred to above. The Company does not believe that a change to the previously disclosed terms of the Rights Offering would be fair to those stockholders who relied on this public disclosure, and accordingly the Company does not plan to change any of the previously disclosed information (including the pricing). This information is described on page 10 of the Registration Statement in a Q&A titled “Why did our board of directors elect to price the Rights Offering at the lesser of the Initial Price and the Alternate Price?”

Read in the reply
SEC asked (3)
With a view to disclosure and with reference to the second risk factor disclosures on pages 31 and 32, please tell us what consideration the Board gave to including a floor price for the offer and why it decided to include the Alternate Price feature. Also, discuss what consideration, if any, given to making subscriptions revocable in the event that the stock price materially decreases during the offering period.
Rest of the question

Similarly tell us what steps you would take if the Board were to determine during the pendency of the offering to conduct a reverse stock split either during or immediately following the offering.

SMMT answered
Given that the Board reserves the right to terminate the Rights Offering at any time, the Special Committee and Board determined that a floor price was not in the best interests of the Company, especially given concerns that setting a floor price can have the effect of market forces leading to a price at the floor price. The Company believes that the Alternate Price mechanics provide subscribing stockholders with certain protections in the event of a decline in market share price.
Rest of the answer

The Company believes that inclusion of the Alternate Price provides protection for a market price decline and has not considered making subscriptions revocable. In further response to the Staff’s comment, the Company has revised its disclosure on page 31 of the Registration Statement.

While the Board reserves the right to effect the reverse stock split prior to January 6, 2024, we do not intend to effect the reverse stock split prior to the closing of the Rights Offering and issuance of shares thereunder. In accordance herewith, please see the Company’s revised disclosure on page 32 of the Registration Statement.

Read in the reply
SEC asked (4)
We note your statement on the cover page that to the extent the Alternate Price is lower than the Initial Price, you will sell additional shares of common stock. Please also revise your disclosure to discuss your plans if the Alternate Price were to decline such that the number of shares of common stock to be offered would cause you to exceed the number of authorized shares of common stock set forth in your
Rest of the question

certificate of incorporation. We remind you that the company and its management are responsible for the accuracy and adequacy of their disclosures, notwithstanding any review, comments, action or absence of action by the staff. Refer to Rules 460 and 461 regarding requests for acceleration. Please allow adequate time for us to review any amendment prior to the requested effective date of the registration statement.

SMMT answered
In response to the Staff’s comment, the Company has revised the disclosure on the cover page and page 41 of the Registration Statement.

note that the Company filed a current report on Form 8-K earlier today, and the Company has revised the disclosure in the Registration

Statement to reflect the matters disclosed in the Form 8-K.

believe we have been responsive to the Staff’s comments. Please direct any questions concerning this letter to the undersigned at (212) 589-4233 or [email protected].
Read in the reply

Form F-3

2016-05-25 to 2016-06-01 · 1 question · 1 letter from the SEC, 1 from the company
No closing letter
Exhibit 5.1
SEC asked
We note in paragraph 5(ii) of Exhibit 5.1 that counsel opines that the ordinary shares will be “validly allotted and issued and fully paid.” Please file an opinion that also addresses whether the ordinary shares will be non-assessable, as that term is understood under U.S. law. For guidance, please refer to Section II.B.1.c of Staff Legal Bulletin No. 19 (October 14, 2011).
SMMT answered
Pursuant to Rule 461 promulgated under the Securities Act of 1933, as amended, Summit Therapeutics plc (the

“Registrant”) hereby requests acceleration of the effective date of its Registration Statement on Form F-3 (File No. 333-211301), as amended (the “Registration Statement”), so that it may become effective at 4:00 p.m.

Eastern time on June 3, 2016, or as soon thereafter as practicable.

The Registrant hereby acknowledges that:

(i) should the Securities and Exchange Commission (the “Commission”) or the staff, acting pursuant to delegated authority, declare the Registration Statement
Rest of the answer

effective, it does not foreclose the Commission from taking any action with respect to the Registration Statement;

(ii) the action of the Commission or the staff, acting pursuant to delegated authority, in declaring the Registration Statement effective, does not relieve the Registrant from its full responsibility for the adequacy and accuracy of the disclosure in the Registration Statement; and

(iii) the Registrant may not assert the action of the Commission or the staff, acting pursuant to delegated authority, in declaring the Registration Statement effective as a defense in any proceeding initiated by the

Commission or any person under the federal securities laws of the United States.

Read in the reply

Form F-1

2014-12-31 to 2015-03-02 · 29 questions · 4 letters from the SEC, 2 from the company
No closing letter
AcquisitionsIncome taxesRisk factorsResults discussion (MD&A)Pensions
SEC letter of Dec 31, 2014 ↗ no reply letter on EDGAR (the company may have answered in an amended filing)
Our Company, page 1
SEC asked (1)
Your product pipeline table should highlight your products in development that are more likely to result in an approved product in the foreseeable future. Research and development activities that precede the identification of a molecule and a related indication are too remote to be highlighted in the pipeline table.
Rest of the question

Accordingly, please limit your table to products that are at least in the preclinical stage of development. Also, please list your most advanced drug candidate (SMT19969) first and your next most advanced candidate (SMT C1100) second.

SMMT answered

No reply letter found.

Our future success depends on our ability to retain…, page 38
SEC asked (2)
In addition to your CEO Glyn Edwards, please expand this risk factor to identify all principal or key members of your executive and scientific teams upon whom you are highly dependent.
SMMT answered

No reply letter found.

Special Note Regarding Forward-Looking Statements And Industry Data, page 47
SEC asked (3)
We note your statement that “[a]lthough we believe these industry publications and thirdparty research, surveys and studies are reliable, we have not independently verified such data.” This statement appears to infer that you are not liable for statements included in your registration statement. Please delete this sentence or specifically state that you are responsible for the referenced information.
SMMT answered

No reply letter found.

Research and Development Expenses, page 58
SEC asked (4)
Please expand your disclosures to include the total costs incurred from inception to date for each product candidate separately.
SMMT answered

No reply letter found.

Recognition of Research and Development Expenses, page 61
SEC asked (5)
Please revise your disclosure to state whether there have been any material adjustments to estimates based on the actual costs incurred for each period presented and if so please quantify the amounts.
SMMT answered

No reply letter found.

General and Administrative Expenses, page 63
SEC asked (6)
Please explain to us why the provision made for milestone payments is classified as a general and administrative expense as opposed to a research and development expense.
SMMT answered

No reply letter found.

Analysis of Trial Results, page 84
SEC asked (7)
Please define the terms in vitro and in vivo the first time those terms are used.
SMMT answered

No reply letter found.

BioMarin Phase 1 Clinical Trial in Healthy Volunteers, page 85
SEC asked (8)
We note your disclosure regarding BioMarin’s Phase 1 clinical trial utilizing a prior formulation of SMT C1100 in healthy volunteers. Please expand your disclosure to explain why BioMarin elected to discontinue the development of this formulation and transfer all assets and rights back to you.
SMMT answered

No reply letter found.

Planned Clinical Trials, page 85
SEC asked (9)
Please revise your disclosure to identify the following as to each completed and ongoing clinical trial for SMT C1100 and SMT 19969:  who conducted or will conduct the clinical trial;  the location(s) of each clinical trial; and  the date(s) and person(s) who filed INDs with the FDA as to any trials that were or will be conducted in the United States.
SMMT answered

No reply letter found.

Potential Diet Independent Formulation of SMT C1100, page 88
SEC asked (10)
Please revise your disclosure to indicate what you consider to be a diet that has the “appropriate proportions of fat, protein and carbohydrates” to possess the potential to improve the plasma levels of SMT C1100.
SMMT answered

No reply letter found.

SMT19969 for the Treatment of CDI, page 90
SEC asked (11)
Please discuss explain why you switched from an aqueous suspension of SMT19969 between your completed Phase 1 clinical trial to a capsule form of delivery in your ongoing Phase 2 clinical trial.
SMMT answered

No reply letter found.

University of Oxford, page 95
SEC asked (12)
We note your disclosure on page 70 and page 95 regarding the research sponsorship agreement with the University of Oxford and ISIS. Please revise this section to specify the obligations under the agreement owed by the University of Oxford and ISIS and to disclose the maximum amount you have agreed to fund over a three-year research period under this agreement.
SMMT answered

No reply letter found.

Description of Share Capital, page 137
SEC asked (13)
Please expand your disclosure to briefly describe any provision of your memorandum of association or articles of association that would have an effect of delaying, deferring or preventing a change in control.
SMMT answered

No reply letter found.

Consolidated Statement of Comprehensive Income, page F-13
SEC asked (14)
It appears as though you have elected under paragraph 99 of IAS 1 to classify expenses using the function of expense method described in paragraph 103 of IAS 1. However, share-based compensation expense and depreciation and amortization expense would fall under the nature of expense method under paragraph 102 of IAS 1.
Rest of the question

Therefore, please revise your presentation to classify share-based compensation expense and depreciation and amortization expense by functional expense. Disclose the share-based compensation expense amounts and the depreciation and amortization expense amounts in the notes to the financial statements rather than on the face of the statement of comprehensive loss.

SMMT answered

No reply letter found.

Research and development, page F-19
SEC asked (15)
In this policy you indicate that the criteria for capitalizing development costs are not met until a product has been submitted for regulatory approval. In the second paragraph of your disclosure regarding research and development expenses on page 61, you indicate that regulatory approval is the earliest point at which capitalization of development costs can be achieved.
Rest of the question

Please revise your disclosure to be consistent. To the extent that you believe capitalization of development costs can occur upon the filing for regulatory approval, please provide us your analysis supporting your conclusion and reference for us the authoritative literature upon which you relied.

SMMT answered

No reply letter found.

Business combinations, page F-22
SEC asked (16)
Please explain to us how you concluded that the acquisition of MuOx Limited was a business and specifically identify the processes that you acquired. Reference for us the authoritative literature you relied upon to support your determination that MuOx is a business.
SMMT answered

No reply letter found.

MuOx, page F-35
SEC asked (17)
You state that for any IP arising from research carried out under the sponsored research agreement, for which the Group has not exercised the option to acquire a license, the Group would be obligated to pay milestone payments of up to £75,000. However, on page 70 it appears that you would be obligated to make the milestone payment for any arising IP for which you have exercised the option and obtained a license.
Rest of the question

Please clarify. 17. Deferred tax, page F-36

SMMT answered

No reply letter found.

MuOx, page F-35
SEC asked (18)
Please tell us why you do not recognize any of your unrecognized deferred tax assets to offset the deferred tax liability recognized upon your acquisition of MuOx Limited. In your response, tell us whether you file a consolidated income tax return that includes the results of MuOx. Reference for us the authoritative literature you rely upon to support your accounting.
SMMT answered

No reply letter found.

Exhibits
SEC asked (19)
Please file the MuOx Ltd. acquisition agreement and the 2009 funding agreement as exhibits.
SMMT answered

No reply letter found.

Other Comments
SEC asked (20)
Please submit all exhibits as soon as practicable. We may have further comments upon examination of these exhibits.
SMMT answered

No reply letter found.

Other Comments
SEC asked (21)
Please confirm that the graphics included in your registration statement are the only graphic, visual, or photographic information you will use in your prospectus. If those are not the only graphics, please provide any additional graphics prior to their use for our review.
SMMT answered

No reply letter found.

Other Comments
SEC asked (22)
Please supplementally provide us with copies of all written communications, as defined in Rule 405 under the Securities Act, that you, or anyone authorized to do so on your behalf, present to potential investors in reliance on Section 5(d) of the Securities Act, whether or not they retain copies of the communications.
SMMT answered

No reply letter found.

Other Comments
SEC asked (23)
Your exhibit index indicates that you have submitted a confidential treatment request with respect to portions of certain of your exhibits. Please note that our comments on your request for confidential treatment will be provided under separate cover.
SMMT answered

No reply letter found.

Other Comments
SEC asked (24)
Please be advised that the Office of International Corporate Finance has not yet completed their examination of the draft registration statement. We will transmit any comments they may promptly upon completion of their examination.
Rest of the question

If you intend to respond to these comments with an amended draft registration statement, please submit it and any associated correspondence in accordance with the guidance we provide in the Division's October 11, 2012 announcement on the SEC website at http://www.sec.gov/divisions/corpfin/cfannouncements/drsfilingprocedures101512.htm. Please keep in mind that we may publicly post filing review correspondence in accordance with our December 1, 2011 policy (http://www.sec.gov/divisions/corpfin/cfannouncements/edgarcorrespondence.htm). If you intend to use Rule 83 (17 CFR 200.83) to request confidential treatment of information in the correspondence you submit on EDGAR, please properly mark that information in each of your confidential submissions to us so we do not repeat or refer to that information in our comment letters to you.

SMMT answered

No reply letter found.

SEC letter of Jan 22, 2015 ↗ no reply letter on EDGAR (the company may have answered in an amended filing)
Principal Shareholders, page 135
SEC asked (1)
Please include a statement that provides the number of record holders in the United States and the corresponding percentage of your outstanding stock currently held in the United States. See Item 7.A.2 of Form 20-F.
SMMT answered

No reply letter found.

Description of Share Capital, page 137
SEC asked (2)
To the extent practicable, please replace your qualifying references to the Companies Act of 2006 and “Uncertificated Securities Regulations 2001” with substantive disclosure. Your use of the term “subject to” often implies additional rights, privileges, or restrictions that are not explained in your descriptions.
SMMT answered

No reply letter found.

SEC letter of Feb 10, 2015 ↗ no reply letter on EDGAR (the company may have answered in an amended filing)
Description of Share Capital, page 140
SEC asked (1)
Please revise your disclosure to describe in detail the relevance of entering the shares in the register of members (shareholders), including the procedures and timing required to make appropriate entries. Please include a statement in this section that the company will perform the procedures necessary to register the shares in the register of members.
Rest of the question

We note that the depositary will initially hold the ordinary shares underlying the ADSs. You should therefore discuss the ability to seek rectification of the register of members and consider disclosing any related risks as necessary.

SMMT answered

No reply letter found.

Exhibit 5.1
SEC asked (2)
Please submit a revised exhibit 5.1 responsive to the following.  Under Documents Reviewed and Searches and Enquiries please state that you have examined all documents and made all enquiries necessary for you to formulate you opinion.  In 2.7 you may state that you express no opinion as to the laws or regulations of any jurisdiction other than England and Wales.
Rest of the question

We do not believe it is appropriate for you to state that you express no opinion as to any jurisdiction.  In the last sentence of the opinion, we suggest that you delete the words “and such liability is expressly denied.” However, we do not object to you stating that you do not admit you are an expert or are in the category of persons whose consent is required.

SMMT answered

No reply letter found.

Exhibit 5.1
SEC asked
Legal counsel should revise Exhibit 5.1 to remove the entire last sentence of the opinion which reads “Our liability in giving this opinion is limited to you, our client, and our consent is not to be taken as an acknowledgement that we accept liability to any person other than you, our client.”
SMMT answered
Pursuant to Rule 461 under the Securities Act of 1933, as amended (the “Act”), we hereby join Summit Therapeutics plc in requesting that the effective date of the above-referenced registration statement be accelerated to Wednesday March 4, 2015, at 4:00 p.m., Eastern time, or as soon thereafter as practicable.

In connection with this acceleration request and pursuant to Rule 460 under the Act, please be advised that from February 20, 2015 through the date hereof, the undersigned effected the following approximate distribution of copies of the Preliminary Prospectus dated February 20,
Rest of the answer

2015:

-

0 to prospective underwriters;

421 to institutional investors;

0 to prospective dealers; and

959 to others (including individuals).

This is to further advise you that the underwriters have complied and will continue to comply with SEC release No. 33-4968 and Rule 15c2-8 under the Securities Exchange Act of 1934, as amended.

[Remainder of Page Intentionally Left Blank]

Read in the reply

Also in this review: company letter, Mar 2, 2015

Letters without questions

Other letters

UPLOAD and CORRESP
13 other letters: notices that a filing will not be reviewed, requests to declare a registration effective, and the like

From the SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), 29 letters filed since 2014-12-31. Questions and answers are matched by their numbers; topics come from words in each question. The reports are compared word for word (same form, before the first SEC letter against the first report after the company's reply). No AI.

Sources

The SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), matched question by question. No AI.

Also

Filings: the letters in the filing list.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/SMMT/export.csv") into a cell.

Next in Owners and insiders:Insider trades
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.