Screener / SEC EDGAR /CIK 0001627475 /10-K filed Feb 13, 2026, compared with Feb 13, 2025 /Numbers from the XBRL of the 10-Ks
Nasdaq Technology · Data Processing

Upwork, Inc UPWK

Compare with peers Embed
New in the 10-K 8 paragraphs with nothing like them in the 10-K filed Feb 13, 2025 New in the 10-Q 10 paragraphs not in the 10-Q filed Aug 10, 2026 10-Q against the 10-K 42 risk factor paragraphs and sentences added or reworded

New risk paragraphs, branching off last year

Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Feb 13, 2025. A box jumps to the paragraph as filed, below.

8 new

Paragraphs with nothing like them in last year's 10-K

Quoted exactly

8 paragraphs in Risk Factors of the 10-K filed Feb 13, 2026 with nothing like them in the 10-K filed Feb 13, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.

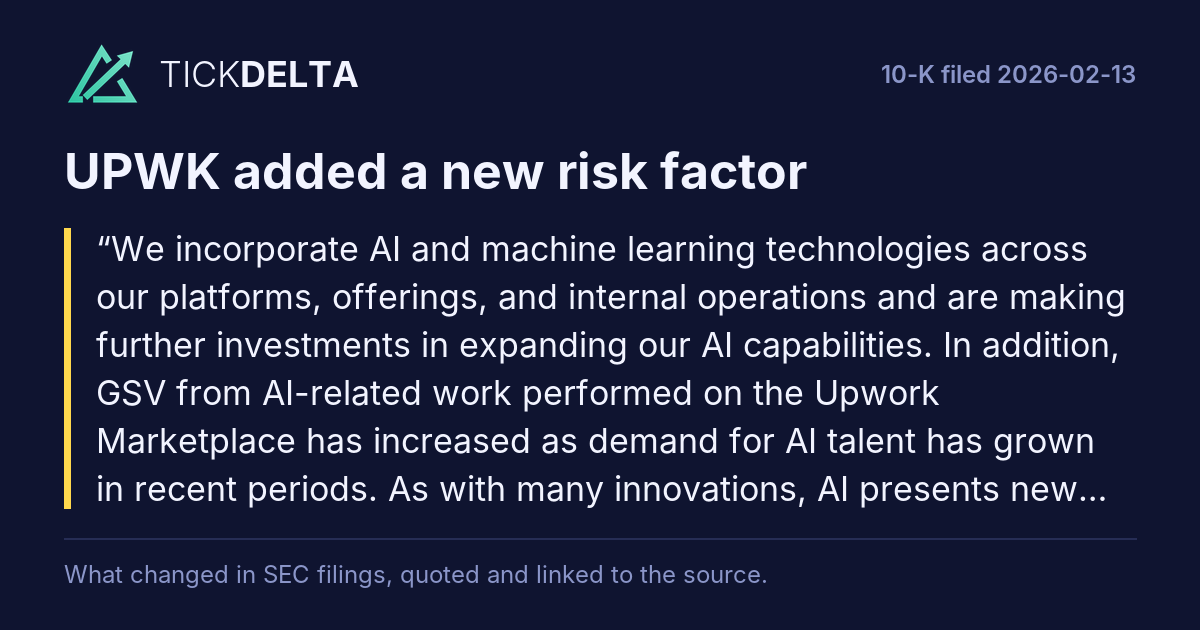
We incorporate AI and machine learning technologies across our platforms, offerings, and internal operations and are making further investments in expanding our AI capabilities. In addition, GSV from AI-related work performed on the Upwork Marketplace has increased as demand for AI talent has grown in recent periods. As with many innovations, AI presents new and evolving risks and challenges that could undermine or slow its adoption or cause us to experience brand or reputational harm, competitive harm, legal liability, new or enhanced governmental or regulatory scrutiny, and to incur additional costs to resolve such issues, each of which could adversely impact our business, operating results, and financial condition. For example, AI outputs may be, or alleged to be, deficient, inaccurate, inappropriate, biased, or infringing on the intellectual property rights of third parties. Perceived or actual technical, legal, compliance, privacy, security, ethical, or other issues relating to the use of AI may cause public confidence in AI generally or in our use of AI to be undermined, which could slow our customers’ adoption of our offerings, services, and features that use AI or result in a decrease in demand for AI-related work. In addition, the rapid evolution of AI will require significant resources to develop, integrate, and maintain the AI technologies included in our offerings, services, and features in order to remain competitive and to implement these technologies responsibly and minimize unintended or harmful impacts. There can be no assurance that the development and deployment of such technologies will be successful or cost effective.

Read in the 10-K

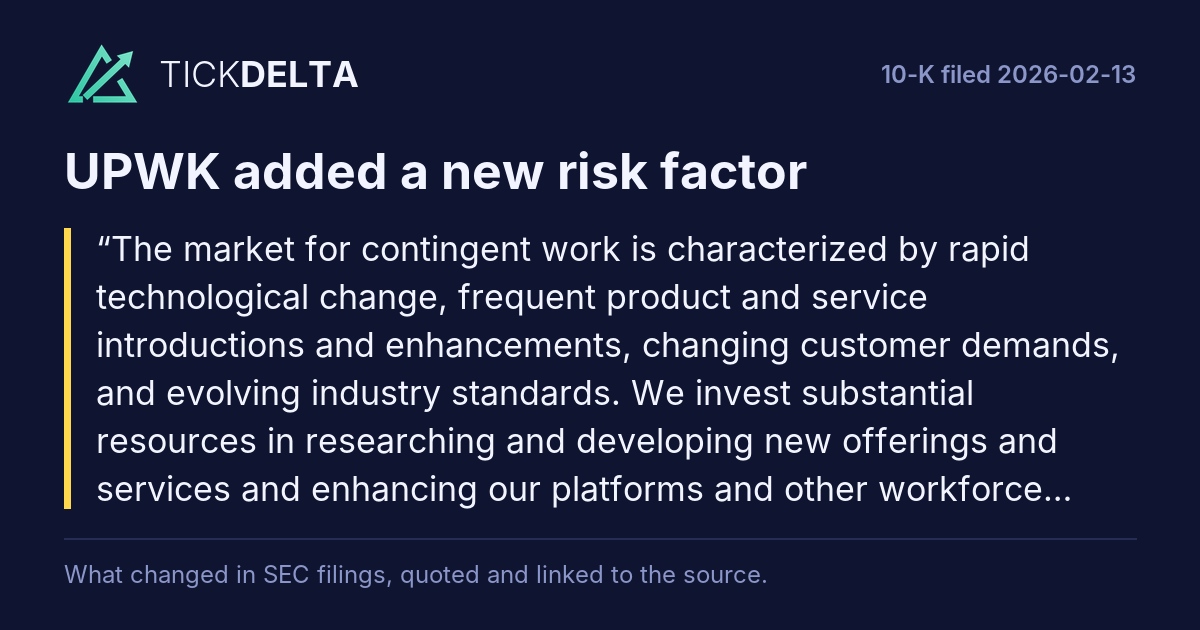
The market for contingent work is characterized by rapid technological change, frequent product and service introductions and enhancements, changing customer demands, and evolving industry standards. We invest substantial resources in researching and developing new offerings and services and enhancing our platforms and other workforce solutions by incorporating additional features, improving functionality, modernizing our technology,

Read in the 10-K

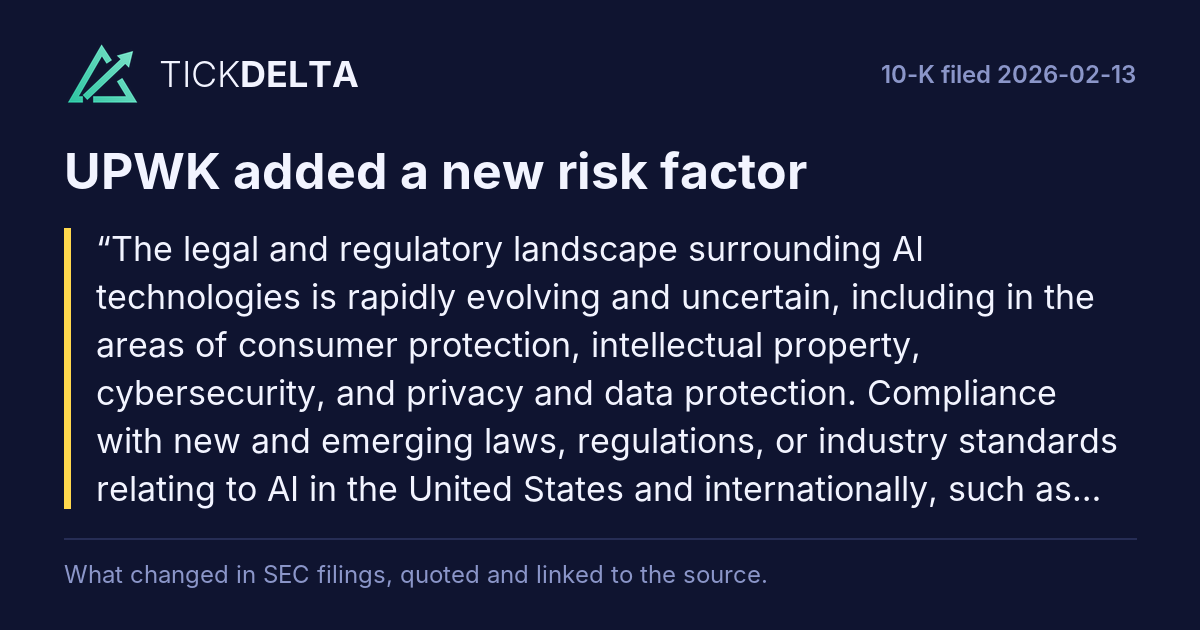
The legal and regulatory landscape surrounding AI technologies is rapidly evolving and uncertain, including in the areas of consumer protection, intellectual property, cybersecurity, and privacy and data protection. Compliance with new and emerging laws, regulations, or industry standards relating to AI in the United States and internationally, such as U.S. state regulations and the E.U. AI Act, may impose significant operational costs and may limit our, our vendors’, or our customers’ ability to develop, deploy, or use existing or future AI technologies. As a result, our ability to adapt our existing platforms and offerings or develop new offerings, services, and features using AI may be limited or restricted and demand for AI-related work may decline, which could adversely impact our business, operating results, and financial condition.

Read in the 10-K

work are remote, which may make it more difficult to control use of confidential materials, increasing the risk that our source code or other confidential or trade secret information may be exposed.

Read in the 10-K

In particular, Lifted’s Enterprise offerings include its subsidiaries employing talent on a temporary basis and placing such individuals in clients’ workplaces. Lifted and its subsidiaries’ ability to control the workplace environment is limited. As the employer of record of temporary employees, Lifted subsidiaries incur a risk of liability to their temporary employees for various workplace events, including claims of physical injury, discrimination, harassment, or failure to protect confidential personal information. In addition, the talent engaged through Lifted may access client workspaces from their personal devices through cloud-based systems. If cybersecurity incidents were to occur as a result, Lifted may face legal and contractual liability, reputational damage, loss of business, and other expenses. Lifted also incurs a risk of liability to clients resulting from allegations of damages caused by talent acting on phishing emails, cyberattacks, and other errors, omissions, or theft, or allegations of compromise of client confidential information. In some cases, Lifted or a Lifted subsidiary has agreed to indemnify clients in respect of these types of claims.

Read in the 10-K
Show the other 3

•fluctuations in the prices that talent charge clients on the Upwork Marketplace;

Read in the 10-K

costs of compliance. The impact and burden of these regulations and proposed regulations on our business and the businesses of our customers is uncertain and may have a negative impact on our business.

Read in the 10-K

limitation under Section 382 of the Internal Revenue Code of 1986, as amended, which we refer to as the Code. The California state NOL carryforward amounts will begin to expire in 2032 if not utilized.

Read in the 10-K

Paragraphs in the 10-Q filed Nov 2, 2026 that were not in the one before

New in the latest 10-Q

10 paragraphs in the 10-Q filed Nov 2, 2026 with nothing like them in the 10-Q filed Aug 10, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.

Financial statements and notes

As of December 31, 2025, the if-converted value of the Notes did not exceed the outstanding principal amount.

Read in the 10-Q

(in thousands) Restructuring Liability Beginning balance as of January 1, 2026 $ — ─────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────── Restructuring charges incurred for the six months ended June 30, 2026 13,836 Restructuring charges incurred for the three months ended September 30, 2026 4,281 Cash payments for the nine months ended September 30, 2026 (12,707) Non-cash adjustments for the nine months ended September 30, 2026 $ (3,476) Ending balance as of September 30, 2026 $ 1,934

Read in the 10-Q

On October 30, 2026, Lifted completed the acquisition of 100 % of the equity interests of WorkMotion Software GmbH, a privately held, Germany-based employer-of-record business, for cash consideration of approximately $ 129.7 million. The Company funded the purchase price with cash on hand. The Company will account for the transaction as a business combination in accordance with ASC Topic 805 - Business Combinations (“ASC 805”).

Read in the 10-Q

The Company has not yet completed its initial accounting for the transaction, as the acquisition closed shortly before these condensed consolidated financial statements were issued. Accordingly, certain ASC 805 disclosures are not yet available, including the allocation of the purchase consideration to the fair values of assets acquired and liabilities assumed, including goodwill and the qualitative factors that comprise it. The Company expects to complete the acquisition accounting within the measurement period.

Read in the 10-Q

Enterprise revenue is expected to increase in the fourth quarter of 2026, as compared to the third quarter of 2026, driven by Enterprise Solutions, partially offset by an expected decline in Managed Services Revenue. We are focused on supporting existing Enterprise clients and continue to invest in the development and expansion of Lifted.

Read in the 10-Q
Show the other 5

The increases in amortization for both periods reflect our investments in the Upwork Marketplace, including AI-enabled features and agentic capabilities that were placed into service at the end of year 2025.

Read in the 10-Q

September 30, 2026 and December 31, 2025, we had $228.0 million and $294.4 million in cash and cash equivalents, respectively. As of September 30, 2026 and December 31, 2025, we had $76.3 million and $378.4 million in marketable securities, respectively. The decrease in cash, cash equivalents, and marketable securities from December 31, 2025 was primarily due to the repayment of the Notes (as defined below) and repurchases of our common stock.

Read in the 10-Q

Risk Factors

websites may not be prominent enough to drive sufficient traffic to our websites, and we may not be able to influence search engine results.

Read in the 10-Q

under the European Payment Services Directive or other international laws and regulations or may choose to obtain such a license even if not required or to support new products or services.

Read in the 10-Q

There were no unregistered sales of equity securities during the three months ended September 30, 2026.

Read in the 10-Q

The 10-Q's risk factors against the 10-K

Item 1A of the 10-Q filed Nov 2, 2026 against Item 1A of the 10-K filed Feb 13, 2026. A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed. Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed, Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal (cut words struck through, new words highlighted). Text on the page, not a score; each links to the filing at sec.gov.

Added10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
To grow and maintain our business, offerings, and features, we need to continue to establish and maintain relationships with third parties, such as staffing providers, software and technology vendors, including third-party providers of AI technologies, and payment processing and disbursement providers. As our agreements with third-party partners terminate or expire, we may be unable to renew or replace these

Read it in the 10-Q at sec.gov

Added10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
websites may not be prominent enough to drive sufficient traffic to our websites, and we may not be able to influence search engine results.

Read it in the 10-Q at sec.gov

Show the other 19
Added10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
Our platforms enable customers to manage important aspects of their businesses, and any errors, defects, disruptions in service, or other performance or availability problems with our platforms or other workforce solutions, or our inability to adequately prevent or timely detect or remedy errors, defects, or

Read it in the 10-Q at sec.gov

Added10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
financial condition, and we could be required to make costly and burdensome changes to our business practices or compliance programs.

Read it in the 10-Q at sec.gov

Added10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
keeping, voting, proxy disclosure and other rules and regulations that would increase our operating and compliance costs, could make it impractical for us to continue our business as contemplated, and could have a material adverse effect on our business.

Read it in the 10-Q at sec.gov

Added10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
• requiring us to comply with restrictive and financial covenants under the Credit Agreement - including limits on incurring indebtedness, granting liens, making investments and acquisitions, paying dividends and repurchasing stock, disposing of assets, and transacting with affiliates, and the maintenance of a maximum Consolidated Net Leverage Ratio and minimum Consolidated Fixed Charge Coverage Ratio tested quarterly - a breach of which could result in an event of default;

Read it in the 10-Q at sec.gov

Added10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
• exposing us to increased interest expense to the extent we incur variable-rate borrowings under the Revolving Credit Facility;

Read it in the 10-Q at sec.gov

Added10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
• subjecting substantially all of our assets to liens securing the Revolving Credit Facility, and, following an event of default (including upon a change of control), permitting the lenders to terminate their commitments, accelerate our borrowings, and foreclose on those assets;

Read it in the 10-Q at sec.gov

Added10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
• limiting our flexibility to plan for, or react to, changes in our business, including our ability to pursue or fund strategic initiatives or acquisitions; and

Read it in the 10-Q at sec.gov

Reworded10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
If we were obligated to register as an “investment company,” we would have to comply with a variety of substantive requirements under the Investment Company Act that impose, among other things, limitations on capital structure, restrictions on specified investments, prohibitions on transactions with affiliates, and compliance with reporting, record keeping, voting, proxy disclosure and other rules and regulations that would increase our operating and compliance costs, could make it impractical for us to continue our business as contemplated, and could have a material adverse effect on our business.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
As a result, our ability to adapt our existing platforms and offerings or develop new offerings, services, and features using AI may be limited or restricted restricted, third-party providers of AI technologies may limit, restrict, or terminate our access to or use of their offerings or impose more restrictive terms, and demand for AI-related work may decline, which could adversely impact our business, operating results, and financial condition.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
Our efforts to attract and retain customers may not be successful or cost effective, and if customers, particularly significant clients, cease or reduce their use of our offerings and services for any reason, our business, operating results, and financial condition would be adversely affected.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
During the year nine months ended December 31, 2025, September 30, 2026, we repurchased and subsequently retired 9.3 8.3 million shares of our common stock for an aggregate amount of $136.0 $109.7 million under the Share Repurchase Authorizations, and we had $64.0 $254.3 million available for repurchases under the 2025 2026 Share Repurchase Authorization as of December 31, 2025. September 30, 2026.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
Any of the foregoing could, individually or in the aggregate, harm our reputation, reduce demand for our platforms and other workforce solutions, and adversely affect our business, operating results, and financial condition, and we could be required to make costly and burdensome changes to our business practices or compliance programs.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
The legal and regulatory landscape surrounding AI technologies is rapidly evolving and uncertain, including in the areas of consumer protection, intellectual property, cybersecurity, and privacy and data protection. protection, legal responsibility for actions taken by an AI agent without a user’s explicit direction, and worker classification.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
The federal NOL carryforwards of $2.0 million generated after December 31, 2017 can be carried forward indefinitely with utilization in any year limited to 80% of our taxable income or any limitation under Section 382 of the Internal Revenue Code of 1986, as amended, which we refer to as the Code.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
In addition, we may, from time to time, seek to acquire or strategically invest in other complementary products, technologies, or businesses businesses, or repurchase outstanding shares of our common stock or our 0.25% convertible senior notes due 2026, which we refer to as the Notes. stock.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
Our indebtedness could limit the cash flow available for our operations operations, and expose the restrictive and financial covenants under our Credit Agreement could limit our operational flexibility, exposing us to risks that could adversely affect our business, operating results, and financial condition.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
In addition, regulators are increasingly focusing on we face evolving and sometimes conflicting regulatory requirements and stakeholder expectations concerning environmental, social, and governance matters and related disclosures.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 2, 2026 vs 10-K Feb 13, 2026
Additionally, implementing changes to business strategies could result in furloughs, layoffs, and reductions in force, such as our restructuring plan announced in October 2024, which we refer to as the Restructuring Plan. 2026 Restructuring.

Read it in the 10-Q at sec.govThe 10-K sentence

The first 24 of 42 are shown (at most 12 of each type).

Phrases used for the first time

Two-word phrases in Risk Factors of the 10-K filed Feb 13, 2026 that are in none of the 1 earlier 10-Ks stored, back to Feb 13, 2025

workforce solutions ×42upwork marketplace ×9contingent work ×4ai-related work ×3active customers ×2launched lifted ×2enterprise-focused subsidiary ×2subsidiary offering ×2offering broader ×2broader range ×2work solutions ×2large enterprises ×2client projects ×2platforms offerings ×2enterprise business’s ×2business’s managed ×2
Where each one is used
  • workforce solutions: •Customers circumvent our platforms and other workforce solutions, which adversely impacts our business.
  • upwork marketplace: To grow our business, we need to continue to establish and maintain relationships with third parties, such as staffing providers, software and technology vendors, and payment processing and disbursement providers. We also have several partnerships that enable us to integrate AI tools into the Upwork Marketplace...
  • contingent work: We continue to evolve our business strategy, offerings, and pricing model, as well as our sales, marketing, and brand positioning efforts. We continuously evaluate and revise our current offerings and pricing model and create and test additional offerings, pricing models, features, and services to serve our current...
  • ai-related work: We incorporate AI and machine learning technologies across our platforms, offerings, and internal operations and are making further investments in expanding our AI capabilities. In addition, GSV from AI-related work performed on the Upwork Marketplace has increased as demand for AI talent has grown in recent...
  • active customers: •Our growth depends on our ability to attract and retain a community of talent and clients, and the failure to maintain or grow our community of active customers in a cost-effective manner or at all could adversely impact our business, operating results, and financial condition.
  • launched lifted: We continue to evolve our business strategy, offerings, and pricing model, as well as our sales, marketing, and brand positioning efforts. We continuously evaluate and revise our current offerings and pricing model and create and test additional offerings, pricing models, features, and services to serve our current...
  • enterprise-focused subsidiary: We continue to evolve our business strategy, offerings, and pricing model, as well as our sales, marketing, and brand positioning efforts. We continuously evaluate and revise our current offerings and pricing model and create and test additional offerings, pricing models, features, and services to serve our current...
  • subsidiary offering: We continue to evolve our business strategy, offerings, and pricing model, as well as our sales, marketing, and brand positioning efforts. We continuously evaluate and revise our current offerings and pricing model and create and test additional offerings, pricing models, features, and services to serve our current...

The 10-K at sec.gov

Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.

What was taken out

8 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.

Across all companies
full-time employees relative to their use of independent contractors. We cannot predict the timing, strength, or duration of any economic slowdown, or any subsequent recovery generally. If the conditions in the general economy continue to deteriorate, our business, operating results, and financial condition could be adversely affected.
In the 10-K filed Feb 13, 2025
We expect that there will continue to be new laws, regulations, and industry standards concerning privacy, data protection, automated processing, and information security. For example, Europe’s General Data Protection Regulation, which we refer to as the GDPR, the UK General Data Protection Regulation, and Europe’s Digital
In the 10-K filed Feb 13, 2025
common stock from time to time in connection with a financing, an acquisition, investments, or otherwise. Any such issuances could result in substantial dilution to our existing stockholders and cause the market price of our common stock to decline.
In the 10-K filed Feb 13, 2025
We have experienced growth in a relatively short period of time and expect to invest in our growth in the future. However, our historical growth should not be considered indicative of our future performance. There can be no
In the 10-K filed Feb 13, 2025

Sources

Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.

Also

10-K change: what was reworded or cut, section by section.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/UPWK/export.csv") into a cell.

Next:10-K change
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.