Form 10-K for the Fiscal Year Ended December 31, 2020
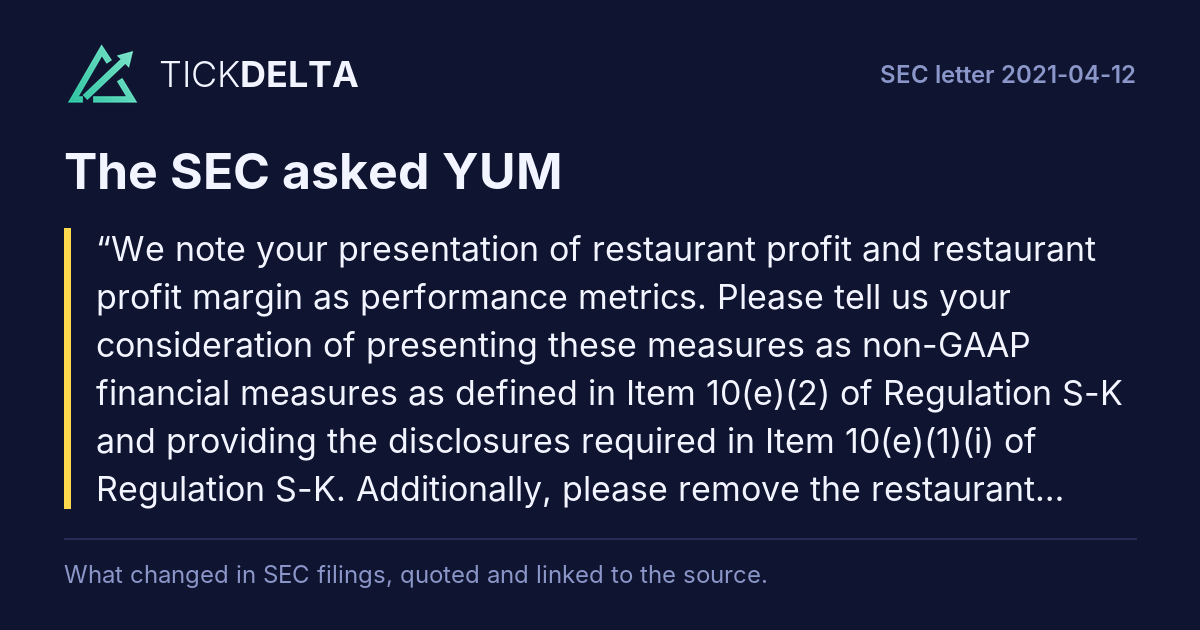
We note your presentation of restaurant profit and restaurant profit margin as performance metrics. Please tell us your consideration of presenting these measures as non-GAAP financial measures as defined in Item 10(e)(2) of Regulation S-K and providing the disclosures required in Item 10(e)(1)(i) of Regulation S-K.Rest of the question
Additionally, please remove the restaurant profit and restaurant margin % from the “GAAP Results” disclosure on page 35 of your Form 10-K.
While the Company’s predominate business model is as a franchisor, it does own and operate over 1,000 restaurants. The amounts of revenues and profits earned by these restaurants are significant in relation to our total revenues and profits. The primary metrics we use to measure the profitability of our Company-owned restaurants are Company restaurant profit and Company restaurant margin as a percentage of sales.Read in the reply ↗Rest of the answer
Accordingly, we have historically provided these metrics in our SEC filings and other public disclosures.
Company restaurant profit is calculated as the difference between Company sales and Company restaurant expenses, both of which are line items presented on the face of our Consolidated Statements of Income. Company restaurant margin as a percentage of sales is calculated as Company restaurant profit divided by Company sales.
Company sales are recognized as food items are sold in our Company-owned restaurants, which is when our obligation to perform is satisfied. Company restaurant expenses include all expenses to operate that Company restaurant, including cost of food and paper, cost of store-level labor, rent, depreciation and amortization of restaurant-level assets and advertising expenses incurred by and on behalf of that Company restaurant. As such, we believe that both Company sales and Company restaurant expenses represent amounts computed in accordance with Generally Accepted Accounting Principles (“GAAP”).
Yum! Brands, Inc.
Item 10(e)(4) of Regulation S-K states that, for purposes of Item 10(e), non-GAAP financial measures exclude operating and other statistical measures; and ratios or statistical measures calculated using exclusively one or both of (i) financial measures calculated in accordance with GAAP, and (ii) operating measures or other measures that are not non-GAAP financial measures. Additionally, the SEC’s 2003 Final Rule, “Conditions for Use of Non-GAAP Financial Measures” states, “An example of a ratio that would not be a non-GAAP financial measure would be a measure of operating margin that is calculated by dividing revenues into operating income, where both revenue and operating income are calculated in accordance with GAAP.”
Consistent with the SEC guidance referenced, we do not believe either Company restaurant profit or Company restaurant margin as a percentage of sales, both of which are calculated using exclusively GAAP measures, represent non-GAAP measures. Company restaurant profit is calculated exclusively using GAAP measures (by subtracting Company restaurant expenses from Company sales), while Company restaurant margin is calculated by dividing this resulting Company restaurant profit amount by Company sales (also, a GAAP measure).
While both are calculated using financial measures calculated in accordance with GAAP, we will remove Restaurant profit and Restaurant margin % from the GAAP Results section of our future filings, beginning with our Quarterly Report on Form 10-Q to be filed for the period ended March 31, 2021. Instead, we will include such amounts in the Performance Metrics section of our future filings and continue to provide all disclosures as required in the SEC’s “Commission Guidance on Management’s Discussion and Analysis of Financial Condition” issued in January, 2020. In addition, to provide additional clarity to investors regarding the way in which Company restaurant profit is calculated, in our future filings, beginning with our Quarterly Report on Form 10-Q to be filed for the period ended March 31, 2021, we intend to expand the discussion of Company restaurant profit in our Management’s Discussion and Analysis of Financial Condition and Results of Operations as follows (with new proposed language underlined):
• Company restaurant profit (“Restaurant profit”) is defined as Company sales less all expenses incurred directly by our Company-owned restaurants in generating Company sales, including cost of food and paper, cost of store-level labor, rent, depreciation and amortization of restaurant-level assets and advertising expenses incurred by and on behalf of that Company restaurant. Company restaurant margin as a percentage of sales is defined as Restaurant profit divided by Company sales. Restaurant profit is useful to investors as it provides a measure of profitability for our Company-owned restaurants.
First report after the company's reply of 2021-04-22: 10-Q filed 2021-05-05 ↗, against the 10-Q filed 2020-11-05 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: company letter, 2021-05-07, closing letter, 2021-05-17