Rest of the answer
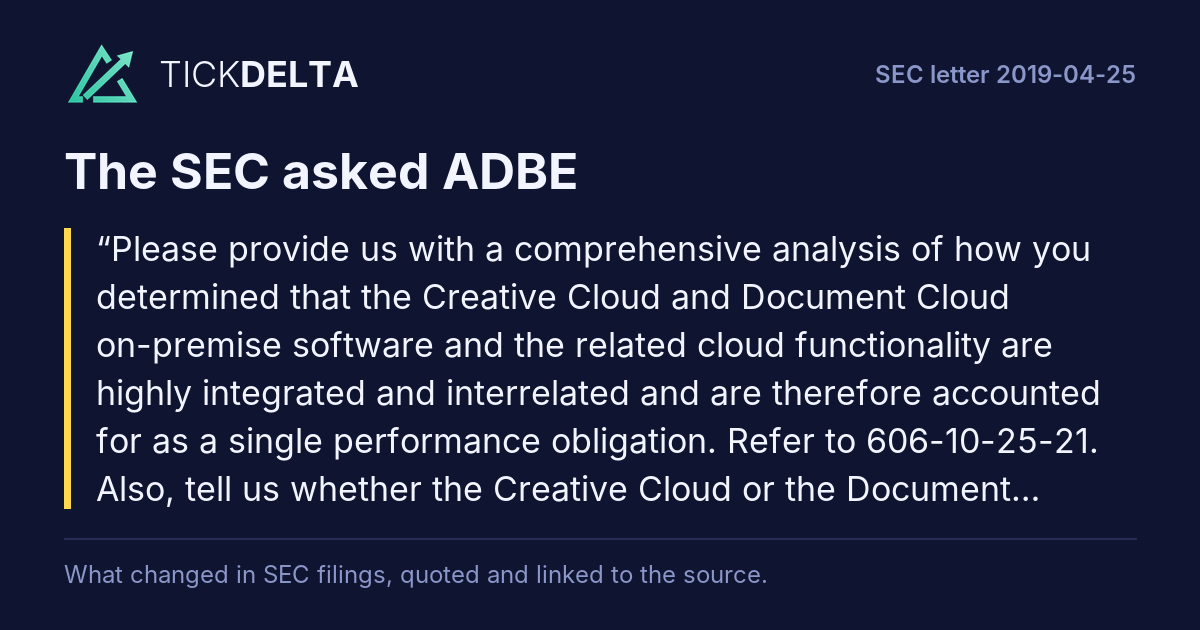
customer downloading some of the entity’s software for use on desktop and mobile devices and accessing other software and features/functionality only in the cloud (i.e., only on a hosted basis, without the right to take possession of the underlying software code). Therefore, when evaluating the accounting question, we considered all the guidance on distinct goods or services in ASC 606 (i.e., the guidance in paragraphs 606-10-25-19 through 25-22 and the relevant examples in ASC section 606-10-55), as well as the discussion in the Basis for Conclusions ("BC") to Accounting Standards Update ("ASU") No. 2016-10, which helps to explain the intent of the Financial Accounting Standards Board ("FASB" or the "Board") with respect to application of the ‘separately identifiable’ principle in paragraph 606-10-25-21. Paragraphs BC29 and BC33(b) are particularly relevant to the evaluation of our Creative Cloud and Document Cloud solutions because both address fundamental aspects about how an entity should consider whether two or more promises to transfer goods or services are ‘separately identifiable’ in the context of the contract with the customer, and thus should be accounted for separately, or represent a combined element that is comprised of individual goods or services promised in a contract that should be accounted for together.
In addition, while not authoritative, we have considered the guidance developed by the American Institute of Certified Public Accountants ("AICPA") Software Entities Revenue Recognition Task Force (and approved by the Financial Reporting Executive Committee) provided in the AICPA Revenue Recognition Guide (published June 2017), paragraphs 9.2.10 - 9.2.15 relating to Determining Whether Software Intellectual Property is Distinct in Cloud Computing Arrangements. This guidance is directly relevant to Adobe’s Creative Cloud and Document Cloud solutions in that it addresses hybrid offerings that include both on-premise (or on-device) software and hosted (or cloud-based) functionalities.
I. Creative Cloud
Business Model and Evolution to the Cloud
Adobe Creative Cloud ("CC") was first announced in October 2011 and was launched in 2012. In May 2013, we announced that future versions of the Creative Suite (the purely on-premise precursor to CC) would no longer be available for purchase and that all future updates and upgrades to our solutions would only be available in Creative Cloud. Prior to the launch of Creative Cloud, the Company offered individual products and software suites containing multiple products with a perpetual software license.
As discussed in Appendix A, Section I.B (Migration to the Cloud), the transition from Creative Suite and on-premise-only offerings to Creative Cloud was part of a long-term vision about the future of how creative professionals work. That transition, and the continued evolution of Creative Cloud was, and continues to be, driven in large part by the needs and demands of those customers that now subscribe to our offering. Our vision for Creative Cloud remains that of a highly integrated set of desktop, mobile, and cloud-based tools, developed to work together to meet the creative needs of our customers in the collaborative, mobile manner they have demanded.
Adobe Creative Cloud is a subscription, generally offered for a oneto three-year term, which integrates Adobe’s desktop and mobile creative tools with cloud-delivered services and functionalities. Adobe Creative Cloud permits customers to access these tools and cloud-based services and functionalities seamlessly across desktop, web, and mobile devices (including smartphones and tablets). Creative Cloud addresses the needs of creative professionals
BY ADOBE INC.: ADBE - 03 including graphic designers, production artists, web designers and developers, experience and user interface designers, videographers, motion graphic artists, prepress professionals, video game developers, mobile application developers, students, and administrators. Customers rely on our solutions for publishing, web design and development, video and animation production, mobile app and gaming development, and document creation and collaboration.
Analysis
Is the promise to transfer Creative Cloud on-premise and on-device licenses separately identifiable from the promise to provide access to the cloud-based features and functionalities to which the customer has access as part of Creative Cloud?
Cloud-based features that are integral to the promise of the Creative Cloud solution and that work together with the on-premise/on-device software to create significant features and functionalities
There are significant features and functionalities of the Creative Cloud solution that can be accessed only when connected to the Adobe cloud and rely upon interaction between the on-premise/on-device software and the cloud-based (i.e., hosted) features of the solution. These cloud-based features are integral to delivering the solution we promise and our customers expect, as we describe below.
Appendix A outlines these interrelated on-premise/on-device and cloud-based features and functionalities in further detail, but the following are examples of functionality which are only possible through Creative Cloud's cloud-enabled services and features' interaction with the on-premise/on-device software:
•
Cloud-Based Workflow (Creative Cloud Libraries and Team Projects) - Users can access and work with their created content on any device. Customers are able to sync and access their fonts across applications, and can also create and share “Creative Cloud Libraries” across their teams and organizations, which allow for seamless access to shared graphics, branding elements, fonts, and other creative assets (“creative asset” refers to something like a design, a logo, an image, video, or a character) necessary for a productive workflow across teams, applications, and devices. Assets such as videos, pictures, web pages, illustrations, print layouts, color palettes, brushes, and shapes created on a desktop or mobile device are automatically and immediately available to other tools within Creative Cloud and on any device. The result is the ability to leverage workflows that did not exist prior to the integration of cloud-based functionality with on-premise/on-device tools and increased efficiency. Team Projects cloud functionality allows multiple users to work on a project simultaneously, managing conflicts and version control seamlessly.
Linked Assets - The Adobe cloud enables automatic propagation of changes to creative assets (via Creative Cloud Libraries). When an asset is placed in a document, a reference/digital link to the original asset is embedded within the asset. When the asset is updated by a user on his/her desktop or mobile device, notifications are sent to the apps and synced across the cloud to every place where that asset is used. Prior to the availability of Creative Cloud, this process would have involved multiple creative professionals downloading files manually either through email or a central server and changes would not be replicated to other documents (i.e., they would need to be later merged). An individual would have to manually update the asset across all places that asset is used and repeat this process each time an edit is made. When this process is considered in the context of a complex project worked on in multi-device environment and a development team working worldwide and across time zones, these challenges are significant. It is important to note that we are not just describing a productivity gain - this is how our customers expect to be able to work and this automatic propagation is a cloud-enabled functionality of the Creative Cloud. Customers regularly work on projects which involve significant numbers of creative assets across many different projects and with many different teams. Being able to work seamlessly across these assets is a core function and expectation of the solution, not simply an added benefit.
Cloud-based Content Intelligence Using Artificial Intelligence ("AI") and Machine Learning - Recognizing what is contained in a creative asset (e.g., photo, video, illustration) at a precise level and assigning relevant tags (key words) to make intelligent recommendations when searching for similar content. This includes features such as understanding that a component of a photograph is (for example) a tree, a beach, or a person as well as understanding context, such as whether the people are a family, whether they are happy, the composition of the photograph, depth of field, and font recognition (recognizing a font from a creative asset and recommending
BY ADOBE INC.: ADBE - 04 similar fonts, even from handwriting), which significantly enhance the process of editing creative assets. Customers can utilize these features only when using the on-premise/on-device software while connected to the Adobe cloud.
Automatic cloud “rendering” of a design to multiple mediums (e.g., a vector graphic suitable for a print brochure, a high-resolution bitmap to be used in a web page displayed on a high-resolution monitor, and a low-resolution bitmap to be used in a mobile app) without having to create different versions of the creative asset. The rendering process of the data occurs in the Adobe cloud, using its computing power together with the design created using the on-premise/on-device software. Rendering refers to the different formatting and/or coding that is required to publish a properly-formatted design in different mediums, and must be undertaken as a separate task for each medium by the creative professional if they were to undertake the design task without Creative Cloud’s cloud-based features. Another application of this functionality is that assets are “dynamically created” in the cloud as needed, which allows users on mobile devices to make edits to large assets without downloading the full resolution asset, but full fidelity is maintained in the asset and the edits are made to the full resolution version of the asset - processing in the cloud allows this functionality to take place, providing clear benefits for working on mobile devices and in bandwidth-limited scenarios and enables workflows not possible with a purely on-premise or on-device solution.
The nature of our promise to our Creative Cloud customers includes not only what design tasks can be completed, but also how those design tasks can be completed. Being able to work seamlessly across these assets is a core expectation of the solution, not simply a “bonus feature” or a “nice-to-have,” and this promise is only fulfilled by the combination of on-premise, on-device, and cloud functionality.
That is, not only does a customer purchase the Creative Cloud solution to enable him/her to undertake and complete design tasks, that customer expects, in no small measure because of the promises we make in our substantial published marketing materials, that he/she will experience defined features and functionalities and realize measurable efficiencies from acquiring the solution. Creative Cloud customers’ “intended benefit” (see BC33(b) of ASU 2016-10) from the contract, therefore, includes access to cutting-edge features and functionalities and the realization of promised efficiencies in his/her regular design tasks that result only from interaction of the on-premise/on-device software with each other and with software and services that are only accessible through the Adobe cloud (i.e., on a hosted basis).
In the application of ASC 606, we noted that while customers can obtain benefit from many of the creative licenses on their own, the design tasks most of our customers undertake use several of the tools that, only when used together and with key cloud-based features, provide the combined functionality necessary for the customer to complete their design tasks in the manner and timeframe required. Therefore, consistent with the principle in paragraph 606-10-25-21, the licenses to the individual on-premise (desktop) and on-device (mobile) software tools represent inputs to the Creative Cloud solution that permit the customer to complete design tasks of the nature described throughout our response. The preceding topic is discussed in additional detail in Appendix A.
Therefore, consistent with the FASB’s discussion of its intent with respect to the ‘separately identifiable’ principle in paragraph 606-10-25-21 that is included in paragraphs BC29 and BC33(b) of ASU 2016-10, and also consistent with the factors included in Example 9.2.3 of the AICPA Revenue Recognition Guide, the combination of the on-premise/on-device software licenses and the cloud-based features result in a combined, integrated functionality through the Creative Cloud solution that is more than simply the sum of two or more independent goods or services purchased in the same contract, and the customer’s ability to derive its intended benefit from the contract depends on Adobe both (1) transferring the on-premise/on-device software licenses and (2) providing access to the cloud-based features and functionalities throughout the subscription period. Consequently, the nature of Adobe’s promise, within the context of the contract, is to provide its customers with access to the integrated Creative Cloud solution, comprised of the on-premise/on-device software licenses and the cloud-based features, rather than to provide the customer with a package of on-premise/on-device software licenses and separate cloud-based services.
Conclusion to the Accounting Considerations
Based on our application of the relevant accounting guidance and the analysis above, our conclusion is that the multiple on-premise/on-device software licenses and the cloud-based features and functionalities that comprise the Adobe Creative Cloud solution constitute a single performance obligation that should be recognized over the subscription period as the customer consumes and receives benefit from its access to the solution.
BY ADOBE INC.: ADBE - 05
II. Document Cloud
Adobe Document Cloud ("DC") is a portable document format ("PDF") solution which includes on-premise, on-device, and cloud-hosted features and functionality that allow users to create, convert, edit, sign, send, and manage documents across devices and teams. PDF, the file format underlying Document Cloud, is made freely available to all by Adobe, who created the file format. As such, tools such as our Acrobat Reader (document viewing only) and minimal document storage are available to all (including non-customers) to facilitate the ubiquity of “viewing” PDFs everywhere.
Document Cloud was launched in April 2015. In addition to Document Cloud, we sell a purely on-premise, perpetual license to Adobe Acrobat (Standard and Pro) (launched in June 1993), which is a desktop-only PDF tool and does not include any cloud-hosted features or functionality. Adobe Acrobat is the desktop software component of Document Cloud. When the Company announced Document Cloud, it did so alongside the existing Acrobat product (i.e., it launched DC while still offering Acrobat) as “a modern way to manage critical documents at home, in the office, and across devices [and] address the waste and inefficiency associated with document processes,” and provide our customers with a holistic document solution that enables them to work seamlessly across devices, teams, and locations. http://news.adobe.com/press-release/adobe-introduces-document-cloud
Mobile Acrobat Reader functionality is combined with cloud features by a subscription to Document Cloud, as described in the workflow examples below and in Appendix B (e.g., when we describe editing, re-ordering, PDF creation on mobile, etc. which are all only available on mobile when subscribing to DC). Unless we specifically state otherwise, when we describe what is possible “on-premise” throughout this letter, we are referring to both “on-premise” (desktop machine) and “on-device” (mobile).
Document Cloud is sold as a “Standard” or “Pro” offering and there are feature differences between the two offerings; these include differences within both the on-premise Acrobat software and the cloud-based features of the offering. These feature differences do not change the workflows described throughout this document, but the Pro version of DC adds functionality such as the ability to have computers read PDFs aloud on Mac OS X, create and validate PDFs based on WCAG (web content accessibility guidelines) and PDF U/A (universal accessibility) accessibility standards, or create a “compare” report between two PDFs, match an exact font from a scanned document, create a PDF from the Microsoft Word “ribbon” on Mac OS X, and rearrange pages of a PDF on an iPad. We do not believe any of these features impact our analysis throughout this document (i.e., we do not believe the additional functionalities present in the Pro version suggest only the Pro version is a single hybrid cloud performance obligation), as all workflows we describe are possible with both the Standard and Pro versions of the DC solution.
As discussed in Appendix B, Section I.B (Migration to the Cloud), the transition from Acrobat and on-premise-only offerings to Document Cloud was part of a long-term vision about the future of how people use and interact with documents. That transition, and the continued evolution of Document Cloud was, and continues to be, driven in large part by the needs and demands of those customers that now subscribe to our offering. In Document Cloud, Adobe has delivered a highly-integrated set of desktop, mobile, and cloud-based tools, developed to work together to meet the needs of our customers in the collaborative, mobile-enabled manner they expect.
We market and sell Document Cloud as an end-to-end document solution that enables our customers to work in the manner they expect - anywhere, at any time, on any device, across teams - manage documents throughout an organization and with their customers, and have a fully functional hosted signature service built into their workflow.
Our core document offering to customers is a subscription, generally offered for a oneto three-year term, which integrates Adobe’s desktop and mobile document tools (e.g., Acrobat, Fill and Sign, Scan) with cloud-delivered services and functionalities. Adobe Document Cloud permits customers to access these tools and cloud-based services and functionalities across desktop, web, and mobile devices (including smartphones and tablets). Document Cloud addresses the needs of anyone who works with documents and forms (physical and digital) on a regular basis and is used by finance, accounting, marketing, IT, HR, and strategy groups to name a few. Document Cloud allows users to easily create, edit, collaborate on, send, track, and sign documents across devices and teams. Customers rely on our solutions to work in a secure, standardized way with documents utilizing the PDF file format as the basis for their workflow. Users utilize our solutions to digitize paper-based workflows, reduce re-work by standardizing on PDF, use mobile capabilities and syncing to work from anywhere at any time, track documents across the Adobe Document
BY ADOBE INC.: ADBE - 06
Cloud, and increase the ease, speed, and security of the document signature process, facilitating workflows only available to Document Cloud subscribers.
Is the promise to transfer Document Cloud on-premise and on-device licenses (Acrobat and Acrobat Mobile) separately identifiable from the promise to provide access to the cloud-based features and functionalities to which the customer has access as part of Document Cloud?
Cloud-based features that are integral to the promise of the Document Cloud solution and that work together with the on-premise/on-device software to create significant features and functionalities
There are significant features and functionalities of the Document Cloud solution that can be accessed only when connected to the Adobe cloud and rely upon interaction between the on-premise/on-device software and the cloud-based (i.e., hosted) features of the solution. These cloud-based features are integral to delivering the solution we promise and our customers expect, as we describe below.
Appendix B outlines these interrelated on-premise/on-device and cloud-based features and functionalities in further detail, but the following are examples of functionality which are only possible through Document Cloud's cloud-enabled services and features' interaction with the on-premise/on-device software:
Cloud-based document review workflow, which allows teams (i.e., multiple team members) to work on and review documents simultaneously, managing permissions, comments, notifications, versioning, and edits all within the Adobe cloud and fully integrated with Acrobat. For example, one user may be a manager and the only person with authority to mark a document as “approved,” and the review workflow system understands these types of permission levels and team roles and enforces them on the document from within the Adobe cloud. When multiple people are working on the same document at the same time within their respective on-premise and on-device tools, these types of permissions allow for complex review and control processes where users can edit, review, and comment simultaneously and review workflows can be enforced such that each team member has a specific role and permissions are controlled across desktop and mobile.
Another example of functionality only enabled by the cloud is that reviewers can “mention” a specific individual in their comment in the document within the desktop tool. Because the desktop and mobile tools are integrated with the cloud services and because the cloud services know who all the users are and their roles on the team, this “mention” automatically triggers notification to that individual, who can then reply directly to the notification email. Their email response (from anywhere) will be ingested into the document via the cloud as a response to the comment, all facilitated by the Adobe cloud. Cloud-based review dashboards are available for review initiators which allow them to see the status of all documents currently in review, who has modified them, who has reviewed them, etc.
Reviewers are connected to the cloud review system such that notifications they receive are automatically tailored to their role and their interactions with the document. For example, the system knows and tailors notifications based on which version the user last opened, whether they’ve started their review, or whether they’ve left any comments. All this functionality resides in the cloud and is integrated with the user interface for desktop, mobile, and web. This type of review workflow facilitates seamless review, approval, and signature workflows throughout an organization, cloud-based workflow assignment and tracking (based on roles and responsibilities), and is designed cloud-first with the underlying processes and workflows being focused on a completely mobile and connected offering from the beginning.
This functionality allows teams to be simultaneously working on and editing documents, with a clear and auditable workflow, facilitated by the Adobe cloud. All these features described are not available with on-premise Acrobat or on-device Acrobat only. For example, without the cloud-based features, the review process would be linear. Everyone within a given team would have to edit one at a time and either combine all the edits together manually or the document would have to progress from one person to the next, each adding their own comments and changes. The document would be manually tracked throughout the review process and the individual with final review authority would review, provide comments, and the document would likely restart the process of going through the review chain again. The cloud-based features significantly transform what we are able to deliver to our customers.
BY ADOBE INC.: ADBE - 07
Searchable, editable, sharable documents - Document Cloud, utilizing Adobe cloud machine-learning technology (Sensei), can leverage artificial intelligence in a variety of ways. One example is using optical character recognition ("OCR") and machine learning to identify and classify words, paragraphs, lists, tables, form fields, and figures. This information can be used for a variety of purposes, including with forms (discussed below) or to insert supplemental rich data such as metadata and tags into documents that previously had none, from within the on-premise tool, enabled by the Adobe cloud-based features. PDF itself is a flat file format - so Acrobat on its own does not understand that a list of items is a list or that a paragraph is a paragraph and having a machine correctly identify these objects is a difficult and historically error-prone process.
Certain government and educational institutions require by law that all digital documents be tagged with metadata for accessibility. Sensei, as part of Document Cloud, is an Adobe cloud-based service, integrated with the on-premise and on-device tools, which is used to understand context within a document and enhance the document based on this understanding with tags and metadata. This metadata may be used for a wide variety of tasks, including use on accessibility devices such as screen readers for visually impaired users or to search for specific content within thousands of documents.
Another example of how Sensei machine learning can be utilized is to understand document context and insert dynamic web content automatically or provide cogent summaries of a document in plain English. Sensei does this by leveraging the significant document and imaging data available to Adobe through our products and in the cloud.
Document Cloud has significant features and functionality (such as Sensei) which are not available in the on-premise and on-device only offerings, Acrobat. Without this Sensei functionality, individuals would (and do) have to, instead, manually examine a document and add tags and metadata to every object, paragraph, image, list, caption, etc. individually. For example, users of the on-premise Acrobat application have the ability to manually tag documents on a character-by-character basis, but this tagging process is error-prone because it does not have contextual and machine-learning algorithms to understand what is being tagged. There is no way for the on-premise application to understand something as simple as whether text is a caption for an image or body text.
The ability to harness this Adobe cloud-based functionality for use with the on-premise/on-device software results in significant efficiencies compared to software use only and evidences the cloud-based Sensei and the on-premise and on-device software (Acrobat and Acrobat Mobile) working together to produce a properly tagged document. In addition to efficiencies gained in the process of tagging the documents, the ability to locate information easily within large caches of documents becomes significantly more efficient.
Cloud-based Natural Language Processing ("NLP" - a field of artificial intelligence) looks at text and automatically recognizes grammar, syntax and semantics to derive understanding from it, recognizing the elements of a form. Without this type of functionality, mobile form completion of the type described below would not be possible. The ability to have accurate, automated machine identification of specific objects in a document (images, captions, etc.) and dynamically provide summaries through understanding content is a significant step forward in the ability to work with documents for our customers and is only available in the Adobe cloud and with subscription to DC.
One example is a magazine article which contains images, text, captions, quotes, etc. that are placed throughout the article in a non-uniform way. The user needs to be able to accurately identify, catalogue, and search the components of the article (as well as hundreds of others, each with their own unique formatting) - Natural Language Processing allows DC to perform this analysis, based on analysis of thousands of other documents in the cloud.
To recreate this workflow without Adobe cloud functionality, users would have to wait until they could reach a physical scanner (because the use of their phone or tablet to ingest a picture and utilize the cloud to convert to PDF would not be available), manually fill out the form, scan the form, manually tag character-by-character specific sections of a document, manually identify form fields and enable them, and then email it to the desired recipients. However, at this point the user would also lose all visibility into whether the intended recipient received or opened the document (no Send and Track) and what comments have been made by the customer. Essentially, the workflow as described would not be possible in the manner described above. This workflow again describes a process that involves interaction between the on-premise software (Acrobat), on-device software (Acrobat mobile), and the cloud-based features.
BY ADOBE INC.: ADBE - 08
Document Cloud, utilizing functionality only available in the Adobe cloud, learns the structure of fillable forms (i.e., where form fields are located, what the labels are, the types and order of fields) to make filling out forms easier. Because this technology is facilitated by the Adobe cloud, it (and the other technology described here) extends to mobile devices as well. For example, in Adobe Fill & Sign, we use advanced image processing technology to identify form fields from a scanned paper document to make it easy to input personalized information like names and addresses, and sign the document. A user can take a picture of a paper document using their mobile device and Document Cloud will convert the document to a PDF, analyze the document, and identify fillable fields (e.g., name, address, date of birth, etc.). Without Document Cloud, the user would have to find a scanner and scan the document that they would like to turn into a form and email the document to themselves. At this point, they would manually identify the fields in the document and insert field boxes into the document using Acrobat and then fill in the fields. There would be no utilization of Sensei functionality to identify the fields, no ability to ingest the document anywhere (utilizing mobile devices), and the user’s personal information would not be accessible from any device, allowing them to fill fields by just tapping from a list of cloud-synced information. The files could not be worked on by other team members simultaneously. Once the file was sent to others via email, all visibility into the status of the document would be lost.
Please refer to Appendix B for additional discussion of these cloud-based features and others.
Features available only when connected to the Adobe cloud significantly change the customer’s ability to work with and create documents when compared with the use of the on-premise/on-device software on its own (i.e., without access to the cloud-based features).
The nature of our promise to our Document Cloud customers includes not only what can be accomplished with a document workflow, but also how those tasks can be completed. That is, not only does a customer purchase the Document Cloud solution to enable him/her to undertake and complete specific tasks, that customer expects that he/she will have access to specified features and functionalities and realize measurable efficiencies from acquiring the solution. Document Cloud customers’ “intended benefit” from the contract (as per BC33(b) in ASU 2016-10) therefore includes access to cutting-edge features and functionalities and the realization of promised efficiencies in his/her regular tasks that result only from interaction of the on-premise/on-device software with software and services that are only accessible through the Adobe Document Cloud (i.e., on a hosted basis).
Therefore, consistent with the FASB’s discussion of its intent with respect to the ‘separately identifiable’ principle in paragraph 606-10-25-21 that is included in paragraphs BC29 and BC33(b) of ASU 2016-10, and also consistent with the discussion in AICPA Revenue Recognition Guide, paragraphs 9.2.10 - 9.2.15, the combination of the on-premise/on-device software licenses and the cloud-based features result in a combined, integrated functionality through the Document Cloud solution that is more than simply the sum of two or more independent goods or services purchased in the same contract, and the customer’s ability to derive its intended benefit from the contract depends on Adobe both (1) transferring the on-premise/on-device software licenses and (2) providing access to the cloud-based features and functionalities throughout the subscription period. Consequently, the nature of Adobe’s promise, within the context of the contract, is to provide its customers with access to the integrated Document Cloud solution, comprised of the on-premise/on-device software licenses and the cloud-based features, rather than to provide the customer with a package of on-premise/on-device software licenses and separate cloud-based services.
Based on our application of the relevant accounting guidance and the analysis above, our conclusion is that the on-premise/on-device software licenses (Acrobat and Acrobat Mobile) and the cloud-based features and functionalities that comprise the Adobe Document Cloud solution constitute a single performance obligation that should be recognized over the subscription period as the customer consumes and receives benefit from its access to the solution.
III. Non-Cloud Services Enabled Software
In limited circumstances, we sell without cloud services enabled and account for these sales as software licenses. Revenue associated with these sales for the quarters ended March 1, 2019 and March 2, 2018 represented approximately [***] and [***] of total revenue, respectively. We expect this revenue to continue to decrease as a proportion of our total revenue.
BY ADOBE INC.: ADBE - 09
* * *
Adobe further acknowledges that:
Adobe is responsible for the adequacy and accuracy of the disclosure in the filing;
Staff comments or changes to disclosure in response to Staff comments do not foreclose the Commission from taking any action with respect to the filing; and
Adobe may not assert Staff comments as a defense in any proceeding initiated by the Commission or any person under the federal securities laws of the United States.