Paragraph 63 · 49% changed
Every version of it
Screener
/
SEC EDGAR
/CIK 0001287750
/10-K filed Feb 4, 2026, compared with Feb 5, 2025
/Numbers from the XBRL of the 10-Ks
The 10-K against last year's
207 changes: 37 added, 24 removed, 141 reworded, 5 quiet changes
10-K Feb 4, 2026 vs Feb 5, 2025
Risk Factors
14.8%
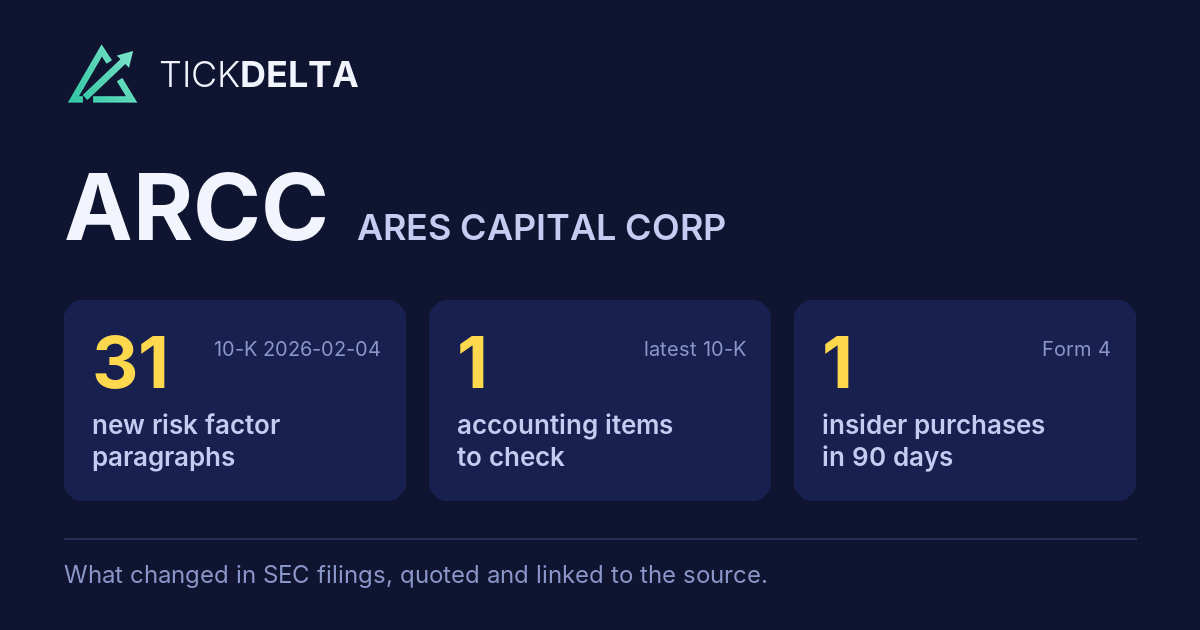
of the text changed · 25,536 words now · 31 new paragraphs, 14 gone
MD&A
14.7%
of the text changed · 15,633 words now · 6 new paragraphs, 10 gone
Legal Proceedings
0.7%
of the text changed · 537 words now
Accounting Policies
9.6%
of the text changed · 3,467 words now
10-K 0001287750-26-000006 (Feb 4, 2026) vs 10-K 0001287750-25-000007 (Feb 5, 2025)
Every paragraph, and how much of it changed
One bar per paragraph, in the order of the 10-K. Height and colour show the share of its words not in the closest paragraph a year earlier; the tallest bars are new paragraphs.
Risk Factors
268 paragraphs · 31 new · 66 reworded · 14 gone · 10-K Feb 4, 2026 against Feb 5, 2025
New paragraph
Reworded (5% of its words or more)
Same or nearly
Paragraph 107 · 46% changed
Every version of it
Paragraph 236 · 45% changed
Every version of it
Paragraph 53 · 44% changed
Every version of it
Paragraph 73 · 44% changed
Every version of it
We rely on the Co-Investment Exemptive Order granted to us, our investment adviser and certain of its our affiliates by the SEC that allows us to engage in co-investment transactions with other affiliated funds entities managed by our investment adviser, subject to certain terms conditions and conditions. However, while the terms requirements. As a result of investments permitted by the Co-Investment Exemptive Order require that we Order, there could be given the opportunity to participate significant overlap in certain transactions originated by our investment adviser portfolio and the investment portfolios of affiliated entities that have an investment objective similar to ours and can rely on the Co-Investment Exemptive Order. We may also otherwise co-invest with funds managed by Ares or any of its downstream affiliates, we ultimately may not participate in those transactions. In addition, based on guidelines approved by our board of directors, we may not see certain transactions originated by subject to compliance with existing regulatory guidance, applicable regulations and our investment adviser or its affiliates. This also may limit the scope of investment opportunities that may otherwise be available to us. adviser’s allocation policy.
Paragraph 140 · 41% changed
Every version of it
Paragraph 106 · 40% changed
Every version of it
Paragraph 256 · 40% changed
Every version of it
In addition, cybersecurity has become is a priority for regulators in the U.S. and around the world. In February 2022, the The SEC proposed, and subsequently delayed the adoption of, new has adopted rules related to cybersecurity risk management for registered investment advisers, registered investment companies and business development companies, as well as amendments to certain rules that govern investment adviser and fund disclosures. companies. In July 2023, addition, the SEC also adopted rules requiring requires public companies to disclose material cybersecurity incidents on Form 8-K and provide periodic disclosure of a registrant’s regarding their cybersecurity risk management, strategy, and governance in annual reports. The rules became effective beginning with annual reports for fiscal years ending on or after December 15, 2023 and beginning with Form 8-Ks on December 18, 2023. In May 2024, the SEC adopted amendments cybersecurity regulations as an amendment to Regulation S-P, which, beginning in S-P designed to establish a federal “minimum standard” for covered institutions to adopt an incident response program to govern their response to any unauthorized access of customer information. The adopted rule requires compliance as of December 2025, require 2025 and applies to us as it includes investment companies and SEC-registered registered investment advisers to adopt advisers. The amendments require implementation of written policies and procedures for to safeguard customer records and information by imposing notification requirements to affected individuals whose sensitive customer information was or is reasonably likely to have been accessed or used without authorization and other requirements, such as review of incident response programs to address unauthorized access to, or use of, customer information, including providing notice to certain individuals affected and having policies and procedures regarding compliance by any such incident. We will need to comply with this amended rule beginning December 2025. third-party service providers. With the SEC particularly focused on cybersecurity, we expect increased scrutiny of our and Ares’ policies and systems designed to manage cybersecurity risks and related disclosures. We also may face increased costs to comply with the new SEC rules, including Ares’ increased costs for cybersecurity training and management, a portion of which may be allocated to us. In addition, the SEC has indicated in recent periods that one of its examination priorities for the Office of Compliance Inspections and Examinations is to continue to examine cybersecurity procedures and controls, including testing the implementation of these procedures and controls.
Paragraph 63 · 49% changed
Every version of it
10-K Feb 5, 2025•Global economic, political and market conditions, including uncertainty about the financial stability of the United States, could have a significant adverse effect on our business, financial condition and results of operations.
10-K Feb 4, 2026
accelerate repayment under such indebtedness and thereby have a material adverse impact on our business, financial condition and results of operations.
Paragraph 107 · 46% changed
Every version of it
10-K Feb 5, 2025“Anti-ESG” sentiment has gained momentum across the U.S., with a growing number of states, federal agencies, the executive branch and Congress having enacted, proposed or indicated an intent to pursue “anti-ESG” policies, legislation or issued related legal opinions and engaged in related investigations and litigation. If investors subject to “anti-ESG” legislation view our investment adviser’s responsible investing or ESG practices as being in contradiction of such “anti-ESG” policies, legislation or legal opinions, such investors may not invest in us and it could negatively impact the price of our common stock. In addition, corporate diversity, equity and inclusion (“DEI”) practices have recently come under increasing scrutiny. For example, some advocacy groups and federal and state officials have asserted that the U.S. Supreme Court’s decision striking down race-based affirmative action in higher education in June 2023 should be analogized to private employment matters and private contract matters and several media campaigns and cases alleging discrimination based on such arguments have been initiated since the decision. Additionally, in January 2025, President Trump signed a number of Executive Orders focused on DEI, which indicate continued scrutiny of DEI initiatives and potential related investigations of certain private entities with respect to DEI initiatives, including publicly traded companies. If we do not successfully manage expectations across varied stakeholder interests, it could erode stakeholder trust, impact our reputation and constrain our investment opportunities. Such scrutiny of both ESG and DEI related practices could expose our investment adviser to the risk of litigation, investigations or challenges by federal or state authorities or result in reputational harm.
10-K Feb 4, 2026
Further, some groups and federal and state officials have asserted that the U.S. Supreme Court’s decision striking down race-based affirmative action in higher education in June 2023 should be analogized to private employment matters and private contract matters. Several media campaigns and cases alleging discrimination based on such arguments have been initiated since the decision and in January 2025, the Trump Administration signed a number of Executive Orders focused on DEI, which caution the private sector to end “illegal DEI discrimination and preferences” and preview upcoming compliance investigations of private entities with respect to DEI initiatives, including publicly traded companies. Agencies across the federal government, including the Department of Justice, the Federal Communications Commission, and the Equal Employment Opportunity Commission, have been focusing on DEI-related investigations and enforcement. It is uncertain how the interpretation, application, and enforcement of laws (including U.S. state and federal nondiscrimination laws), policies, and public sentiment related to DEI will evolve, and it may become increasingly challenging to establish global DEI-related policies and programs that meet the varied laws, policies, and norms of different jurisdictions. If we do not successfully manage
Paragraph 236 · 45% changed
Every version of it
10-K Feb 5, 2025•Global economic, political and market conditions, including uncertainty about the financial stability of the United States, could have a significant adverse effect on our business, financial condition and results of operations.
10-K Feb 4, 2026
Difficult market and political conditions may adversely affect our businesses in many ways, including by reducing the value or hampering the performance of our investments or reducing our ability to raise or deploy capital, each of which could have a significant adverse effect on our business, financial condition and results of operations.
Paragraph 53 · 44% changed
Every version of it
10-K Feb 5, 2025In order for us to cover our annual interest payments on our outstanding indebtedness at December 31, 2024, we must achieve annual returns on our December 31, 2024 total assets of at least 2.4%. The weighted average stated interest rate charged on our principal amount of outstanding indebtedness as of December 31, 2024 was 4.9%. We intend to continue borrowing under the Facilities in the future and we may increase the size of the Facilities, the Letter of Credit Facility or issue additional debt securities or other evidences of indebtedness (although there can be no assurance that we will be successful in doing so). See “Management’s Discussion and Analysis of Financial Condition and Results of Operations—Recent Developments,” as well as Note 16 to our consolidated financial statements for the year ended December 31, 2024 for a subsequent event relating to an additional issuance of unsecured notes. For more information on our indebtedness, see “Management’s Discussion and Analysis of Financial Condition and Results of Operations—Financial Condition, Liquidity and Capital Resources.” Our ability to service our debt depends largely on our financial performance and is subject to prevailing economic conditions and competitive pressures. The amount of leverage that we employ at any particular time will depend on our investment adviser’s and our board of directors’ assessments of market and other factors at the time of any proposed borrowing and is subject to our compliance with our asset coverage requirement following any such borrowing.
10-K Feb 4, 2026
and Capital Resources.” Our ability to service our debt depends largely on our financial performance and is subject to prevailing economic conditions and competitive pressures. The amount of leverage that we employ at any particular time will depend on our investment adviser’s and our board of directors’ assessments of market and other factors at the time of any proposed borrowing and is subject to our compliance with our asset coverage requirement following any such borrowing.
Paragraph 73 · 44% changed
Every version of it
10-K Feb 5, 2025
We rely on the Co-Investment Exemptive Order granted to us, our investment adviser and certain of its affiliates by the SEC that allows us to engage in co-investment transactions with other affiliated funds managed by our investment adviser, subject to certain terms and conditions. However, while the terms of the Co-Investment Exemptive Order require that we be given the opportunity to participate in certain transactions originated by our investment adviser or its affiliates, we ultimately may not participate in those transactions. In addition, based on guidelines approved by our board of directors, we may not see certain transactions originated by our investment adviser or its affiliates. This also may limit the scope of investment opportunities that may otherwise be available to us.
10-K Feb 4, 2026
We rely on the Co-Investment Exemptive Order granted to us, our investment adviser and certain of our affiliates by the SEC that allows us to engage in co-investment transactions with other affiliated entities managed by our investment adviser, subject to certain conditions and requirements. As a result of investments permitted by the Co-Investment Exemptive Order, there could be significant overlap in our investment portfolio and the investment portfolios of affiliated entities that have an investment objective similar to ours and can rely on the Co-Investment Exemptive Order. We may also otherwise co-invest with funds managed by Ares or any of its downstream affiliates, subject to compliance with existing regulatory guidance, applicable regulations and our investment adviser’s allocation policy.
Paragraph 140 · 41% changed
Every version of it
10-K Feb 5, 2025The current macroeconomic environment is characterized by labor shortages, strikes, work stoppages, labor disputes, supply chain disruptions and accidents, changing interest rates, persistent inflation, foreign currency exchange volatility, volatility in global capital markets and concerns over actual and potential tariffs and sanctions, inflation and persistent recession risk. The risks associated with our and our portfolio companies’ businesses are more severe during periods of economic slowdown or recession.
10-K Feb 4, 2026
In recent years, the macroeconomic environment has experienced uncertainty related to evolving tariff and trade policies, geopolitical tensions, inflationary pressures, labor market shortages and disputes, changes in interest rates, supply chain disruptions, foreign currency fluctuations, and periods of volatility in global capital markets. The risks associated with our and our portfolio companies’ businesses are more severe during periods of economic slowdown or recession.
Paragraph 106 · 40% changed
Every version of it
10-K Feb 5, 2025“Anti-ESG” sentiment has gained momentum across the U.S., with a growing number of states, federal agencies, the executive branch and Congress having enacted, proposed or indicated an intent to pursue “anti-ESG” policies, legislation or issued related legal opinions and engaged in related investigations and litigation. If investors subject to “anti-ESG” legislation view our investment adviser’s responsible investing or ESG practices as being in contradiction of such “anti-ESG” policies, legislation or legal opinions, such investors may not invest in us and it could negatively impact the price of our common stock. In addition, corporate diversity, equity and inclusion (“DEI”) practices have recently come under increasing scrutiny. For example, some advocacy groups and federal and state officials have asserted that the U.S. Supreme Court’s decision striking down race-based affirmative action in higher education in June 2023 should be analogized to private employment matters and private contract matters and several media campaigns and cases alleging discrimination based on such arguments have been initiated since the decision. Additionally, in January 2025, President Trump signed a number of Executive Orders focused on DEI, which indicate continued scrutiny of DEI initiatives and potential related investigations of certain private entities with respect to DEI initiatives, including publicly traded companies. If we do not successfully manage expectations across varied stakeholder interests, it could erode stakeholder trust, impact our reputation and constrain our investment opportunities. Such scrutiny of both ESG and DEI related practices could expose our investment adviser to the risk of litigation, investigations or challenges by federal or state authorities or result in reputational harm.
10-K Feb 4, 2026
Moreover, in recent years “anti-ESG” sentiment has gained momentum across the U.S., with several states, the executive branch and federal agencies, and Congress having proposed, enacted or indicated an intent to pursue “anti-ESG” policies, legislation or initiatives, issued related legal opinions and pursued related investigations and litigation. If investors subject to “anti-ESG” legislation view our investment adviser’s responsible investing or ESG practices as being in contradiction of such “anti-ESG” policies, legislation or legal opinions, such investors may not invest in us and it could negatively impact the price of our common stock. In addition, corporate diversity, equity and inclusion (“DEI”) practices have recently come under increasing scrutiny.
Paragraph 256 · 40% changed
Every version of it
10-K Feb 5, 2025
In addition, cybersecurity has become a priority for regulators in the U.S. and around the world. In February 2022, the SEC proposed, and subsequently delayed the adoption of, new rules related to cybersecurity risk management for registered investment advisers, registered investment companies and business development companies, as well as amendments to certain rules that govern investment adviser and fund disclosures. In July 2023, the SEC also adopted rules requiring public companies to disclose material cybersecurity incidents on Form 8-K and periodic disclosure of a registrant’s cybersecurity risk management, strategy, and governance in annual reports. The rules became effective beginning with annual reports for fiscal years ending on or after December 15, 2023 and beginning with Form 8-Ks on December 18, 2023. In May 2024, the SEC adopted amendments to Regulation S-P, which, beginning in December 2025, require investment companies and SEC-registered investment advisers to adopt written policies and procedures for incident response programs to address unauthorized access to, or use of, customer information, including providing notice to certain individuals affected by any such incident. We will need to comply with this amended rule beginning December 2025. With the SEC particularly focused on cybersecurity, we expect increased scrutiny of our and Ares’ policies and systems designed to manage cybersecurity risks and related disclosures.
10-K Feb 4, 2026
In addition, cybersecurity is a priority for regulators in the U.S. and around the world. The SEC has adopted rules related to cybersecurity risk management for registered investment advisers, registered investment companies and business development companies. In addition, the SEC requires public companies to disclose material cybersecurity incidents on Form 8-K and provide periodic disclosure regarding their cybersecurity risk management, strategy, and governance in annual reports. In May 2024, the SEC adopted cybersecurity regulations as an amendment to Regulation S-P designed to establish a federal “minimum standard” for covered institutions to adopt an incident response program to govern their response to any unauthorized access of customer information. The adopted rule requires compliance as of December 2025 and applies to us as it includes investment companies and registered investment advisers. The amendments require implementation of written policies and procedures to safeguard customer records and information by imposing notification requirements to affected individuals whose sensitive customer information was or is reasonably likely to have been accessed or used without authorization and other requirements, such as review of incident response programs and having policies and procedures regarding compliance by third-party service providers. With the SEC particularly focused on cybersecurity, we expect increased scrutiny of our and Ares’ policies and systems designed to manage cybersecurity risks and related disclosures. We also may face increased costs to comply with the new SEC rules, including Ares’ increased costs for cybersecurity training and management, a portion of which may be allocated to us. In addition, the SEC has indicated in recent periods that one of its examination priorities for the Office of Compliance Inspections and Examinations is to continue to examine cybersecurity procedures and controls, including testing the implementation of these procedures and controls.
MD&A
232 paragraphs · 6 new · 82 reworded · 10 gone · 10-K Feb 4, 2026 against Feb 5, 2025
New paragraph
Reworded (5% of its words or more)
Same or nearly
Paragraph 198 · 43% changed
Paragraph 161 · 40% changed
We are authorized under our stock repurchase program to purchase up to $1.0 billion in the aggregate of our outstanding common stock in the open market at certain thresholds below our net asset value per share, in accordance with the guidelines specified in Rule 10b-18 under the Securities Exchange Act of 1934, as amended (the “Exchange Act”). The timing, manner, price and amount of any share repurchases will be determined by us, in our sole discretion, based upon an evaluation of economic and market conditions, stock price, applicable legal and regulatory requirements and other factors. The stock repurchase program does not require us to repurchase any specific number of shares of common stock or any shares of common stock at all. Consequently, we cannot assure stockholders that any specific number of shares of common stock, if any, will be repurchased under the stock repurchase program. As of December 31, 2024, the expiration date of the stock repurchase program was February 15, 2025. The program may be suspended, extended, modified or discontinued at any time. As of December 31, 2024, there was $1.0 billion available for additional repurchases under the program.
Paragraph 204 · 36% changed
In June 2024, January 2026, we repaid in full the $900 million in aggregate principal amount outstanding of unsecured notes (the “June 2024 Notes”) January 2026 Notes upon their maturity. The June 2024 Notes maturity, which bore interest at a rate of 4.200% 3.875% per annum, payable semi-annually. annum.
Paragraph 26 · 35% changed
Paragraph 67 · 35% changed
(1)We have committed provided a commitment to fund up to $750 million and $500 million million, as of December 31, 2025 and 2024, respectively, to IHAM, the with availability of which is funding solely at our discretion.
Paragraph 170 · 35% changed
(5)Represents the aggregate principal amount outstanding, less unamortized debt issuance costs and the net unaccreted/amortized discount or premium recorded upon issuance. In March 2024, 2025 and July 2025, we repaid in full the 2024 Convertible March 2025 Notes (as and the July 2025 Notes (each as defined below) below), respectively, upon their maturity. In June 2024, we repaid in full See “Recent Developments,” as well as Note 16 to our consolidated financial statements for the June 2024 year ended December 31, 2025 for subsequent events relating to the January 2026 Notes (as defined below) upon their maturity. and an additional issuance of unsecured notes.
Paragraph 14 · 33% changed
•the impact of supply chain constraints global health crises on our or our portfolio companies companies’ business and the U.S. and global economy;
Paragraph 114 · 32% changed
Paragraph 198 · 43% changed
10-K Feb 5, 2025(1)The effective stated interest rates of the January 2027 Notes, the March 2029 Notes and the July 2029 Notes include the impact of interest rate swaps.
10-K Feb 4, 2026
(1)In connection with the issuances of the January 2031 Notes and the March 2032 Notes, we entered into forward-starting interest rate swaps with an effective date of July 15, 2026 and January 8, 2026, respectively.
Paragraph 161 · 40% changed
10-K Feb 5, 2025
We are authorized under our stock repurchase program to purchase up to $1.0 billion in the aggregate of our outstanding common stock in the open market at certain thresholds below our net asset value per share, in accordance with the guidelines specified in Rule 10b-18 under the Securities Exchange Act of 1934, as amended (the “Exchange Act”). The timing, manner, price and amount of any share repurchases will be determined by us, in our sole discretion, based upon an evaluation of economic and market conditions, stock price, applicable legal and regulatory requirements and other factors. The stock repurchase program does not require us to repurchase any specific number of shares of common stock or any shares of common stock at all. Consequently, we cannot assure stockholders that any specific number of shares of common stock, if any, will be repurchased under the stock repurchase program. As of December 31, 2024, the expiration date of the stock repurchase program was February 15, 2025. The program may be suspended, extended, modified or discontinued at any time. As of December 31, 2024, there was $1.0 billion available for additional repurchases under the program.
10-K Feb 4, 2026
We are authorized under our stock repurchase program to purchase up to $1.0 billion in the aggregate of our outstanding common stock in the open market at certain thresholds below our net asset value per share, in accordance with the guidelines specified in Rule 10b-18 under the Securities Exchange Act of 1934, as amended (the “Exchange Act”). The timing,
Paragraph 204 · 36% changed
10-K Feb 5, 2025
In June 2024, we repaid in full the $900 million in aggregate principal amount outstanding of unsecured notes (the “June 2024 Notes”) upon their maturity. The June 2024 Notes bore interest at a rate of 4.200% per annum, payable semi-annually.
10-K Feb 4, 2026
In January 2026, we repaid in full the January 2026 Notes upon their maturity, which bore interest at a rate of 3.875% per annum.
Paragraph 26 · 35% changed
10-K Feb 5, 2025Additionally, since our IPO on October 8, 2004 through December 31, 2024, our realized gains have exceeded our realized losses by approximately $0.9 billion (excluding a one-time gain on the acquisition of Allied Capital Corporation in April 2010 (the “Allied Acquisition”) and realized gains/losses from the extinguishment of debt and other transactions). For the same time period, our average annualized net realized gain rate was approximately 0.8% (excluding a one-time gain on the Allied Acquisition and realized gains/losses from the extinguishment of debt and other transactions). Net realized gain/loss rates for a particular period are the amount of net realized gains/losses during such period divided by the average quarterly investments at amortized cost in such period.
10-K Feb 4, 2026
realized gains/losses from the extinguishment of debt and other transactions). Net realized gain/loss rates for a particular period are the amount of net realized gains/losses during such period divided by the average quarterly investments at amortized cost in such period.
Paragraph 67 · 35% changed
10-K Feb 5, 2025
(1)We have committed to fund up to $500 million to IHAM, the availability of which is solely at our discretion.
10-K Feb 4, 2026
(1)We have provided a commitment to fund up to $750 million and $500 million, as of December 31, 2025 and 2024, respectively, to IHAM, with availability of funding solely at our discretion.
Paragraph 170 · 35% changed
10-K Feb 5, 2025
(5)Represents the aggregate principal amount outstanding, less unamortized debt issuance costs and the net unaccreted/amortized discount or premium recorded upon issuance. In March 2024, we repaid in full the 2024 Convertible Notes (as defined below) upon their maturity. In June 2024, we repaid in full the June 2024 Notes (as defined below) upon their maturity.
10-K Feb 4, 2026
(5)Represents the aggregate principal amount outstanding, less unamortized debt issuance costs and the net unaccreted/amortized discount or premium recorded upon issuance. In March 2025 and July 2025, we repaid in full the March 2025 Notes and the July 2025 Notes (each as defined below), respectively, upon their maturity. See “Recent Developments,” as well as Note 16 to our consolidated financial statements for the year ended December 31, 2025 for subsequent events relating to the January 2026 Notes and an additional issuance of unsecured notes.
Paragraph 14 · 33% changed
10-K Feb 5, 2025
•the impact of supply chain constraints on our portfolio companies and the global economy;
10-K Feb 4, 2026
•the impact of global health crises on our or our portfolio companies’ business and the U.S. and global economy;
Paragraph 114 · 32% changed
10-K Feb 5, 2025Dividend income received from IHAM for the year ended December 31, 2024 increased from the comparable period in 2023 primarily due to the increased earnings from the IHAM Vehicles as a result of higher interest rates. Dividend income received from IHAM for the year ended December 31, 2024 includes a non-recurring special dividend of $10 million. Recurring dividend income for the year ended December 31, 2024 increased from the comparable period in 2023 primarily due to an increase in yielding preferred equity investments.
10-K Feb 4, 2026
Recurring dividend income for the year ended December 31, 2025 decreased from the comparable period in 2024 primarily due to a decrease in yielding preferred equity investments.
A paragraph is matched with the one last year that shares the most of its words; under half in common makes it new. The paragraphs shown are the 8 reworded the most in each section.
The paragraph that changed most in each section
The redline
Marked against last year's 10-K: cut words struck through, new words highlighted.
Risk Factors289 words changed in this paragraph; it is 42% similar to last year's version.
In addition, cybersecurity has become is a priority for regulators in the U.S. and around the world. In February 2022, the The SEC proposed, and subsequently delayed the adoption of, new has adopted rules related to cybersecurity risk management for registered investment advisers, registered investment companies and business development companies, as well as amendments to certain rules that govern investment adviser and fund disclosures. companies. In July 2023, addition, the SEC also adopted rules requiring requires public companies to disclose material cybersecurity incidents on Form 8-K and provide periodic disclosure of a registrant’s regarding their cybersecurity risk management, strategy, and governance in annual reports. The rules became effective beginning with annual reports for fiscal years ending on or after December 15, 2023 and beginning with Form 8-Ks on December 18, 2023. In May 2024, the SEC adopted amendments cybersecurity regulations as an amendment to Regulation S-P, which, beginning in S-P designed to establish a federal “minimum standard” for covered institutions to adopt an incident response program to govern their response to any unauthorized access of customer information. The adopted rule requires compliance as of December 2025, require 2025 and applies to us as it includes investment companies and SEC-registered registered investment advisers to adopt advisers. The amendments require implementation of written policies and procedures for to safeguard customer records and information by imposing notification requirements to affected individuals whose sensitive customer information was or is reasonably likely to have been accessed or used without authorization and other requirements, such as review of incident response programs to address unauthorized access to, or use of, customer information, including providing notice to certain individuals affected and having policies and procedures regarding compliance by any such incident. We will need to comply with this amended rule beginning December 2025. third-party service providers. With the SEC particularly focused on cybersecurity, we expect increased scrutiny of our and Ares’ policies and systems designed to manage cybersecurity risks and related disclosures. We also may face increased costs to comply with the new SEC rules, including Ares’ increased costs for cybersecurity training and management, a portion of which may be allocated to us. In addition, the SEC has indicated in recent periods that one of its examination priorities for the Office of Compliance Inspections and Examinations is to continue to examine cybersecurity procedures and controls, including testing the implementation of these procedures and controls.
Source: Item 1A, 10-K 0001287750-26-000006 vs Item 1A, 10-K 0001287750-25-000007
MD&A206 words changed in this paragraph; it is 58% similar to last year's version.
As a BDC, we are required to comply with certain regulatory requirements. For instance, we generally have to invest at least 70% of our total assets in “qualifying assets,” including securities and indebtedness of private U.S. companies and certain public U.S. companies, cash, cash equivalents, U.S. government securities and high-quality debt investments that mature in one year or less. We also may invest up to 30% of our portfolio in non-qualifying assets, as permitted by the Investment Company Act. Specifically, as part of this 30% basket, we may invest in entities that are not considered “eligible portfolio companies” (as defined in the Investment Company Act), including companies located outside of the United States, entities that are operating pursuant to certain exceptions under the Investment Company Act, and publicly traded entities whose public equity market capitalization exceeds the levels provided for under the Investment Company Act. In addition, we, our investment adviser and certain of our affiliates have received an order from the SEC that permits us and other BDCs and registered closed-end management investment companies managed by Ares Management to co-invest in portfolio companies with each other and with other affiliated investment entities (the “Co-Investment Exemptive Order”). As required by the Co-Investment Exemptive Order, we have adopted, and our board of directors has approved, policies and procedures reasonably designed to ensure compliance with the terms of the Co-Investment Exemptive Order, and our investment adviser and our Chief Compliance Officer will provide reporting to our board of directors. Co-investments made under the Co-Investment Exemptive Order are subject to compliance with certain conditions and other requirements, which could limit our ability to participate in co-investment transactions. As a result of investments permitted by the Co-Investment Exemptive Order, there could be significant overlap in our investment portfolio and the investment portfolio of affiliated Ares Management entities that can rely on the Co-Investment Exemptive Order and have an investment objective similar to ours. We may also otherwise co-invest with funds managed by Ares Management or any of its downstream affiliates, subject to compliance with existing regulatory guidance, applicable regulations and our investment adviser’s allocation policy.
Source: Item 7, 10-K 0001287750-26-000006 vs Item 7, 10-K 0001287750-25-000007
Accounting Policies85 words changed in this paragraph; it is 50% similar to last year's version.
The Company reclassified certain prior period amounts in the accompanying consolidated balance sheet and consolidated statement of cash flows operations to conform to its current period presentation, including the industry groupings of certain of the Company’s portfolio companies presentation. The Company separately disclosed “interest rate swap collateral payable” and “deferred tax liabilities” from “accounts payable and other liabilities” in the accompanying consolidated schedule balance sheet. In addition, the Company separately disclosed “income tax expense on net realized gains” from “income tax expense, including excise taxes” and “net change in deferred tax liabilities” from “net unrealized gains (losses) from investments” in the accompanying consolidated statement of investments and the notes to the consolidated financial statements. operations. These reclassifications had no impact on prior periods’ net income or stockholders’ equity.
Source: 10-K text, Note 2 – SIGNIFICANT ACCOUNTING POLICIES, 10-K 0001287750-26-000006 vs 10-K text, Note 2 – SIGNIFICANT ACCOUNTING POLICIES, 10-K 0001287750-25-000007
Legal Proceedings3 words changed in this paragraph; it is 98% similar to last year's version.
As of December 31, 2025 2024 2023 ───────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────── Total revolving loan commitments $ 2,734 $ 2,254 $ 1,814 Less: funded commitments (492) (529) (482) Less: unavailable revolving loan commitments due to borrowing base or other covenant restrictions (11) (1) — Total net unfunded revolving loan commitments 2,231 1,724 1,332 Total unfunded delayed draw loan commitments 2,989 2,193 952 Less: unavailable delayed draw loan commitments due to borrowing base or other covenant restrictions (30) (22) (13) Total net unfunded delayed draw loan commitments 2,959 2,171 939 Total net unfunded revolving and delayed draw loan commitments $ 5,190 $ 3,895 $ 2,271
Source: Item 3, via Note 7 – COMMITMENTS AND CONTINGENCIES, 10-K 0001287750-26-000006 vs Item 3, via Note 7 – COMMITMENTS AND CONTINGENCIES, 10-K 0001287750-25-000007
Sentences and paragraphs added, removed or reworded
Every change, by type
Sentences and paragraphs of ARCC's Risk Factors and MD&A, 10-K Feb 4, 2026 against 10-K Feb 5, 2025. Each links to the text at sec.gov.
Quiet changes are sentences kept from last year with one to four words changed, at least one of them a hedge, a modal or a qualifier (may, could, will, not, significant, material…). A year or date rolling forward is not counted.
The full word list
adverse, adversely, all, although, anticipate, anticipates, any, approximately, believe, believes, can, cannot, certain, could, expect, expects, generally, however, if, intend, intends, largely, likely, many, material, materially, may, might, most, must, never, no, not, possible, primarily, probable, should, significant, significantly, some, substantial, substantially, unlikely, will, would
AddedRisk Factors
•Developments in artificial intelligence could disrupt markets in which we operate and subject us to increased competition, legal and regulatory risks and compliance costs.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedRisk Factors
See “Item 7. Management’s Discussion and Analysis of Financial Condition and Result of Operations—Recent Developments,” as well as Note 16 to our consolidated financial statements for the year ended December 31, 2025 for subsequent events relating to the January 2026 Notes and an additional issuance of unsecured notes.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedRisk Factors
that are on less favorable terms than what we may have originally anticipated, which may impact our return on these investments.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedRisk Factors
diversification requirements. In addition, because the relevant provisions of the Code may change, compliance with one or more of the RIC requirements may be impossible or impracticable.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedRisk Factors
expectations across varied stakeholder interests, it could erode stakeholder trust, impact our reputation and constrain our investment opportunities. Such scrutiny of both ESG and DEI related practices could expose our investment adviser to the risk of litigation, investigations or challenges by federal or state authorities or result in reputational harm.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedRisk Factors
New and evolving and sometimes conflicting sustainability/ESG regulations and disclosure expectations could increase our compliance costs and expose us to enforcement, litigation, or fundraising constraints.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedRisk Factors
Compliance with any new laws or regulations increases our regulatory burden and could result in increased legal, accounting and compliance costs, make some activities more difficult, time-consuming and costly, affect the manner in which we or our portfolio companies conduct our businesses and adversely affect our profitability.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedRisk Factors
Climate change and related transition and physical risks could adversely affect our operations and those of our portfolio companies and increase costs (including insurance costs).
Read it in 10-K Feb 4, 2026 at sec.gov
Show the other 61
AddedRisk Factors
In recent periods, there has been increased activity by certain activist and other organized groups in opposition to certain investments made by and activities of private funds. Such groups may contact or otherwise seek to engage with government and regulatory bodies and fund investors, including public pension funds, to criticize or challenge certain investments, which could lead to negative publicity that could harm our or our investment adviser's reputation. In addition, partially as a result of certain high profile defaults and bankruptcies, there has also been increased negative publicity with respect to the private credit industry. Although neither we nor our investment adviser have been involved in those particular defaults and bankruptcies, the negative publicity and concerns surrounding the private credit industry generally could in the future harm our or our investment adviser's reputation, adversely affect our borrower or investor relationships and fundraising efforts and create pressure on the trading price of our common stock.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedRisk Factors
Regulators are also increasing scrutiny and implementing and considering regulation of the use of artificial intelligence technologies, including with respect to uses of artificial intelligence by investment advisers. While comprehensive U.S. regulation has not been enacted to date, various U.S. governmental agencies and departments, including the SEC and Department of the Treasury, have recently released reports or otherwise indicated interest in assessing risks relating to uses of artificial intelligence by businesses such as ours. Some specific laws governing artificial intelligence have already been passed in certain U.S. states and in the EU. We cannot predict what, if any, effects this may have on our business or the nature of future regulations.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedRisk Factors
•an increase in negative global media coverage relating to the private credit industry.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedRisk Factors
We are materially affected by conditions in the global financial markets and economic and political conditions throughout the world that are outside our control. These conditions may affect the level and volatility of securities prices and the liquidity and value of our investments, and we may not be able to or may choose not to manage our exposure to these conditions. This could in turn have a significant adverse effect on our business, financial condition and results of operations.
Read it in 10-K Feb 4, 2026 at sec.gov
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RemovedRisk Factors
RewordedRisk Factors
As of December 31, 2024, 2025, we had approximately $3.6 $4.5 billion of outstanding borrowings under the Credit Facilities, our wholly owned consolidated subsidiary, Ares Direct Lending CLO 1 LLC (“ADL CLO 1”) had approximately $476 million in aggregate principal amount outstanding of the notes offered in the ADL CLO 1 debt securitization that mature on April 25, 2036 (collectively, the “April 2036 CLO Notes”), excluding the approximately $226 million of subordinated notes that mature on April 25, 2036 issued by ADL CLO 1 which were retained by us and eliminated in consolidation (the “April 2036 CLO Subordinated Notes”), our wholly owned consolidated subsidiary, Ares Direct Lending CLO 4 LLC (“ADL CLO 4”) had approximately $544 million in aggregate principal amount outstanding of the loans incurred in the ADL CLO 4 debt securitization that mature on October 24, 2036 (collectively, the “October 2036 CLO Secured Loans” and, together with the April 2036 CLO Notes, the “Debt Securitizations”), Loans”), excluding the approximately $260 million of subordinated notes that mature on October 24, 2036 issued by ADL CLO 4 which were retained by us and eliminated in consolidation (the “October 2036 CLO Subordinated Notes”), our wholly owned consolidated subsidiary, Ares Direct Lending CLO 7 LLC (“ADL CLO 7”) had approximately $700 million in aggregate principal amount outstanding of the notes offered in the ADL CLO 7 debt securitization that mature on January 20, 2038 (collectively, the “January 2038 CLO Notes” and, together with the April 2036 CLO Notes and the October 2036 CLO Secured Loans, the “Debt Securitizations”), excluding the approximately $303 million of subordinated notes that mature on January 20, 2038 issued by ADL CLO 7 which were retained by us and eliminated in consolidation (the “January 2038 CLO Subordinated Notes”), and we had approximately $9.2 $9.8 billion in aggregate principal amount outstanding of senior unsecured notes (we refer to each series of unsecured notes using the defined term set forth under the “Unsecured Notes” column of the table below and collectively referred to all such series series, together with an additional issuance of unsecured notes as the “Unsecured Notes”). described in “Item 7.
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedRisk Factors
The result of any security incident or cyber-attack may include disrupted operations, including in our and our investment adviser’s operations, misstated or unreliable financial data, fraudulent transfers or requests for transfers of money, liability for stolen or improperly accessed assets or information (including personal information), fines or penalties, investigations, increased cybersecurity protection and insurance costs, litigation, or damage to our business relationships and reputation, in each case, causing our business and results of operations to suffer or otherwise causing interruptions or malfunctions in our, our investment adviser’s employees’, our administrator’s employees’, their affiliates’ employees’, our investors’, our counterparties’ or third parties’ operations.
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedRisk Factors
RewordedRisk Factors
RewordedRisk Factors
We are party to an administration agreement with our administrator, Ares Operations, a subsidiary of Ares Management, pursuant to which our administrator furnishes us with administrative services and we pay our administrator at cost our allocable portion of overhead and other expenses (including travel expenses) incurred by our administrator in performing its obligations under our administration agreement, including our allocable portion of the compensation, rent, and other expenses of certain of our officers (including our chief compliance officer, chief financial officer, chief accounting officer, general counsel, secretary, treasurer and assistant treasurer) and their respective staffs, but not investment professionals.
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedRisk Factors
RewordedRisk Factors
Our business operations and our portfolio companies may face risks associated with climate change, including risks related to the impact of climate-related legislation and regulation (both domestically and internationally), risks related to climate-related business trends (such as the process of transitioning to a lower-carbon economy), and risks stemming from the physical impacts of climate change, such as the increasing frequency or severity of extreme weather events (including wildfires, droughts, hurricanes and floods) and rising sea levels and temperatures.
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedRisk Factors
RewordedRisk Factors
RewordedRisk Factors
RewordedRisk Factors
In addition, there may be conflicts in the allocation of investments among us and the funds managed by investment managers affiliated with Ares (including our investment adviser) or one or more of our controlled affiliates or among the funds they manage, including investments made pursuant to the Co-Investment Exemptive Order.
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedRisk Factors
Failure to comply with these covenants could result in a default under the Credit Facilities, the Debt Securitizations or the Unsecured Notes, that, if we were unable to obtain a waiver from the lenders or holders of such indebtedness, as applicable, such lenders or holders could accelerate repayment under such indebtedness and thereby have a material adverse impact on our business, financial condition and results of operations.
Read it in 10-K Feb 4, 2026 at sec.gov
Quiet changesRisk Factors
The types of factors that may be considered in valuing our investments include the enterprise value of the portfolio company (the entire value of the portfolio company to a market participant, including the sum of the values of debt and equity securities used to capitalize the enterprise at a point in time), the nature and realizable value of any collateral, the portfolio company’s ability to make payments and its earnings and discounted cash flows, the markets in which the portfolio company does business, a comparison of the portfolio company’s securities to any similar publicly traded securities, changes in the interest rate environment and the credit markets generally that may affect the price at which similar investments would trade in their principal markets and other relevant factors.
Read it in 10-K Feb 4, 2026 at sec.gov
Quiet changesRisk Factors
Quiet changesRisk Factors
There can be no assurance that adverse developments with respect to CSRD will not adversely affect our assets or the returns from those assets.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedMD&A
•changes in the general economy, including those caused by tariffs and trade disputes with other countries, changes in inflation and risk of recession;
Read it in 10-K Feb 4, 2026 at sec.gov
AddedMD&A
In 2025, U.S. leveraged corporate credit markets delivered positive total returns, supported by growing U.S. gross domestic product and consumer spending, stable inflation and historically low unemployment. These tailwinds were partially offset by slower job growth and increased uncertainty related to tariff policies and risks from various geopolitical developments. Although future economic growth in the U.S. is expected to slow relative to 2024 levels, the U.S debt and equity markets have shown strength as the Federal Reserve’s anticipated accommodative monetary policies are expected to support overall economic activity.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedMD&A
As of December 31, 2025 2024 Amortized Cost Fair Value Amortized Cost Fair Value Debt and other income producing securities(1) 10.3% 10.3% 11.1% 11.2% Total portfolio(2) 9.4% 9.3% 10.0% 9.9% First lien senior secured loans(3) 9.1% 9.2% 9.9% 10.1% Second lien senior secured loans(3) 10.2% 10.7% 12.1% 12.7% Subordinated certificates of the SDLP(3)(6) 13.2% 13.0% 12.4% 13.2% Senior subordinated loans(3) 10.5% 11.0% 11.9% 12.2% Ivy Hill Asset Management L.P.(4) 17.2% 15.3% 16.7% 14.8% Other income producing equity securities(5) 11.0% 11.3% 11.3% 11.5%
Read it in 10-K Feb 4, 2026 at sec.gov
AddedMD&A
Additional supplemental financial information for the SDLP is set forth in Exhibit 99.2 to this Form 10-K.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedMD&A
(1)Accrued in accordance with GAAP as discussed below. As of December 31, 2025 and 2024, there was no capital gains incentive fee actually payable under our investment advisory and management agreement.
Read it in 10-K Feb 4, 2026 at sec.gov
AddedMD&A
Accommodations Plus Technologies LLC and Accommodations Plus Technologies Holdings LLC 39
Read it in 10-K Feb 4, 2026 at sec.gov
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RemovedMD&A
RewordedMD&A
Revenues Investment income $ 344 310 $ 1,014 930 $ (337) (304) $ 1,021 936 Management fees and other income 53 52 11 (51) 12 (50) 15 Total revenues 397 1,026 (387) 1,036 362 941 (355) 948 Expenses Interest expense 37 564 64 487 — 601 551 Distributions to subordinated notes — 209 (154) 55 147 (105) 42 Management fees and other expenses 15 61 (50) 26 17 59 (51) 25 Total expenses 52 834 (204) 682 81 693 (156) 618 Net operating income 345 192 (183) 354 281 248 (199) 330 Net realized losses on investments and foreign currency (28) (99) 18 (109) Net realized gains (losses) on investments and foreign currency — (132) (4) (136) Net realized gain on extinguishment of debt — 2 2 4 21 (23) (2) Net unrealized gains (losses) gains on investments, foreign currency and other transactions (64) 62 57 55 (3) (13) 16 — Total net realized and unrealized losses on investments, foreign currency and other transactions (64) (68) 55 (77) (31) (91) 11 (111) Net income 281 124 (128) 277 250 157 (188) 219 Less:
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedMD&A
Class Type Principal Outstanding Maturity Date Interest Rate April 2036 January 2038 Class A A-1 CLO Notes Senior Secured Floating Rate $ 406 April 25, 2036 SOFR+1.80% April 2036 570 January 20, 2038 SOFR+1.40% January 2038 Class A-2 CLO Notes Senior Secured Floating Rate 50 January 20, 2038 SOFR+1.65% January 2038 Class B CLO Notes Senior Secured Floating Rate 70 April 25, 2036 SOFR+2.20% 80 January 20, 2038 SOFR+1.85% Total April 2036 January 2038 CLO Secured Notes 476 April 2036 700 January 2038 CLO Subordinated Notes Subordinated 226 April 25, 2036 303 January 20, 2038 None Total April 2036 January 2038 CLO Notes $ 702 1,003
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedMD&A
RewordedMD&A
For the Years Ended December 31, (in millions) 2025 2024 2023 Total investment income $ 3,052 $ 2,990 $ 2,614 Total expenses 1,594 1,514 1,328 Net investment income before income taxes 1,458 1,476 1,286 Income tax expense, including excise tax 73 20 taxes 43 40 Net investment income 1,403 1,266 1,415 1,436 Net realized losses on investments, foreign currency and other transactions (55) (179) (20) (88) Net unrealized gains on investments, foreign currency and other transactions (losses) (96) 188 435 Realized loss on extinguishment of debt — (14) — Net increase in stockholders’ equity resulting from operations $ 1,522 1,299 $ 1,522
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedMD&A
(dollar amounts in millions) Description Hedged Item Company Receives Company Pays Maturity Date Notional Amount Interest rate swap January 2027 Notes 7.000% SOFR +2.581% +2.5810% January 15, 2027 $900 Interest rate swap March 2029 Notes 5.875% SOFR +2.023% +2.0230% March 1, 2029 $1,000 Interest rate swap July 2029 Notes 5.950% SOFR +1.643% +1.6430% July 15, 2029 $850 Interest rate swap September 2030 Notes 5.500% SOFR +1.7705% September 1, 2030 $750 Interest rate swap(1) January 2031 Notes 5.100% SOFR +1.7270% January 15, 2031 $650 Interest rate swap(1) March 2032 Notes 5.800% SOFR +1.6995% March 8, 2032 $1,000
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedMD&A
Class Type Principal Outstanding Maturity Date Interest Rate April October 2036 Class A CLO Notes Loans Senior Secured Floating Rate $ 406 April 25, 464 October 24, 2036 SOFR+1.80% April SOFR+1.54% October 2036 Class B CLO Notes Loans Senior Secured Floating Rate 70 April 25, 80 October 24, 2036 SOFR+2.20% SOFR+1.83% Total April October 2036 CLO Secured Notes 476 April Loans 544 October 2036 CLO Subordinated Notes Subordinated 226 April 25, 260 October 24, 2036 None Total April October 2036 CLO Notes $ 702 804
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedMD&A
RewordedMD&A
For the Years Ended December 31, (in millions) 2025 2024 2023 Stated interest expense(1) $ 736 $ 665 $ 535 Credit facility fees 24 23 21 Amortization of debt issuance costs 34 33 31 Net amortization of premium discount/premium on notes payable — (6) (5) Net gain on interest rate swaps accounted for as hedge instruments and the related hedged items (1) — Total interest and credit facility fees $ 793 $ 715 $ 582
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedMD&A
We and our consolidated subsidiary, ARCC FB Ares Capital CP Funding LLC (“AFB”), (“Ares Capital CP”), are party to a revolving funding facility (as amended, the “BNP “Revolving Funding Facility”) with AFB, as the borrower, and BNP Paribas, as the administrative agent and lender, Facility”), that allows AFB Ares Capital CP to borrow up to $1,265 million $2.3 billion at any one time outstanding.
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedMD&A
RewordedMD&A
For the years ended December 31, 2024 2025 and 2023, the estimated excess taxable income carried forward was approximately $922 million and $631 million, respectively, and as a result, 2024, we recorded a net expense of $35 $37 million and $23 $35 million, respectively, for U.S. federal excise tax. taxes.
Read it in 10-K Feb 4, 2026 at sec.gov
RewordedMD&A
Revenues Investment income $ 344 $ 1,014 $ (337) $ 1,021 Management fees and other income 53 12 (50) 15 Total revenues 397 1,026 (387) 1,036 Expenses Interest expense 37 564 — 601 Distributions to subordinated notes — 209 (154) 207 (152) 55 Management fees and other expenses 15 61 (50) 26 Total expenses 52 834 (204) 832 (202) 682 Net operating income 345 192 (183) 194 (185) 354 Net realized gains (losses) on investments and foreign currency — (132) (4) (136) Net realized gain on extinguishment of debt — 1 2 2 4 3 Net unrealized gains (losses) gains on investments, foreign currency and other transactions (64) 62 57 55 Total net realized and unrealized losses on investments, foreign currency and other transactions (64) (68) (69) 55 (77) (78) Net income 281 124 (128) 277 125 (130) 276 Less:
Read it in 10-K Feb 4, 2026 at sec.gov
Quiet changesMD&A
We use words such as “anticipates,” “believes,” “expects,” “intends,” “projects,” “seeks,” “estimates,” “will,” “should,” “could,” “would,” “likely,” “may” and similar expressions to identify forward-looking statements, although not all forward-looking statements include these words.
Read it in 10-K Feb 4, 2026 at sec.gov
Quiet changesMD&A
We are party to a senior secured revolving credit facility (as amended and restated, the “Revolving Credit Facility”), that allows us to borrow up to $4.5 approximately $5.5 billion at any one time outstanding.
Read it in 10-K Feb 4, 2026 at sec.gov
Sources
The two latest 10-Ks on EDGAR, section by section. Each change links to the text at sec.gov.
Also
New risk factors: paragraphs with nothing like them last year, quoted in full.
Work with it
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/ARCC/export.csv") into a cell.