Paragraphs with nothing like them in last year's 10-K
Quoted exactly
3 paragraphs in Risk Factors of the 10-K filed Feb 20, 2026
with nothing like them in the 10-K filed Feb 21, 2025. Quoted exactly.
Paragraphs that were only edited are under 10-K change.
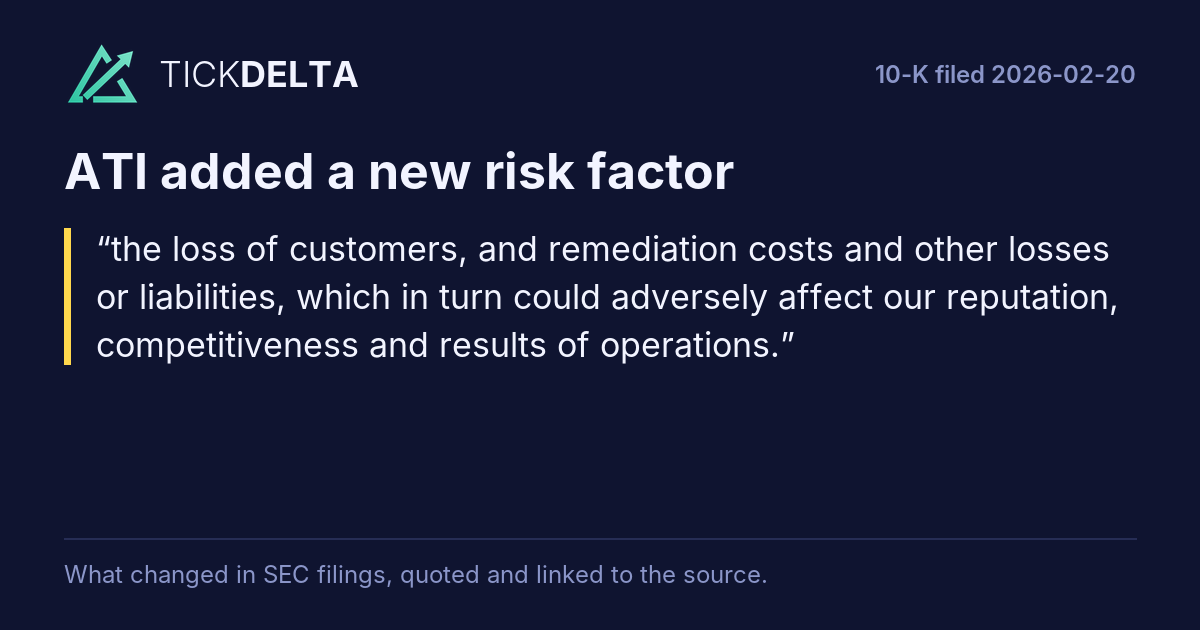
the loss of customers, and remediation costs and other losses or liabilities, which in turn could adversely affect our reputation, competitiveness and results of operations.
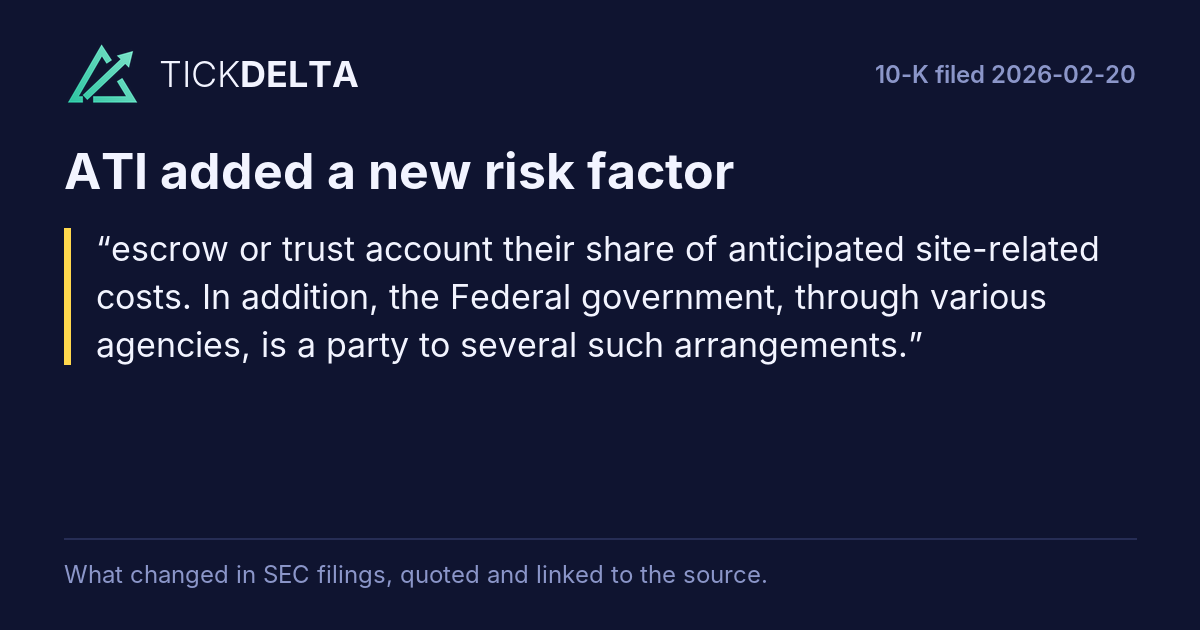
escrow or trust account their share of anticipated site-related costs. In addition, the Federal government, through various agencies, is a party to several such arrangements.
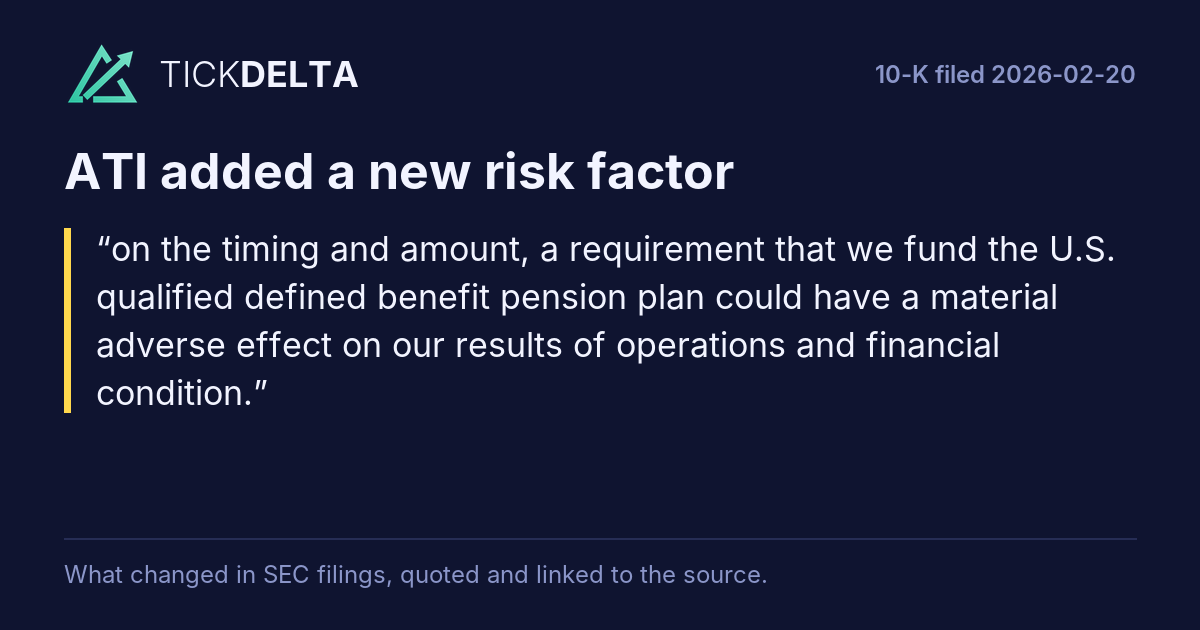
on the timing and amount, a requirement that we fund the U.S. qualified defined benefit pension plan could have a material adverse effect on our results of operations and financial condition.
Paragraphs in the 10-Q filed Oct 29, 2026 that were not in the one before
New in the latest 10-Q
15 paragraphs in the 10-Q filed Oct 29, 2026 with nothing like
them in the 10-Q filed Aug 6, 2026 (at least half the words must differ; new numbers alone do not count).
Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.
Financial statements and notes
ATI Stockholders (In millions, except per share amounts) Common Additional Retained Treasury Accumulated Non- Total
Read in the 10-Qopen_in_new
Item 2. Management’s Discussion and Analysis of Financial Condition and Results of Operations
Read in the 10-Qopen_in_new
We operate in two business segments: High Performance Materials & Components (HPMC) and Advanced Alloys & Solutions
Read in the 10-Qopen_in_new
(AA&S). HPMC produces a wide range of high performance materials, components, and advanced metallic powder alloys.
Read in the 10-Qopen_in_new
These products are made from nickel-based alloys and superalloys, titanium and titanium-based alloys, and a variety of other
Read in the 10-Qopen_in_new
Show the other 10
specialty materials. HPMC’s capabilities range from cast/wrought and powder alloy development to production of highly
Read in the 10-Qopen_in_new
engineered finished components, and 3D-printed aerospace products. The HPMC segment’s primary focus is on maximizing jet
Read in the 10-Qopen_in_new
engine materials and components growth, with approximately 93% of its revenue derived from the aerospace & defense
Read in the 10-Qopen_in_new
The AA&S segment produces nickel-based alloys, titanium and titanium-based alloys, and specialty alloys, including
Read in the 10-Qopen_in_new
zirconium, hafnium, and niobium, in a variety of forms including plate, sheet, and strip products. AA&S focuses on high-value
Read in the 10-Qopen_in_new
materials that are utilized in technically challenging and extreme environments, which require materials that can withstand
Read in the 10-Qopen_in_new
extreme heat, radiation and corrosion. Sales to the aerospace & defense markets comprise approximately 44% of total AA&S
Read in the 10-Qopen_in_new
sales. AA&S also serves customers across several other markets, notably specialty energy and conventional energy, as
Read in the 10-Qopen_in_new
Our third quarter 2026 effective tax rate was 21.0%, which was relatively unchanged from our effective tax rate for the third quarter 2025 of 21.4%. The effective tax rate for the third quarter of 2026 includes discrete tax benefits of $0.8 million, primarily for the release of a foreign valuation allowance, while the effective tax rate for the third quarter of 2025 includes discrete tax expense of $2.8 million, primarily related to return-to-provision adjustments for limitations of permanent benefits due to decreased taxable income.
Read in the 10-Qopen_in_new
(c) Third quarter and year-to-date 2026 includes a pre-tax debt extinguishment charge of $1.2 million for the write-off of unamortized debt issuance costs related to the redemption of the $350 million of 5.875% Senior Notes due 2027.
Read in the 10-Qopen_in_new
The 10-Q's risk factors against the 10-K
Item 1A of the 10-Q filed Oct 29, 2026 against Item 1A of the 10-K filed Feb 20, 2026.
A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed.
Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed,
Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal
(cut words struck through, new words highlighted).
Text on the page, not a score; each links to the filing at sec.gov.
Added10-Q Oct 29, 2026 vs 10-K Feb 20, 2026
The following is an update to and should be read in conjunction with Item 1A. Risk Factors contained in the Company’s Annual Report on Form 10-K for the year ended December 28, 2025. In addition to the other information set forth in this report, you should carefully consider the factors discussed in Part I, “Item 1A. Risk Factors” in our Annual Report on Form 10- K for the year ended December 28, 2025, which could materially affect our business, financial condition or future results. The risks described in our Annual Report on Form 10-K are not the only risks facing our Company. Additional risks and uncertainties not currently known to us or that we currently deem to be immaterial also may materially adversely affect our business, financial condition and/or operating results.
Read it in the 10-Q at sec.govopen_in_new
Added10-Q Oct 29, 2026 vs 10-K Feb 20, 2026
In February 2026, the United States and Israel launched coordinated military strikes against Iran, which retaliated with missile attacks across the region. Although we do not have material operations in the Middle East, the ongoing conflict and any further escalation, including additional military actions, retaliatory measures, sanctions, disruptions to trade or transportation routes, cyberattacks, or other governmental or market responses, could lead to significant disruption of global energy supplies and increases in global energy prices, heighten inflationary pressures on our input costs and supply chain, adversely affect global supply chains, energy markets, commodity prices, currency exchange rates, financial markets and overall macroeconomic conditions, and adversely impact customer spending patterns in markets in which we operate. While we do not expect the impacts of conflict between the United States, Israel, and Iran to have a significant effect on our business, financial condition and results of operations, we are unable to predict the extent or nature of potential future impacts at this time.
Read it in the 10-Q at sec.govopen_in_new
Added10-Q Oct 29, 2026 vs 10-K Feb 20, 2026
Set forth below is information regarding the Company’s stock repurchases during the period covered by this report, comprised of shares repurchased by ATI under the $700 million Share Repurchase Program authorized by the Company’s Board of Directors in September 2024 shares repurchased by ATI under the additional $500 million in repurchase authority announced in February 2026, and shares repurchased by ATI from employees to satisfy employee-owed taxes on share-based compensation. The Company’s current Stock Repurchase Program has no time limit, does not obligate the Company to repurchase any specific number of shares, and may be modified, suspended, or terminated at any time by the Board of Directors without prior notice.
Read it in the 10-Q at sec.govopen_in_new
Added10-Q Oct 29, 2026 vs 10-K Feb 20, 2026
(a) Includes shares repurchased by ATI from employees to satisfy employee-owed taxes on share based compensation.
Read it in the 10-Q at sec.govopen_in_new
Reworded10-Q Oct 29, 2026 vs 10-K Feb 20, 2026
We intend The Company disputes and intends to vigorously defend against these claims, claims but given the preliminary nature of these matters, cannot predict their outcome or estimate any range of reasonably possible loss at this time.
Read it in the 10-Q at sec.govopen_in_newThe 10-K sentenceopen_in_new
Show the other 2
Reworded10-Q Oct 29, 2026 vs 10-K Feb 20, 2026
The ongoing conflict between Russia the United States, Israel, and Ukraine Iran and related geopolitical instability may adversely affect our business and results of operations.
Read it in the 10-Q at sec.govopen_in_newThe 10-K sentenceopen_in_new
Reworded10-Q Oct 29, 2026 vs 10-K Feb 20, 2026
In August 2024, the Company received notice that it and certain of its affiliates are parties to two lawsuits, filed in federal district court for the Western District of Pennsylvania, Pennsylvania (the District Court), that assert various claims associated with the Company’s October 2023 purchase of group annuity contracts to transfer a portion of its U.S. qualified defined benefit pension plan obligations to Athene Annuity and Life Company and Athene Annuity & Life Assurance of New York.
Read it in the 10-Q at sec.govopen_in_newThe 10-K sentenceopen_in_new
Sources
Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.
Also
10-K change: what was reworded or cut, section by section.
Work with it
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/ATI/export.csv") into a cell.