Form 10-K for the Fiscal Year ended December 31, 2023
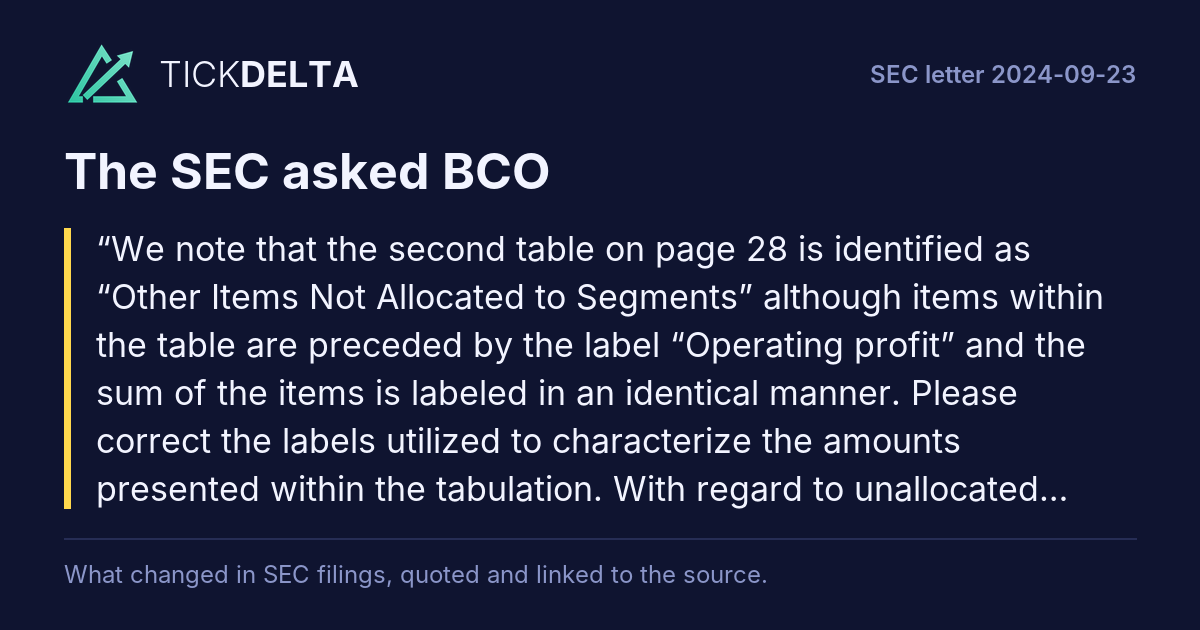
We note that the second table on page 28 is identified as “Other Items Not Allocated to Segments” although items within the table are preceded by the label “Operating profit” and the sum of the items is labeled in an identical manner. Please correct the labels utilized to characterize the amounts presented within the tabulation.Rest of the question
With regard to unallocated costs, please disclose the criteria utilized to report such costs as either corporate expenses, which are in turn reflected in your non-GAAP measures, or as other items which are excluded from your non-GAAP measures, and explain how that criteria serves to appropriately differentiate between items that are representative of "core operating performance" or "regular earnings" and items that are not, in your view. Non-GAAP Results Reconciled to GAAP, page 35 Given the emphasis you have placed on non-GAAP measures throughout MD&A, and considering language characterizing your non-GAAP measures as more representative of core operating performance and regular earnings than the corresponding GAAP measures, it is unclear how you have considered our Compliance and Disclosure Interpretations (C&DI's) on Non-GAAP measures in formulating your disclosures. Please address the following points. • Provide us with an analysis of each adjustment showing how you considered the guidance in Question 100.01 of our C&DI's, as to whether the excluded item represents a normal, recurring, cash operating expense necessary to operate your business, and explaining how your exclusion of any amount designated as such would not cause the resulting measure to be misleading in your view. • Please address the guidance in Question 102.10(c) of our C&DI's with respect to your presentation of non-GAAP measures in each section of your discussion and analysis, and submit the revisions that you propose to restore balance to the disclosures and to avoid giving undue prominence to your presentation of non-GAAP measures. 3. You may view the C&DI's on Non-GAAP measure at the following address: https://www.sec.gov/corpfin/non-gaap-financial-measures.htm.
The Company acknowledges theRead in the reply
Staff’s comments and will revise the “Other Items Not Allocated to Segments” table to provide clarifying labels and descriptions. See page 7 of Exhibit A-1 for example language for such updated table.
The Company first considers if items should be included or excluded from non-GAAP measures based on whether or not we consider them to be part of the Company’s operations and revenue generating activities. Items that are included in non-GAAP measures are reported in either Corporate expenses or in segment results.Rest of the answer
Items that are excluded from non-GAAP measures would otherwise have been in either Corporate or segment results and are reported as Other Items not Allocated to Segments.
Corporate expenses include costs to manage the global business and perform activities required by public companies, as well as other items that are considered part of the Company’s operations and revenue generating activities, but are not considered when the chief operating decision maker ("CODM") evaluates segment results. Examples include corporate staff compensation, corporate headquarters costs, regional management costs, share-based compensation, and currency transaction gains and losses.
Other Items not Allocated to Segments include income and expenses that are not necessary to operate the Company's business in the ordinary course and are not considered when the CODM evaluates segment results. These include non-recurring, as well as certain recurring costs and gains. The Company believes each of the items in the “Other Items Not Allocated to Segments” table is appropriately excluded from non-GAAP measures as they are not considered to be part of the Company's operations and revenue generating activities. See pages 7-10 of Exhibit A-1 for additional disclosures to be provided in future filings regarding this criteria.
First report after the company's reply of Oct 22, 2024: 10-Q filed Nov 6, 2024 ↗, against the 10-Q filed Aug 7, 2024 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: closing letter, 2024-11-05