Brinks Co BCO
New risk paragraphs, branching off last year
Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Feb 26, 2025. A box jumps to the paragraph as filed, below.
Paragraphs with nothing like them in last year's 10-K
2 paragraphs in Risk Factors of the 10-K filed Feb 26, 2026 with nothing like them in the 10-K filed Feb 26, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.
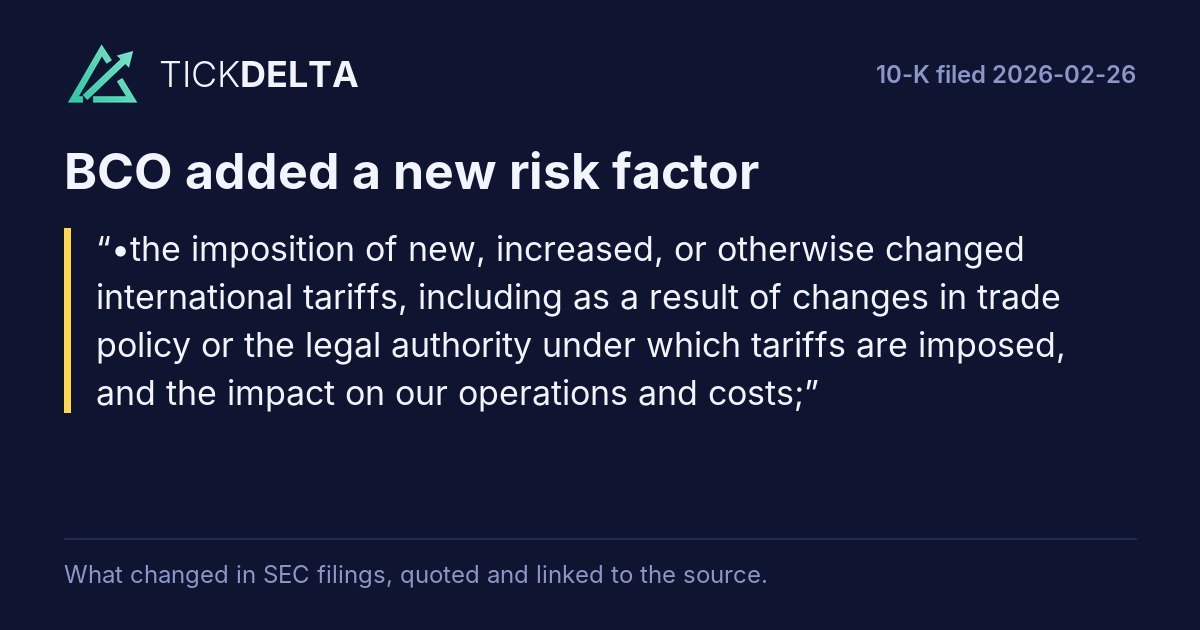
•the imposition of new, increased, or otherwise changed international tariffs, including as a result of changes in trade policy or the legal authority under which tariffs are imposed, and the impact on our operations and costs;
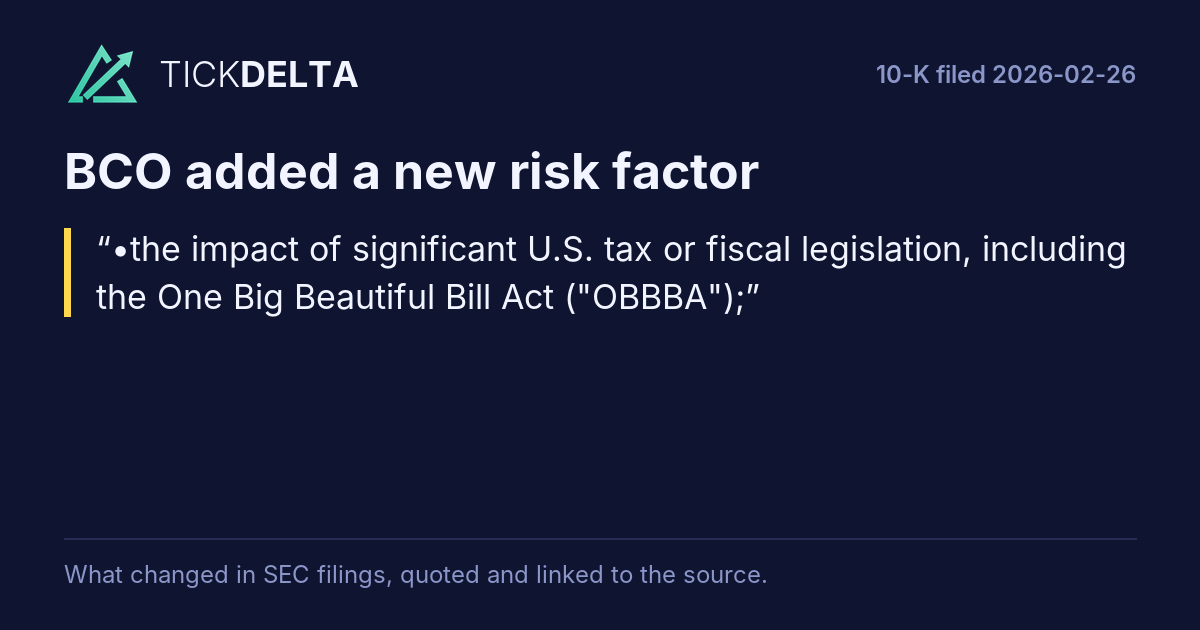
•the impact of significant U.S. tax or fiscal legislation, including the One Big Beautiful Bill Act ("OBBBA");
Paragraphs in the 10-Q filed Nov 4, 2026 that were not in the one before
New in the latest 10-Q
15 paragraphs in the 10-Q filed Nov 4, 2026 with nothing like them in the 10-Q filed Aug 5, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.
Financial statements and notes
Effective July 1, 2026, we concluded that we did not meet the accounting criteria for control over our Malaysia operations and, as a result, we began reporting the results of our 48.88 % investment in our Malaysia subsidiaries using the equity method of accounting. This conclusion, reached in the third quarter of 2026, reflected our assessment of the facts and circumstances relevant to our determination of control.
Read in the 10-Q
The Company recognized a pre-tax deconsolidation net loss of $ 8.9 million during the three and nine months ended September 30, 2026, comprised of a $ 16.1 million net gain reported in other operating income (expense) offset by a $ 25.0 million of net losses reported in nonoperating income (expense) in the condensed consolidated statements of operations. The net gain in other operating income (expense) is primarily comprised of a $ 22.0 million write-off of contingent consideration payable partially offset by $ 6.5 million write-off of receivables (as discussed in Note 9). The net loss reflects the accounting impact of deconsolidating our Malaysia subsidiaries offset by a gain of $ 51.4 million related to remeasuring our retained ownership interest as an equity-method investment at fair value. The fair value was estimated using the Income Approach, which included significant assumptions in preparing the projected cash flows including revenue growth, capital requirements, an EBITDA multiple to determine terminal value, and discount rates.
Read in the 10-Q
(a) Activity includes a $ 16.1 million gain relating to the deconsolidation of our Malaysia subsidiaries. See Note 1 for details.
Read in the 10-Q
Incident-related losses In the first nine months of 2026, we recognized losses of $ 19.6 million related to a September 2026 precious metals robbery within our global services line of business, and $ 7.0 million related to damaged leased and owned inventory from a significant flooding incident at a North America warehouse location.
Read in the 10-Q
Non-routine auto loss matter In 2023, a Brink’s employee was involved in a motor vehicle accident with unique circumstances that resulted in the death of a third party and, in connection with the ensuing litigation, Brink’s recognized a charge. Additionally, we have incurred third-party costs, primarily legal costs, associated with this matter.
Read in the 10-Q
Show the other 10
(a) As a result of the deconsolidation of our Malaysia operations, we derecognized the allowance amount attributed to our Malaysia operations.
Read in the 10-Q
(b) The Provision for uncollectible accounts receivable and Write-offs and recoveries amounts above include approximately $6.5 million in write offs of receivables from our Malaysia operations. See Note 1 for more details about deconsolidation of our Malaysia operations.
Read in the 10-Q
The Company is involved in a regulatory proceeding in the Netherlands. Based on its assessment of the matter and the information currently available, the Company has determined that a loss is not probable and has not recorded an accrual. The ultimate outcome of the proceeding remains uncertain, and the Company is currently unable to reasonably estimate the amount or range of any possible loss. The Company does not expect the proceeding to have a material impact on its consolidated financial statements and will continue to evaluate the matter as additional information becomes available.
Read in the 10-Q
In connection with our planned acquisition of NCR Atleos Corporation, Brink's has been working constructively with the United Kingdom’s Competition and Markets Authority (“CMA”) regarding the proposed divestiture of NoteMachine/TestLink UK (“disposal group”) as an acceptable remedy to address the CMA's UK-specific concerns and avoid a referral for a Phase 2 investigation. Following the CMA’s October 8, 2026 announcement that it had accepted the proposed remedy in principle, the disposal group met the criteria to be classified as held for sale.
Read in the 10-Q
Under held for sale accounting, the assets and liabilities of the disposal group are measured at the lower of carrying amount or fair value less costs to sell and presented separately in the financial statements or related footnotes. We do not currently expect the impact of this measurement to be material to our consolidated financial statements. The related accounting effects will be reflected in our financial statements for the period ending December 31, 2026.
Read in the 10-Q
As of September 30, 2026, the disposal group had total assets and liabilities of $ 240.5 million and $ 47.8 million, respectively. Because
Read in the 10-Q
the held-for-sale criteria were met after September 30, 2026, these assets and liabilities continue to be presented as held and used in the consolidated balance sheet as of that date.
Read in the 10-Q
• Net gain of $16.1 million relating to the deconsolidation of our Malaysia subsidiaries.
Read in the 10-Q
(a) Represents the write-off of the contingent consideration balance associated with the Company's Malaysia operations following their deconsolidation effective July 1, 2026. See Note 1 for further explanation.
Read in the 10-Q
(a) Net loss on write-off of investments in deconsolidated Malaysia operations represents the write-off of investment balances associated with the Company's Malaysia operations following their deconsolidation effective July 1, 2026. See Note 1 for further explanation.
Read in the 10-Q
The 10-Q's risk factors against the 10-K
Item 1A of the 10-Q filed Nov 4, 2026 against Item 1A of the 10-K filed Feb 26, 2026.
A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed.
Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed,
Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal
(cut words struck through, new words highlighted).
Text on the page, not a score; each links to the filing at sec.gov.
What the 10-Q itself says about its risk factors:Information regarding Risk Factors appears in Part I, Item 1A. Risk Factors of our Annual Report on Form 10-K for the year ended December 31, 2025. There have been no material changes in our risk factors previously disclosed in our Annual Report on Form 10-K for the year ended December 31, 2025.
Read in the 10-Q
1 paragraph in the 10-Q's Item 1A, and none of them adds, rewords or quietly edits a paragraph of the 10-K's.
Phrases used for the first time
Two-word phrases in Risk Factors of the 10-K filed Feb 26, 2026 that are in none of the 1 earlier 10-Ks stored, back to Feb 26, 2025
Where each one is used
- management’s current: This document contains both historical and forward-looking information which is based on management’s current expectations, assumptions and beliefs and involves risks and uncertainties that could cause actual results to differ materially.which is based on management’s current expectations, assumptions and beliefs...
- current expectations: This document contains both historical and forward-looking information which is based on management’s current expectations, assumptions and beliefs and involves risks and uncertainties that could cause actual results to differ materially.which is based on management’s current expectations, assumptions and beliefs...
- expectations assumptions: This document contains both historical and forward-looking information which is based on management’s current expectations, assumptions and beliefs and involves risks and uncertainties that could cause actual results to differ materially.which is based on management’s current expectations, assumptions and beliefs...
- involves risks: This document contains both historical and forward-looking information which is based on management’s current expectations, assumptions and beliefs and involves risks and uncertainties that could cause actual results to differ materially.which is based on management’s current expectations, assumptions and beliefs...
- statements contained: This list of risks, uncertainties and contingencies is not intended to be exhaustive. Additional factors that could cause our results to differ materially from those described in the forward-looking statements can be found under “Risk Factors” in Item 1A of this Form 10-K and in our other public filings with the...
Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.
What was taken out
1 paragraph of last year's Risk Factors with nothing like them now. The longest are quoted.
Sources
Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.
Also
10-K change: what was reworded or cut, section by section.
Work with it
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/BCO/export.csv") into a cell.