Screener / SEC EDGAR /CIK 0001666134 /10-K filed Feb 26, 2026, compared with Feb 21, 2025 /Numbers from the XBRL of the 10-Ks
Nasdaq Technology · Software

Blackline, Inc. BL

Compare with peers Embed
New in the 10-K 10 paragraphs with nothing like them in the 10-K filed Feb 21, 2025 New in the 10-Q 24 paragraphs not in the 10-Q filed Aug 5, 2026 10-Q against the 10-K 67 risk factor paragraphs and sentences added or reworded

New risk paragraphs, branching off last year

Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Feb 21, 2025. A box jumps to the paragraph as filed, below.

10 new

Paragraphs with nothing like them in last year's 10-K

Quoted exactly

10 paragraphs in Risk Factors of the 10-K filed Feb 26, 2026 with nothing like them in the 10-K filed Feb 21, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.

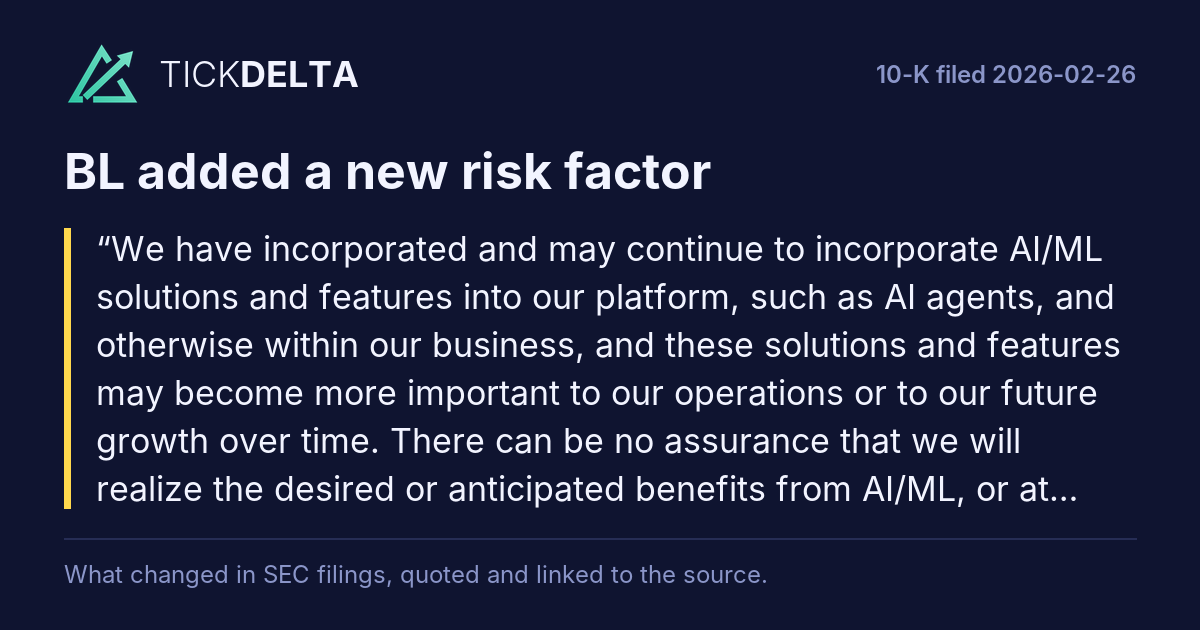
We have incorporated and may continue to incorporate AI/ML solutions and features into our platform, such as AI agents, and otherwise within our business, and these solutions and features may become more important to our operations or to our future growth over time. There can be no assurance that we will realize the desired or anticipated benefits from AI/ML, or at all, and we may fail to effectively implement or market our AI/ML solutions and features. Our competitors or other third parties may incorporate AI/ML into their products, offerings, and solutions more quickly or more successfully than we do, which could impair our ability to compete effectively, and adversely affect our results of operations. We may also face greater competition from non-specialist solutions relying on generic large language models (“LLMs”), generative AI and general-purpose agents to address a broad range of business needs. We must effectively demonstrate to customers and prospects that our solutions and features are superior to other solutions available to their organizations, including generic LLMs, software created using natural language prompts and generative AI, and other emerging technologies. If we are unable to continue to innovate and demonstrate a compelling value proposition that exceeds what customers believe they can create on their own with AI/ML tools, and/or what ERPs are able to integrate directly in their offerings, our ability to attract and retain customers could be diminished, which would adversely affect our business. In addition, if our current and potential competitors develop products with similar or superior functionality to our platform, we may need to decrease the prices or accept less favorable terms for our platform subscriptions in order to remain competitive. If we are unable to maintain our pricing due to competitive pressures, our margins will be reduced and our operating results will be negatively affected.

Additionally, our AI/ML solutions and features may expose us to additional claims, demands, and proceedings by private parties and regulatory authorities and subject us to legal liability as well as brand and reputational harm. For example, the AI/ML models that we use are trained using various data sets, and if our models are incorrectly designed, the data we use to train them is incomplete or inadequate, or we do not have sufficient rights to use the data on which our models rely, the performance of our AI/ML solutions and features, as well as our reputation, could suffer or we could incur liability through the violation of contractual or regulatory obligations. Moreover, the use of AI/ML capabilities or tools to improve internal functions and operations may also introduce other legal, financial, and strategic risks. We may overestimate the ability of such capabilities and tools to yield these benefits, and we may be required to make additional investments in technology and systems. We may also need to make changes to our business and operating model in light of changes in our industry, which could cause disruptions to our business. We have implemented policies, guidelines, and procedures specifically directed at the use of AI/ML tools in the workplace to address these risks, but the use of AI/ML tools by our workforce may nonetheless result in exposure of our proprietary information to unauthorized recipients, exposure to or misuse by unauthorized recipients of our or third-party data or intellectual property, or failure to comply with open source software requirements. Our efforts to mitigate these risks, including through training, monitoring, and enforcement of our policies, guidelines, and procedures governing the use of AI/ML tools may not be successful.

Read in the 10-K

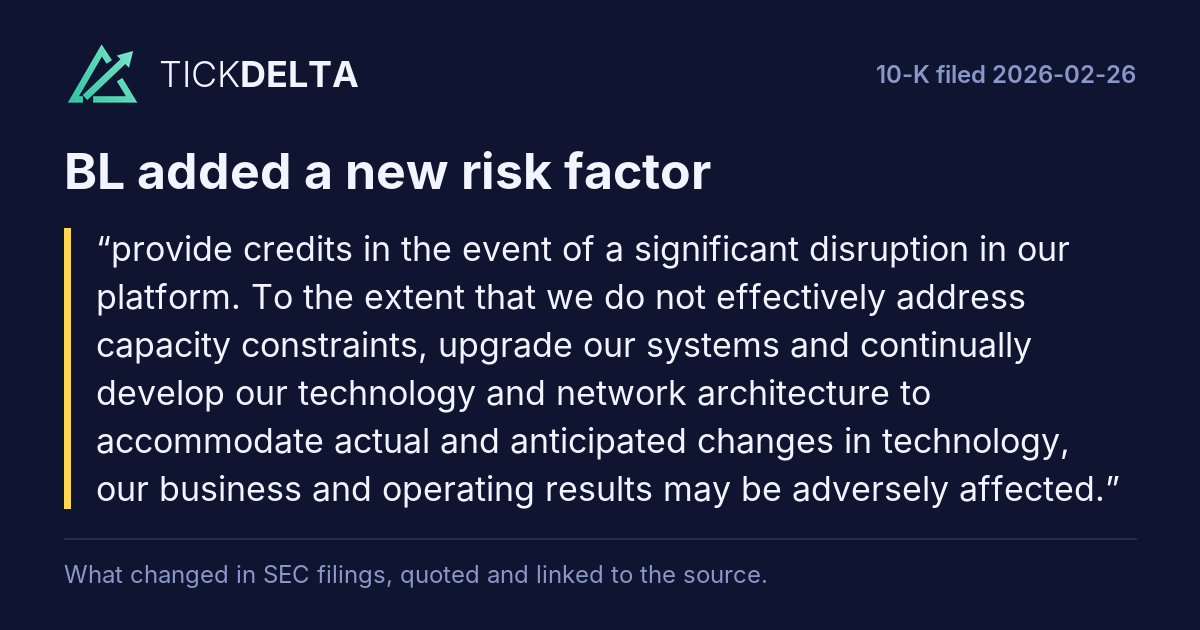
provide credits in the event of a significant disruption in our platform. To the extent that we do not effectively address capacity constraints, upgrade our systems and continually develop our technology and network architecture to accommodate actual and anticipated changes in technology, our business and operating results may be adversely affected.

Read in the 10-K

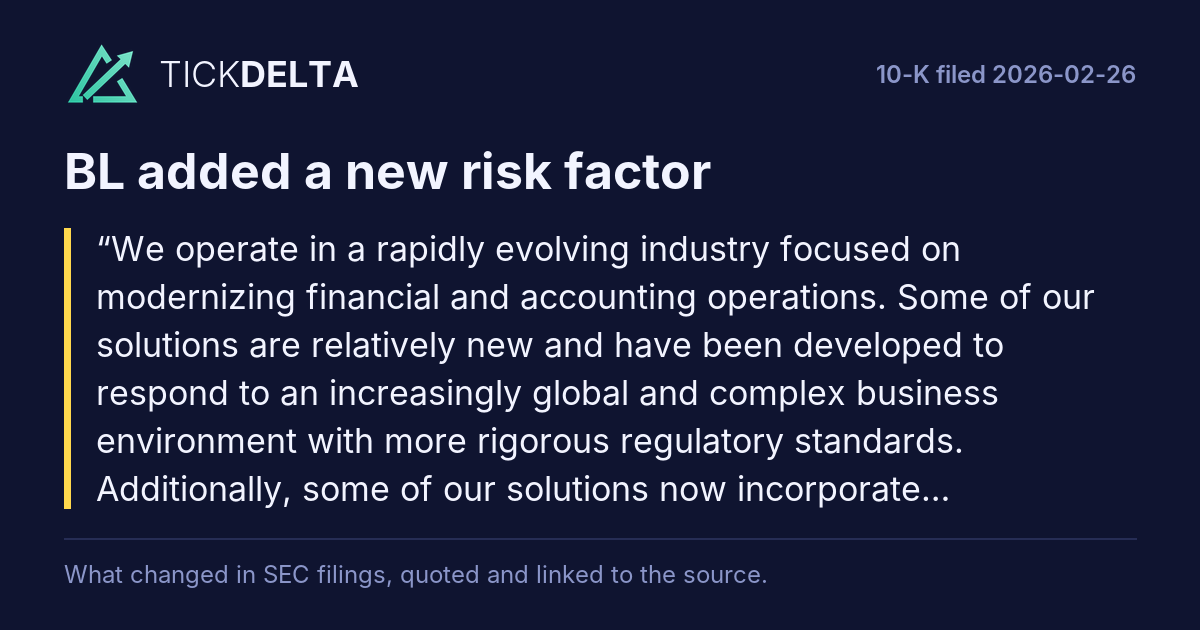
We operate in a rapidly evolving industry focused on modernizing financial and accounting operations. Some of our solutions are relatively new and have been developed to respond to an increasingly global and complex business environment with more rigorous regulatory standards. Additionally, some of our solutions now incorporate AI-enabled features, such as AI agents. While the use of AI/ML is leading to advancements in technology, if our new solutions are not widely adopted and accepted, or fail to operate as expected, our business and reputation may be

Read in the 10-K

Furthermore, our reported net income is impacted by factors beyond our operational spending, including fluctuations in interest income and our provision for income taxes.

Read in the 10-K

competing solutions, our ability to compete in the marketplace or to grow our revenue could be impaired and our operating results could suffer. Even if we are successful, we cannot assure you that these relationships will result in improved operating results.

Read in the 10-K
Show the other 4

business. Privacy, data protection, and cybersecurity concerns, whether valid or not valid, may inhibit the market adoption, effectiveness, or use of our services, particularly in certain industries and foreign countries.

Read in the 10-K

There is considerable patent and other intellectual property development activity in our industry. Our success depends, in part, on not infringing upon the intellectual property rights of others. From time to time, our competitors

Read in the 10-K

competitive, and other factors beyond our control. Further, if any series of the Notes convert and we elect to issue common stock in lieu of cash upon conversion, our existing stockholders could suffer significant dilution.

Read in the 10-K

sustain. In addition, we may be subject to increased regulations, reporting requirements, standards, or expectations regarding the environmental impacts of our business, and failure to comply with such regulations, requirements, standards or expectations could adversely affect our reputation, business or financial performance.

Read in the 10-K

Paragraphs in the 10-Q filed Nov 6, 2026 that were not in the one before

New in the latest 10-Q

24 paragraphs in the 10-Q filed Nov 6, 2026 with nothing like them in the 10-Q filed Aug 5, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.

Financial statements and notes

On September 18, 2026, the Company acquired NetNow Financial Inc. (“NetNow” and such acquisition, the “NetNow Acquisition”), a provider of AI-enabled business-to-business customer onboarding and credit risk management solutions, to expand BlackLine’s Invoice-to-Cash capabilities.

Read in the 10-Q

On September 18, 2026, the Company acquired all of the common stock of NetNow for total purchase consideration, paid in cash, of $ 20.1 million. The Company acquired NetNow to add AI-enabled customer onboarding and credit risk management to its Invoice-to-Cash offerings and extend those offerings into the broader order-to-cash process.

Read in the 10-Q

The Company accounted for the transaction as a business combination using the acquisition method of accounting. The purchase consideration was allocated to the tangible and identifiable intangible assets acquired and liabilities assumed based on their respective estimated fair values on the acquisition date. This acquisition was not a significant acquisition under Regulation S-X, and the purchase consideration allocation is preliminary and subject to change as the Company finalizes the closing completion accounts adjustment to the purchase consideration.

Read in the 10-Q

Transaction costs related to the acquisition and accounted for separately from the assets acquired and liabilities assumed were $ 0.8 million. These costs were expensed as incurred in general and administrative expenses in the unaudited condensed consolidated statements of operations.

Read in the 10-Q

The purchase consideration and major classes of assets and liabilities to which the Company allocated the purchase consideration of $ 20.1 million were as follows (in thousands):

Read in the 10-Q
Show the other 19

Total purchase consideration $ 20,096 Cash and cash equivalents $ 2,619 Accounts receivable, net 141 Prepaids and other current assets 28 Property and equipment 18 Intangible assets 9,125 Goodwill 11,101 Other assets 2 Accounts payable (7) Accrued liabilities (103) Deferred revenue (767) Deferred tax liabilities, net (2,061) Total purchase consideration $ 20,096

Read in the 10-Q

The Company believes the amount of goodwill resulting from the acquisition is primarily attributable to expected future synergies from integrating NetNow’s technology with the Company’s Invoice-to-Cash offerings. The goodwill resulting from the acquisition is not tax deductible.

Read in the 10-Q

The Company, with assistance from a third-party specialist, determined the fair value of the acquired intangible assets using the income approach, specifically the relief-from-royalty method for developed technology and the multi-period excess earnings method for customer relationships. All estimates, key assumptions, and forecasts were either provided by, or reviewed by the Company. While the Company chose to utilize a third-party valuation specialist for assistance, the fair value analysis and related valuations reflect the conclusions of the Company and not those of any third party. The fair value measurements of the intangible assets were based primarily on significant unobservable inputs and thus represent a Level 3 measurement as defined in ASC 820, Fair Value Measurement. The acquired intangible asset categories, fair value, and amortization periods, were as follows:

Read in the 10-Q

Amortization Period Fair Value (in years) (in thousands) Developed technology 6 $ 6,260 Customer relationships 8 2,865 $ 9,125

Read in the 10-Q

The weighted average life of intangible assets at the acquisition date was 6.6 years.

Read in the 10-Q

The revenue and earnings of NetNow were included in the Company’s results since the acquisition date. Neither these amounts nor pro forma revenue and results of operations are presented separately, as their impact is not material to the Company’s unaudited condensed consolidated financial statements for the periods presented.

Read in the 10-Q

(1) Reflects additions to the gross carrying amount of $ 6.3 million and $ 2.9 million of developed technology and customer relationships, respectively, related to the NetNow Acquisition during the quarter ended September 30, 2026. Refer to “Note 5 - Business Combinations” for additional information.

Read in the 10-Q

(1) Relates to the NetNow Acquisition during the quarter ended September 30, 2026. Refer to “Note 5 - Business Combinations” for additional information.

Read in the 10-Q

The following tables summarize the related activity for the Fiscal 2025 and Fiscal 2026 restructuring programs for the quarter and nine months ended September 30, 2026 (in thousands):

Read in the 10-Q

In addition, the Company incurred $ 1.3 million of accelerated amortization of right-of-use lease assets and other lease asset disposal costs recorded to restructuring costs in the unaudited condensed consolidated statements of operations in connection with the Fiscal 2026 restructuring program.

Read in the 10-Q

Our cloud-based solutions, delivered through our Agentic Financial Operations Platform, span three primary areas: Financial Close and Consolidation, Intercompany, and Invoice-to-Cash. These solutions help organizations automate, standardize, and manage critical financial and accounting processes, including financial close and reporting, account reconciliations, financial consolidation, intercompany accounting and settlement, and accounts receivable management.

Read in the 10-Q

On September 18, 2026, we acquired NetNow Financial Inc. (“NetNow” and such acquisition, the “NetNow Acquisition”), a provider of AI-enabled business-to-business customer onboarding and credit risk management solutions, to expand our Invoice-to-Cash capabilities.

Read in the 10-Q

• $1.6 million increase in advisory and legal-related expenses, including transaction-related costs for the NetNow Acquisition; and

Read in the 10-Q

• $2.1 million increase in advisory and legal-related expenses, including transaction-related costs for the NetNow Acquisition; and

Read in the 10-Q

Risk Factors

transformation, could negatively impact customers’ ability or willingness to renew their subscription agreements or could cause our customers to downgrade the terms of their subscription agreements.

Read in the 10-Q

Use of our platform involves the storage, transmission and processing of our customers’ proprietary data, including highly confidential financial information regarding their business and personal or identifying information of

Read in the 10-Q

increase our revenue through additional sales in any period, as revenue from new customers must be recognized over the applicable subscription term.

Read in the 10-Q

authorities have created complexity and uncertainty regarding processing and transfers of personal data from the EEA to the U.S. and certain other countries outside the EEA.

Read in the 10-Q

our business, and failure to comply with such regulations, requirements, standards or expectations could adversely affect our reputation, business or financial performance.

Read in the 10-Q

The 10-Q's risk factors against the 10-K

Item 1A of the 10-Q filed Nov 6, 2026 against Item 1A of the 10-K filed Feb 26, 2026. A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed. Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed, Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal (cut words struck through, new words highlighted). Text on the page, not a score; each links to the filing at sec.gov.

Added10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
transformation, could negatively impact customers’ ability or willingness to renew their subscription agreements or could cause our customers to downgrade the terms of their subscription agreements.

Read it in the 10-Q at sec.gov

Added10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
Growth in our customer base and operations has placed, and may continue to place, a significant strain on our managerial, administrative, operational, financial and other resources, particularly as we focus on cost discipline and efficiency. We anticipate that additional investments in our infrastructure will be necessary to support the growth of our operations both domestically and internationally. These additional investments will increase our costs, with no assurance that our business or revenue will grow sufficiently to cover these additional costs. Labor shortages and

Read it in the 10-Q at sec.gov

Added10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
Use of our platform involves the storage, transmission and processing of our customers’ proprietary data, including highly confidential financial information regarding their business and personal or identifying information of

Read it in the 10-Q at sec.gov

Added10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
increase our revenue through additional sales in any period, as revenue from new customers must be recognized over the applicable subscription term.

Read it in the 10-Q at sec.gov

Added10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
Conducting international operations, particularly in new markets, subjects us to additional risks. These risks include:

Read it in the 10-Q at sec.gov

Show the other 16
Added10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
authorities have created complexity and uncertainty regarding processing and transfers of personal data from the EEA to the U.S. and certain other countries outside the EEA.

Read it in the 10-Q at sec.gov

Reworded10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
For example, the AI/ML models that we use are trained using various data sets, and if our models are incorrectly designed, the data we use to train them is incomplete or inadequate, or we do not have sufficient rights to use the data on which our models rely, the performance of our AI/ML solutions and features, as well as our reputation, could suffer or we could incur liability through the violation of contractual or regulatory obligations.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
If a publicized security breach or incident occurs with respect to another SaaS provider or other technology company, our current and potential customers may lose trust in the security of our platform or in the SaaS business model generally, which could adversely impact our ability to retain existing customers or attract new ones.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
On January 5, 2026, the OECD announced a “side-by-side” elective safe harbor that exempts U.S.-parented multinational entities from certain provisions of Pillar 2 for fiscal years beginning on or after January 1, 2026. 2026, but does not provide an exemption from the “qualified domestic minimum top-up taxes,” which many countries have enacted or have begun enacting laws based on Pillar 2 proposals.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
Even in the absence of unfavorable macroeconomic trends, changes in the size and mix of IT spend, such as favoring newer technologies like AI/ML at the expense of digital transformation, could negatively impact customers’ ability or willingness to renew their subscription agreements or could cause our customers to downgrade the terms of their subscription agreements.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
This ruling from the CJEU and recent rulings from various European Union (“EU”) member state data protection authorities have created complexity and uncertainty regarding processing and transfers of personal data from the EEA to the U.S. and certain other countries outside the EEA.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
Market acceptance of our products may also be affected by customer confusion associated with the introduction of new and emerging technologies by us and our competitors, or changes in technological trends, such as the increase in the use of AI/ML. AI/ML, including agentic AI, particularly to the extent that our potential customers are more easily able to develop their own solutions with AI/ML technologies.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
If we are unsuccessful in establishing or maintaining our relationships, or if the counterparties to our relationships offer competing solutions, our ability to compete in the marketplace or to grow our revenue could be impaired and our operating results could suffer.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
In addition, to the extent that fluctuations in currency exchange rates cause our results of operations to differ from our expectations or the expectations of our investors, the trading price of our common stock could be adversely affected.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
Our failure to repurchase such the 2029 Notes at a time when the repurchase is required by the applicable indenture governing such the 2029 Notes or to pay cash upon conversions conversion of such the 2029 Notes or at their respective maturity as required by the applicable indenture governing such the 2029 Notes would constitute a default under such the indenture.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
If a publicized security breach or incident occurs with respect to another SaaS provider or other technology company, our current and potential customers may lose trust in the security of our platform or in the SaaS business model generally, which could adversely impact our ability to retain existing customers or attract new ones.

Read it in the 10-Q at sec.govThe 10-K sentence

Quiet changes10-Q Nov 6, 2026 vs 10-K Feb 26, 2026
If our security controls are breached or unauthorized, if unauthorized or inadvertent access to customer, employee or other confidential data is otherwise obtained, our software solutions may be perceived as insecure, we may lose existing customers or fail to attract new customers, our business may be harmed and we may incur significant liabilities.

Read it in the 10-Q at sec.govThe 10-K sentence

The first 21 of 67 are shown (at most 12 of each type).

Phrases used for the first time

Two-word phrases in Risk Factors of the 10-K filed Feb 26, 2026 that are in none of the 1 earlier 10-Ks stored, back to Feb 21, 2025

cloud offerings ×5protection cybersecurity ×4offerings generally ×4data act ×4non-tariff trade ×3trade barriers ×3cloud sovereignty ×3unauthorized recipients ×2imposes obligations ×2executive officer ×2gaap profitability ×2without limitation ×2sovereignty requirements ×2additional compliance ×2cloud service ×2service interoperability ×2
Where each one is used
  • cloud offerings: Privacy and cybersecurity concerns, customer expectations, and evolving domestic or foreign laws and regulations, including increased regulation of cloud offerings and restrictions of cross-border data transfers, may limit or reduce the adoption of our services, result in significant costs and compliance...
  • protection cybersecurity: Global legal and regulatory requirements related to collecting, storing, handling, transferring, and otherwise processing personal data are rapidly evolving in ways that require our business to adapt to support our compliance and our customers’ compliance. As the regulatory focus on privacy, data protection,...
  • offerings generally: Global legal and regulatory requirements related to collecting, storing, handling, transferring, and otherwise processing personal data are rapidly evolving in ways that require our business to adapt to support our compliance and our customers’ compliance. As the regulatory focus on privacy, data protection,...
  • data act: Globally, virtually every jurisdiction in which we operate has established its own frameworks governing privacy, data protection, cybersecurity, and cloud offerings generally with which we, and/or our customers, must comply. These laws and regulations often are more restrictive than those in the U.S. Regulatory...
  • non-tariff trade: Our operating results may vary based on the impact of changes in our industry or the global economy on us or our customers. The revenue growth and potential profitability of our business depend on demand for business software applications and services generally, and for accounting and finance systems in particular....
  • trade barriers: Our operating results may vary based on the impact of changes in our industry or the global economy on us or our customers. The revenue growth and potential profitability of our business depend on demand for business software applications and services generally, and for accounting and finance systems in particular....
  • cloud sovereignty: If we are unable to provide enhancements and new features for our existing solutions or new solutions that achieve market acceptance or that keep pace with rapid technological developments, our business could be adversely affected. For example, advancements in technology and the introduction of products by our...
  • unauthorized recipients: Additionally, our AI/ML solutions and features may expose us to additional claims, demands, and proceedings by private parties and regulatory authorities and subject us to legal liability as well as brand and reputational harm. For example, the AI/ML models that we use are trained using various data sets, and if...

The 10-K at sec.gov

Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.

What was taken out

7 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.

Across all companies
Our operating results may vary based on the impact of changes in our industry or the global economy on us or our customers. The revenue growth and potential profitability of our business depend on demand for business software applications and services generally, and for accounting and finance systems in particular. We have been operating in a period of economic uncertainty and cannot predict the timing, strength, or duration of any economic
In the 10-K filed Feb 21, 2025
Our sales and marketing efforts have been and may continue to be impacted by geopolitical developments and other events beyond our control, including economic volatility and macroeconomic trends. Such events have resulted in increased price sensitivity on the part of certain current and prospective customers, and could negatively impact sales for certain of our premium-priced offerings.
In the 10-K filed Feb 21, 2025
The market for accounting and financial software and services is highly competitive and rapidly evolving. Our competitors vary in size and in the breadth and scope of the products and services they offer. We often compete
In the 10-K filed Feb 21, 2025
Section 22 of the Securities Act creates concurrent jurisdiction for federal and state courts over all such Securities Act actions. Accordingly, both state and federal courts have jurisdiction to entertain such claims. To
In the 10-K filed Feb 21, 2025

Sources

Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.

Also

10-K change: what was reworded or cut, section by section.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/BL/export.csv") into a cell.

Next:10-K change
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.