Screener / SEC EDGAR /CIK 0001676238 /10-K filed Mar 25, 2026, compared with Mar 31, 2025 /Numbers from the XBRL of the 10-Ks
Nasdaq Technology · Software

Braze, Inc. BRZE

Compare with peers Embed
New in the 10-K 12 paragraphs with nothing like them in the 10-K filed Mar 31, 2025 New in the 10-Q 6 paragraphs not in the 10-Q filed May 28, 2026 10-Q against the 10-K 28 risk factor paragraphs and sentences added or reworded

New risk paragraphs, branching off last year

Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Mar 31, 2025. A box jumps to the paragraph as filed, below.

12 new

Paragraphs with nothing like them in last year's 10-K

Quoted exactly

12 paragraphs in Risk Factors of the 10-K filed Mar 25, 2026 with nothing like them in the 10-K filed Mar 31, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.

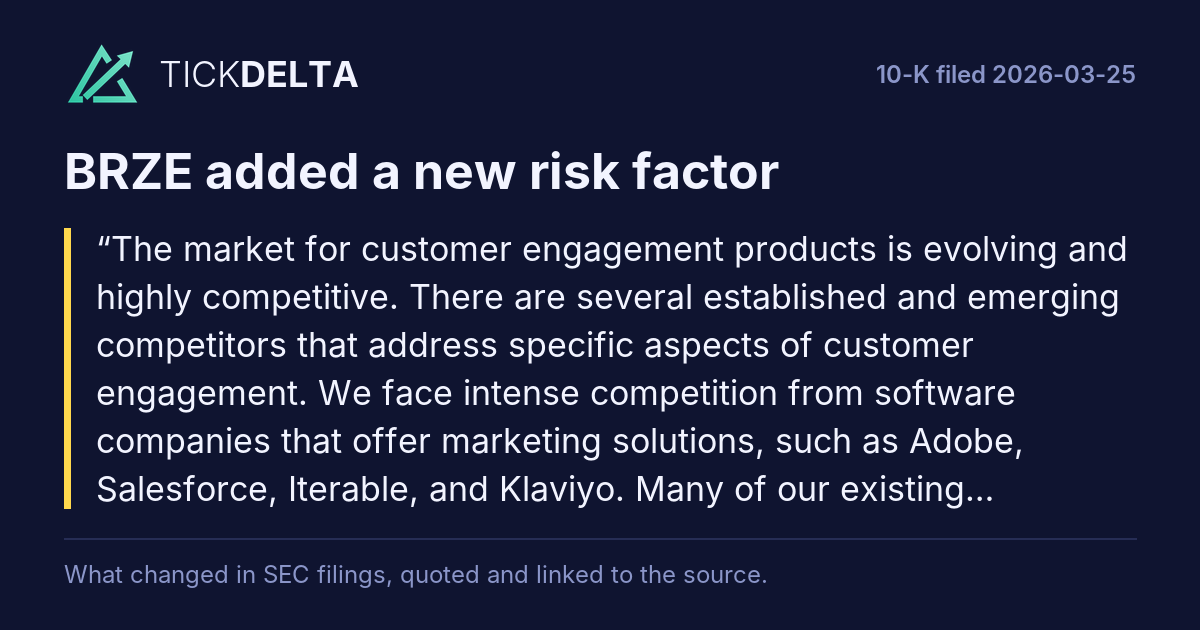
The market for customer engagement products is evolving and highly competitive. There are several established and emerging competitors that address specific aspects of customer engagement. We face intense competition from software companies that offer marketing solutions, such as Adobe, Salesforce, Iterable, and Klaviyo. Many of our existing competitors have, and our potential competitors could have, substantial competitive advantages, such as greater name recognition, longer operating histories, larger sales and marketing budgets and resources, greater customer support resources, lower labor and

Read in the 10-K

•technological innovations, including related to AI, or new standards that our platform does not address;

Read in the 10-K

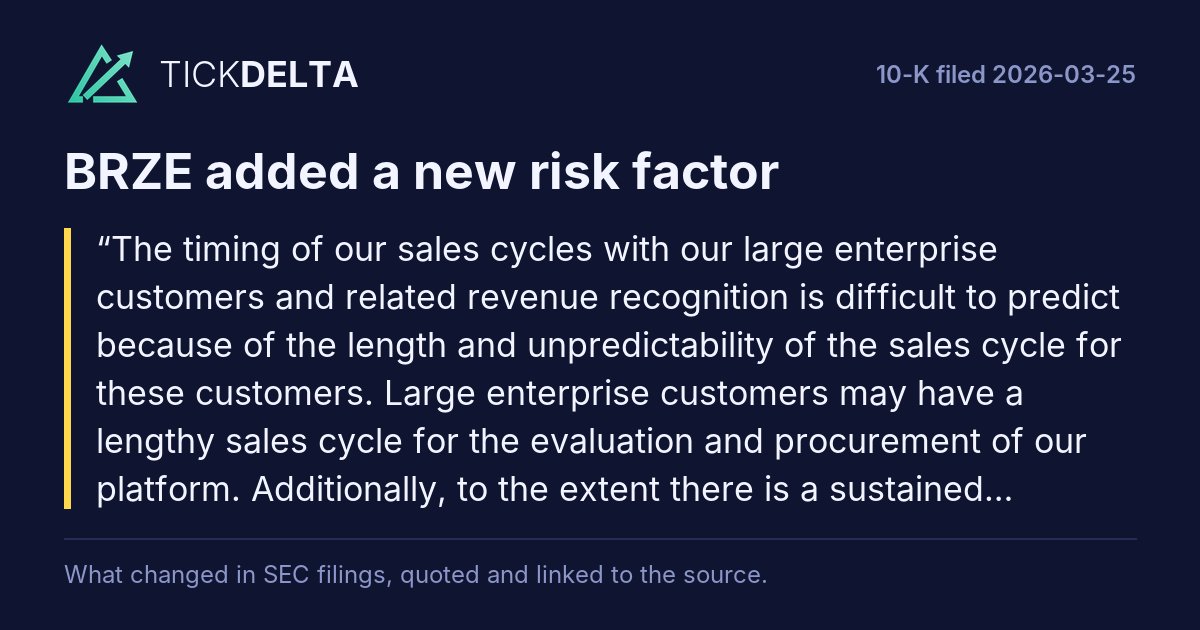
The timing of our sales cycles with our large enterprise customers and related revenue recognition is difficult to predict because of the length and unpredictability of the sales cycle for these customers. Large enterprise customers may have a lengthy sales cycle for the evaluation and procurement of our platform. Additionally, to the extent there is a sustained general economic downturn resulting in delays or reductions in general customer engagement technology spending by large enterprise customers,

Read in the 10-K

We believe that maintaining and enhancing our brand is important to support the marketing and sale of our existing and future products to new customers and expand sales of our platform and products to existing customers. We also believe that the

Read in the 10-K

international conflicts, domestic unrest or the emergence of new highly infectious diseases, if any, may pose additional challenges for international expansion and may impact our ability to launch new locations and further expand geographically.

Read in the 10-K
Show the other 6

violation of the policies of third-party providers or applicable law, even without our knowledge, we may be subject to financial penalties and reputational harm.

Read in the 10-K

We may not carry sufficient business interruption insurance or have sufficient contractual remedies to compensate us for losses that may occur as a result of any events that cause interruptions in our service.

Read in the 10-K

Further, tax legislation continues to evolve globally with new laws and regulations that create uncertainty in the global economy. The Organization for Economic Cooperation and Development reached agreement among over 140 countries to implement a minimum 15% tax rate on certain multinational enterprises, commonly referred to as the Pillar Two framework. Many countries continue to announce changes in their tax laws and regulations based on the Pillar Two framework. Additionally, the U.S Congress enacted the One Big Beautiful Bill Act which includes significant provisions, including tax cut extensions and modifications to the international tax framework. While we continue to evaluate the impact of these legislative changes as additional guidance becomes available, uncertainty remains regarding the timing and interpretation by tax authorities in affected jurisdictions. These legislative changes could have an adverse impact on our future effective tax rate, tax liabilities, and cash tax.

Read in the 10-K

compete effectively, and adversely affect our results of operations. Any of which may have an adverse impact on our results of operations even as our use and development of AI technologies expands.

Read in the 10-K

The automatic conversion of all outstanding shares of our Class B common stock into Class A common stock has eliminated our dual-class structure, which may subject us to increased stockholder activism and potential proxy contests.

Upon the retirement and automatic conversion of our Class B common stock into Class A common stock on January 30, 2026, our executive officers and early investors no longer hold super-voting rights. Consequently, our voting power is now more widely distributed among our public stockholders. This transition may make us more susceptible to stockholder activism, proxy contests, and unsolicited takeover proposals. Responding to activist campaigns can be costly and time-consuming, disrupt our operations, and divert the attention of management and our employees. Furthermore, perceived uncertainties as to our future strategic direction resulting from this change in voting control could result in the loss of potential business opportunities and cause volatility in our stock price.

Read in the 10-K

and results of operations. If one or more of these analysts cease coverage of our company or fail to regularly publish reports on us, we could lose visibility in the financial markets, which could cause our share price or trading volume to decline.

Read in the 10-K

Paragraphs in the 10-Q filed Sep 9, 2026 that were not in the one before

New in the latest 10-Q

6 paragraphs in the 10-Q filed Sep 9, 2026 with nothing like them in the 10-Q filed May 28, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.

Financial statements and notes

(1) The Company did not have finance leases during the three months ended July 31, 2025.

Read in the 10-Q

attract new customers will depend on a number of factors, including the quality and pricing of our products, offerings of our competitors and the effectiveness of our marketing efforts.

Read in the 10-Q

respectively, for our customers with ARR of $500,000 or more. In addition, 361 and 282 of our customers had ARR of $500,000 or more as of July 31, 2026 and July 31, 2025, respectively.

Read in the 10-Q

Our dollar-based net retention rate is influenced by macroeconomic factors that impact our customers’ purchasing decisions, which may impact the revenue attributable to such customers.

Read in the 10-Q

and allocated overhead costs as a result of one-time acquisition compensation related costs incurred in the period of acquisition and the completed vesting of legacy stock option awards.

Read in the 10-Q
Show the other 1

Risk Factors

the European Commission issued an adequacy decision in respect of the U.K.’s data protection framework, enabling data transfers from EU member states to the U.K. to continue until June 27, 2025 without requiring organizations to put in place contractual or other measures in order to lawfully transfer personal data between the territories. While this adequacy decision

Read in the 10-Q

The 10-Q's risk factors against the 10-K

Item 1A of the 10-Q filed Sep 9, 2026 against Item 1A of the 10-K filed Mar 25, 2026. A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed. Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed, Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal (cut words struck through, new words highlighted). Text on the page, not a score; each links to the filing at sec.gov.

Added10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
the European Commission issued an adequacy decision in respect of the U.K.’s data protection framework, enabling data transfers from EU member states to the U.K. to continue until June 27, 2025 without requiring organizations to put in place contractual or other measures in order to lawfully transfer personal data between the territories. While this adequacy decision

Read it in the 10-Q at sec.gov

Added10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
Our sales contracts are denominated primarily in U.S. dollars, and therefore, our revenue is not directly subject to significant foreign currency risk. However, a strengthening of the U.S. dollar could increase the real cost of our platform and products to our customers outside of the United States, which could adversely affect demand for our platform in international markets and our results of operations. In addition, an increasing amount of our operating expenses are incurred outside the United States, including costs related to our international employees, offices and operations. These operating expenses are denominated in foreign currencies and are subject to fluctuations due to changes in foreign currency exchange rates, including the euro, British pound sterling, and other currencies in jurisdictions where we operate. Consequently, our results of operations could be adversely affected by fluctuations in foreign currency exchange rates. While we from time to time enter into hedging transactions to reduce our foreign currency exposure, these hedging transactions may not adequately mitigate the adverse effects of currency exchange rate fluctuations or may themselves result in additional risks or costs to us. As we continue to expand our international operations, our exposure to foreign currency risk may increase, and our business, financial condition and results of operations could be adversely affected.

Read it in the 10-Q at sec.gov

Added10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
In addition, we are subject to the risks of new or enhanced governmental or regulatory scrutiny, litigation, or other legal liability, ethical concerns, negative consumer perceptions as to automation and AI and machine learning technologies, any of which could adversely affect our business, reputation, or financial results. The technologies underlying AI and machine learning and their uses are subject to a variety of laws and regulations related to online services, intermediary liability,

Read it in the 10-Q at sec.gov

Show the other 16
Added10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
We cannot guarantee that our share repurchase program will be fully consummated or that it will enhance long-term stockholder value. Share repurchases could affect the stock price of our Class A common stock and increase its volatility and could diminish our cash reserves

Read it in the 10-Q at sec.gov

Added10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
In March 2026, we announced a program to repurchase up to $100.0 million of our Class A common stock, which included the repurchase $50 million of shares of our Class A common stock through the use of an accelerated share repurchase program. The timing, manner, and amount of any other repurchases pursuant to this share repurchase program will be determined by us at our discretion and will depend on a variety of factors, including business, economic and market conditions, prevailing stock prices, and alternative investment opportunities. The program does not obligate us to repurchase any specific dollar amount or to acquire any specific number of Class A common stock shares, and may be modified, suspended, or terminated at any time without notice.

Read it in the 10-Q at sec.gov

Added10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
Such repurchases could affect our stock price and increase its volatility and will reduce the market liquidity for our stock. These activities may have the effect of maintaining the market price of our Class A common stock or slow down a decline in the market price of our Class A common stock, and, as a result, the price of our Class A common stock may be higher than the price that otherwise might exist in the open market. Additionally, these repurchases will diminish our cash reserves, which could impact our ability to pursue possible future strategic opportunities and acquisitions and result in lower overall returns on our cash balances.

Read it in the 10-Q at sec.gov

Reworded10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
In connection with our the year-end assessment as part of this the Annual Report, we determined that, as of Report on form 10-K for the fiscal year ended January 31, 2026, filed with the SEC on March 25, 2026, we determined that we did not maintain effective internal control over financial reporting due to a material weakness identified in the operation of certain ITGCs relevant to our key accounting, reporting, and proprietary information technology systems, as more fully described in the section entitled "Controls and Procedures" in Item 9A 4 of Part II I of this Annual Quarterly Report on Form 10-K. 10-Q.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
In addition, any future stay-at-home, business closure and other restrictive orders and travel restrictions into and outside the United States as a result of international conflicts, domestic unrest or the emergence of new highly infectious diseases, if any, may pose additional challenges for international expansion and may impact our ability to launch new locations and further expand geographically.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
Additionally, to the extent there is a sustained general economic downturn resulting in delays or reductions in general customer engagement technology spending by large enterprise customers, we may experience an extension of our sales cycle with potential customers or a reduction in sales cycle win rates due to budgetary constraints.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
In general, under Section 382 of the Internal Revenue Code of 1986, as amended, the IRC or the Code, a corporation that undergoes an “ownership change” (which generally is defined under Section 382 of the Code and applicable Treasury Regulations as a greater than 50% change, by value, in its equity ownership over a three-year period) is subject to limitations on its ability to utilize its pre-change NOLs to offset future taxable income.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
In addition to traditional computer “hackers,” threat actors, personnel (such as through theft or misuse), sophisticated nation-states, and nation-state-supported actors now engage in cyberattacks, and nation-state actors may do so for geopolitical reasons and in conjunction with military conflicts and defense activities.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
Our amended and restated certificate of incorporation as currently in effect further provides that, unless we consent in writing to the selection of an alternative forum, the Court of Chancery federal district courts of the State United States of Delaware be America shall, to the sole and exclusive forum for: fullest

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
An adverse determination of any litigation proceedings could put our intellectual property at risk of being invalidated or interpreted narrowly and could put our related patents, patent applications and trademark filings at risk of not issuing or being cancelled.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
We cannot guarantee that any change in strategy will be successful and such changes may cause our revenue to decline, which may inhibit our ability to scale our business and prevent us from achieving and maintaining profitability over the long term.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
These unfavorable conditions have been, and may continue to be, exacerbated in the United States and abroad by global and domestic socioeconomic conditions, including the failure of high-profile banking and other financial institutions, the Federal Reserve’s attempts to combat inflation through interest rate increases, unrest in international trade relations (including those related to trade wars, tariffs, taxation, and importation), domestic and foreign political turmoil, natural catastrophes, pandemics related to highly infectious diseases, warfare and terrorist attacks on the United States, Europe, the Asia Pacific region or elsewhere, and international military conflicts and the related political and economic responses. responses, including ongoing economic uncertainty from trade and resource restrictions resulting therefrom.

Read it in the 10-Q at sec.govThe 10-K sentence

Reworded10-Q Sep 9, 2026 vs 10-K Mar 25, 2026
Any of these security incidents could result in unauthorized access or damage to, or the disablement, encryption, use or misuse, disclosure, modification, destruction or loss of our data or our customers’ data, including personal data, or disrupt our ability to provide our platform or services.

Read it in the 10-Q at sec.govThe 10-K sentence

The first 21 of 28 are shown (at most 12 of each type).

Phrases used for the first time

Two-word phrases in Risk Factors of the 10-K filed Mar 25, 2026 that are in none of the 1 earlier 10-Ks stored, back to Mar 31, 2025

adequacy decision ×3european commission ×2pillar two ×2two framework ×2legislative changes ×2federal agencies ×2automatic conversion ×2stockholder activism ×2proxy contests ×2issued shares ×2
Where each one is used
  • adequacy decision: In addition, many jurisdictions have enacted data localization laws and cross-border personal data transfer laws. These laws may make it more difficult for us to transfer personal data across jurisdictions, which could impede our business. For example, legal developments in the EEA have created complexity and...
  • european commission: In addition, many jurisdictions have enacted data localization laws and cross-border personal data transfer laws. These laws may make it more difficult for us to transfer personal data across jurisdictions, which could impede our business. For example, legal developments in the EEA have created complexity and...
  • pillar two: Further, tax legislation continues to evolve globally with new laws and regulations that create uncertainty in the global economy. The Organization for Economic Cooperation and Development reached agreement among over 140 countries to implement a minimum 15% tax rate on certain multinational enterprises, commonly...
  • two framework: Further, tax legislation continues to evolve globally with new laws and regulations that create uncertainty in the global economy. The Organization for Economic Cooperation and Development reached agreement among over 140 countries to implement a minimum 15% tax rate on certain multinational enterprises, commonly...
  • legislative changes: Further, tax legislation continues to evolve globally with new laws and regulations that create uncertainty in the global economy. The Organization for Economic Cooperation and Development reached agreement among over 140 countries to implement a minimum 15% tax rate on certain multinational enterprises, commonly...
  • federal agencies: In addition, we are subject to the risks of new or enhanced governmental or regulatory scrutiny, litigation, or other legal liability, ethical concerns, negative consumer perceptions as to automation and AI and machine learning technologies, any of which could adversely affect our business, reputation, or financial...
  • automatic conversion: The automatic conversion of all outstanding shares of our Class B common stock into Class A common stock has eliminated our dual-class structure, which may subject us to increased stockholder activism and potential proxy contests.
  • stockholder activism: The automatic conversion of all outstanding shares of our Class B common stock into Class A common stock has eliminated our dual-class structure, which may subject us to increased stockholder activism and potential proxy contests.

The 10-K at sec.gov

Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.

What was taken out

14 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.

Across all companies
Our Class B common stock has ten votes per share and our Class A common stock, which is the stock listed on the Nasdaq Global Select Market, has one vote per share. As a result, as of January 31, 2025, holders of our Class B common stock collectively beneficially owned, in the aggregate, shares representing approximately 64.6% of the voting power of our outstanding capital stock, and our executive officers, directors and holders of 5% or more of our common stock (by voting power) collectively beneficially owned, in the aggregate, outstanding shares representing approximately 69.2% of the...
In the 10-K filed Mar 31, 2025
In response to the COVID-19 pandemic, governments previously instituted shelter-in-place orders, social distancing requirements, travel restrictions and similar measures to slow infection rates. These restrictions prompted shifts from physical commerce to e-commerce, from in-room dining to take out and delivery, from gyms to at home health and fitness and from the theaters to in-home media streaming services. Despite our penetration in these industries that benefited from increased demand during the COVID-19 pandemic, this trend may not continue over the long term. Some of our customers...
In the 10-K filed Mar 31, 2025
We cannot predict whether our dual class structure, combined with the concentrated control of certain stockholders, including our executive officers, employees and directors, investors and their affiliates, will result in a lower or more volatile market price of our Class A common stock or in adverse publicity or other adverse consequences. For example, certain index providers have announced restrictions on including companies with multiple class share structures in certain of their indexes, and our dual class capital structure may make it more difficult for us, or make us ineligible, to...
In the 10-K filed Mar 31, 2025
Our brand, reputation and ability to attract new customers depend on the reliable performance of our technology infrastructure and content delivery. Our platform engages with consumers through a number of channels and integrations, and we are dependent on third-party providers for delivery of content in many of these channels and integrations, including, among others, emails, SMS/MMS/RCS, third-party messaging services and audience sync advertising campaigns. We are also dependent on Apple services and Google services for delivery of mobile and web notifications. If any of these third-party
In the 10-K filed Mar 31, 2025

Sources

Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.

Also

10-K change: what was reworded or cut, section by section.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/BRZE/export.csv") into a cell.

Next:10-K change
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.