tickdelta
Sign in

Tickdelta is free for now. Sign up and get Pro free

← Screener

DFDVDeFi Development

Crypto · Financial Services · Nasdaq, OTC
Compare with peers → Embed

When the SEC's staff reviews a filing, it writes to the company with numbered questions, and the company answers each one in a letter. SEC publishes the exchange once the review is over, at least 20 business days later. Below: what the staff asked DFDV, and the company's answer to each question, quoted from the letters. A question is not an accusation; most reviews end with the company adding detail to its next filing.

Form S-1

2025-09-23 to 2025-10-14 · 8 questions · 2 letters from the SEC, 2 from the company
No closing letter
Crypto assetsResults discussion (MD&A)RevenueSegmentsLiquidity and cashAcquisitionsRisk factorsDerivatives and hedgingDebt
Our Company · Digital Asset Treasury Strategy, page 1
SEC asked (1)
You disclose that your new treasury policy updated your treasury management to "include digital assets, starting with SOL" and that "[m]anagement intends to focus on accumulating digital assets, focusing on SOL, and holding it long-term." Please expand to discuss your intentions to acquire other crypto assets, if any.
Rest of the question

To the extent you intend to acquire a material amount of other crypto assets, please add a section that addresses the characteristics of such crypto assets and the network on which they exist as well as any material risks related to your investment therein. If management does not currently have any such plans, please so state.

DFDV answered
The Company respectfully acknowledges the Staff’s comment and has revised the disclosure on pages 1 and 13 of Amendment No. 1. Read in the reply ↗
Digital Asset Treasury Strategy Revenue, page 2
SEC asked (2)
We note your disclosure that "[w]e derive revenue from our digital asset treasury strategy through delegating a portion of our digital asset holdings with third-party validators… Additionally, we earn validator revenue from participating in the Solana network through creating and validating transactions using our owned validators." Please revise to address the following points: • Quantify the portions of your crypto
Rest of the question

asset holdings that are allocated to your owned validator nodes and to third-party nodes, respectively. • Expand your disclosure to quantify the costs of operating your own validator nodes and address how and whether such operations have a material impact on your profitability. • Quantify the amount of SOL that is staked to your owned validator nodes by third parties.

DFDV answered
has revised the disclosure on pages 2, 13 and 14 of Amendment No. 1. Read in the reply ↗
Digital Asset Treasury Strategy Revenue, page 2
SEC asked (3)
We note your disclosure that "[i]n exchange for staking our digital assets, we receive approximately 10% of the validators' total earned rewards in the form of SOL, net of commission fees." Please revise to discuss how such amount that you receive is determined.
Rest of the question

Also, please revise to explain how the validators' total earned rewards in the form of SOL is determined and calculated and quantify the approximate amount of the validators' commission fees you reference.

DFDV answered
has revised the disclosure on pages 2 and 13 of Amendment No. 1 to clarify how rewards from validators are determined and the approximate commission fees that the Company pays. Read in the reply ↗
Description of Our Segments · Digital Asset Treasury Strategy, page 13
SEC asked (4)
Please expand your disclosure to describe your plan of operation for the next 12 months by disclosing: • The amount and proportions of SOL and/or other crypto assets you have purchased or intend to purchase; • The amount of capital you intend to raise through equity issuances and debt financing for such acquisitions.
Rest of the question

In this regard, we note your disclosure on page 14 that you use proceeds primarily from financing activities that consist of equity issuances and debt financing to acquire SOL; and • An estimated timeline for building your digital asset treasury over this time period. We note your disclosure that "[w]e delegate ('stake') a portion of our digital assets, primarily locked SOL, with third party validators… In some cases, we jointly own and operate validators alongside ecosystem partners to further align our treasury strategy with the broader Solana network." Please revise to provide a materially complete description of your staking program. In this regard, please address each of the following points with respect to your (i) delegated staking activities with third party providers and (ii) staking activities conducted through your owned validators that you operate, as applicable: • State whether you have any target percentage of your SOL holdings that you stake. • Describe in greater detail the mechanics of the staking process. 5. • Disclose the material terms of your agreements with your staking providers, and summarize the responsibility and duties of the staking providers thereunder. • Describe your plans with respect to the use of proceeds from staking rewards. • Disclose with specificity the bonding and unbonding periods associated with staking SOL, discuss how they affect liquidity and disclose the material terms of any policies and procedures you have in place to manage liquidity in this regard. 6. Please expand your disclosure to describe the policies and procedures you have in place or intend to adopt that govern when you exchange cash for crypto assets and when you monetize your crypto assets. Disclose whether you have policies or will establish policies governing the percentage of your treasury holdings that will be SOL. In addition, please disclose whether you intend to hedge your exposure to SOL and, if so, please describe your hedging strategy. Further, provide related risk factor disclosure, if material and to the extent applicable. 7. On page 14, you disclose that you "rely on various counterparties which includes, among others, Kraken, BitGo and Galaxy, to safeguard [your] digital asset holdings and execute trading on [your] behalf." Please supplementally confirm whether you have disclosed the identities of the material counterparties in this regard. With respect to each material counterparty, please describe the material terms of your agreement(s), including, without limitation, the term and termination provisions, and file the same as exhibits to your registration statement, if required by Item 601 of Regulation S-K. For any material counterparty that provides custodial services for your crypto assets, please also disclose: • The proportion of private keys that are held in hot, warm or cold storage; • Whether your assets are held in segregated accounts; • The identity of entities that have access to the custodied assets; • Whether any entity is responsible for verifying the existence of your crypto assets; • Whether and to what extent the third-party custodian carries insurance for any losses of the crypto assets it custodies for you; and • Where the custodian is chartered and how it is regulated. 8. We note your disclosure on page 14 that, "Kraken accounts for approximately 95% of our trading volume and approximately 30% of our digital assets holding are at both BitGo and Galaxy." Please revise to clarify the approximate percentage of your crypto asset holdings that are held at each material third party custodian, respectively. Solana Network, page 15 9. Please revise this section to provide greater detail describing SOL and the Solana blockchain, including: • The market capitalization and average daily trading volume of SOL; • The past and current supply of SOL; • The launch date of SOL and the Solana blockchain; and • The governance of the Solana blockchain. 10. We note your disclosure that the Solana network enables users to instantly send money globally, trade digital assets, utilize smart contracts, and buy or sell fungible and non-fungible tokens. Please revise to quantify or otherwise describe the nature and level of activity for each of these identified use cases, and quantify the number of active developers on the Solana network as of the most recent practicable date, to the extent known.

DFDV answered
has revised the disclosure on page 13 of Amendment No. 1. Read in the reply ↗
Our Company · Digital Asset Treasury Strategy, page 1
SEC asked (1)
You disclose that your new treasury policy updated your treasury management to "include digital assets, starting with SOL" and that "[m]anagement intends to focus on accumulating digital assets, focusing on SOL, and holding it long-term." Please expand to discuss your intentions to acquire other crypto assets, if any.
Rest of the question

To the extent you intend to acquire a material amount of other crypto assets, please add a section that addresses the characteristics of such crypto assets and the network on which they exist as well as any material risks related to your investment therein. If management does not currently have any such plans, please so state.

DFDV answered
The Company respectfully acknowledges the Staff’s comment and has revised the disclosure on pages 1 and 26 of Amendment No. 1. Read in the reply ↗
Digital Asset Treasury Strategy Revenue, page 2
SEC asked (2)
We note your disclosure that "[w]e derive revenue from our digital asset treasury strategy through delegating a portion of our digital asset holdings with third-party validators… Additionally, we earn validator revenue from participating in the Solana network through creating and validating transactions using our owned validators." Please revise to address the following points: • Quantify the portions of your crypto
Rest of the question

asset holdings that are allocated to your owned validator nodes and to third-party nodes, respectively. • Expand your disclosure to quantify the costs of operating your own validator nodes and address how and whether such operations have a material impact on your profitability. • Quantify the amount of SOL that is staked to your owned validator nodes by third parties.

DFDV answered
The Company respectfully acknowledges the Staff’s comment and has revised the disclosure on pages 2, 26 and 27 of Amendment No. 1. Read in the reply ↗
Digital Asset Treasury Strategy Revenue, page 2
SEC asked (3)
We note your disclosure that "[i]n exchange for staking our digital assets, we receive approximately 10% of the validators' total earned rewards in the form of SOL, net of commission fees." Please revise to discuss how such amount that you receive is determined.
Rest of the question

Also, please revise to explain how the validators' total earned rewards in the form of SOL is determined and calculated and quantify the approximate amount of the validators' commission fees you reference.

DFDV answered
The Company respectfully acknowledges the Staff’s comment and has revised the disclosure on pages 2 and 26 of Amendment No. 1 to clarify how rewards from validators are determined and the approximate commission fees that the Company pays. Read in the reply ↗
Description of Our Segments · Digital Asset Treasury Strategy, page 26
SEC asked (4)
Please expand your disclosure to describe your plan of operation for the next 12 months by disclosing: • The amount and proportions of SOL and/or other crypto assets you have purchased or intend to purchase; • The amount of capital you intend to raise through equity issuances and debt financing for such acquisitions.
Rest of the question

In this regard, we note your disclosure on page 27 that you use proceeds primarily from financing activities that consist of equity issuances and debt financing to acquire SOL; and • An estimated timeline for building your digital asset treasury over this time period. We note your disclosure that "[w]e delegate ('stake') a portion of our digital assets, primarily locked SOL, with third party validators… In some cases, we jointly own and operate validators alongside ecosystem partners to further align our treasury strategy with the broader Solana network." Please revise to provide a materially complete description of your staking program. In this regard, please address each of the following points with respect to your (i) delegated staking activities with third party providers and (ii) staking activities conducted through your owned validators that you operate, as applicable: • State whether you have any target percentage of your SOL holdings that you stake. • Describe in greater detail the mechanics of the staking process. 5. • Disclose the material terms of your agreements with your staking providers, and summarize the responsibility and duties of the staking providers thereunder. • Describe your plans with respect to the use of proceeds from staking rewards. • Disclose with specificity the bonding and unbonding periods associated with staking SOL, discuss how they affect liquidity and disclose the material terms of any policies and procedures you have in place to manage liquidity in this regard. 6. Please expand your disclosure to describe the policies and procedures you have in place or intend to adopt that govern when you exchange cash for crypto assets and when you monetize your crypto assets. Disclose whether you have policies or will establish policies governing the percentage of your treasury holdings that will be SOL. In addition, please disclose whether you intend to hedge your exposure to SOL and, if so, please describe your hedging strategy. Further, provide related risk factor disclosure, if material and to the extent applicable. 7. On page 27, you disclose that you "rely on various counterparties which includes, among others, Kraken, BitGo and Galaxy, to safeguard [your] digital asset holdings and execute trading on [your] behalf." Please supplementally confirm whether you have disclosed the identities of the material counterparties in this regard. With respect to each material counterparty, please describe the material terms of your agreement(s), including, without limitation, the term and termination provisions, and file the same as exhibits to your registration statement, if required by Item 601 of Regulation S-K. For any material counterparty that provides custodial services for your crypto assets, please also disclose: • The proportion of private keys that are held in hot, warm or cold storage; • Whether your assets are held in segregated accounts; • The identity of entities that have access to the custodied assets; • Whether any entity is responsible for verifying the existence of your crypto assets; • Whether and to what extent the third-party custodian carries insurance for any losses of the crypto assets it custodies for you; and • Where the custodian is chartered and how it is regulated. 8. We note your disclosure on page 27 that, "Kraken accounts for approximately 95% of our trading volume and approximately 30% of our digital assets holding are at both BitGo and Galaxy." Please revise to clarify the approximate percentage of your crypto asset holdings that are held at each material third party custodian, respectively. Solana Network, page 28 9. Please revise this section to provide greater detail describing SOL and the Solana blockchain, including: • The market capitalization and average daily trading volume of SOL; • The past and current supply of SOL; • The launch date of SOL and the Solana blockchain; and • The governance of the Solana blockchain. 10. We note your disclosure that the Solana network enables users to instantly send money globally, trade digital assets, utilize smart contracts, and buy or sell fungible and non-fungible tokens. Please revise to quantify or otherwise describe the nature and level of activity for each of these identified use cases, and quantify the number of active developers on the Solana network as of the most recent practicable date, to the extent known.

DFDV answered
The Company respectfully acknowledges the Staff’s comment and has revised the disclosure on page 26 of Amendment No. 1. Read in the reply ↗
Form 10-K for the Fiscal Year Ended December 31, 2024

2025-05-13 to 2025-05-21 · 1 question · 1 letter from the SEC, 1 from the company
Review closed 2025-05-21
Controls
Item 9A. Controls and Procedures, page 67
SEC asked
You disclose that you did not provide management's assessment of internal control over financial reporting ("ICFR") due to a transition period established by the Commission. Instruction 1 to Item 308 of Regulation S-K permits management to exclude its assessment of ICFR only in its first annual report filing and this is your second Form 10-K.
Rest of the question

Accordingly, please amend your Form 10-K to include management’s report on ICFR as of December 31, 2024, which should comply with the requirements of Item 308(a) of Regulation S-K. As it relates to your assessment, we note your disclosure concluding ineffectiveness of disclosure controls and procedures and the existence of a material weakness. The amended filing should also include updated and complete certifications pursuant to Item 601(b)(31), including ICFR language, and Item 601(b)(32) of Regulation S-K. For example, we note that your currently filed certifications omit certification 4(b) of Item 601(b)(31). In addition, ensure compliance in your future filings on both Forms 10-K and 10-Q. To the extent needed, please also refer to the Division of Corporation Finance: Sarbanes- Oxley Act of 2002 - Frequently Asked Questions pertaining to Section 302. In closing, we remind you that the company and its management are responsible for the accuracy and adequacy of their disclosures, notwithstanding any review, comments, action or absence of action by the staff.

DFDV answered
The Company acknowledges the Staff’s comment and advises the Staff that the Company has concurrently filed Amendment No. 1 on Form 10-K/A to amend its Original 10-K to address the Staff’s comment.

The Company further advises the Staff that the Company’s Quarterly Report on Form 10-Q for the quarterly period ended March 31, 2025 contains disclosure and certifications consistent with the Staff’s comment, and the Company will ensure compliance in its future filings on Forms 10-K and 10-Q.

We hope that the foregoing has been responsive to the Staff’s comments.
Rest of the answer

Please direct any questions or comments regarding the foregoing to Ross D. Carmel, Esq. of Sichenzia Ross

Ference Carmel LLP at (646) 838-1310 or Joseph Onorati, Chief Executive Officer to the Company at (408) 256-0347.

Read in the reply ↗
In its next report

First report after the company's reply of 2025-05-16: 10-Q filed 2025-08-14 ↗, against the 10-Q filed 2024-11-07 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Also in this review: closing letter, 2025-05-21

Form S-3

2024-08-19 to 2024-08-27 · 5 questions · 1 letter from the SEC, 1 from the company
No closing letter
Risk factors
SEC asked (1)
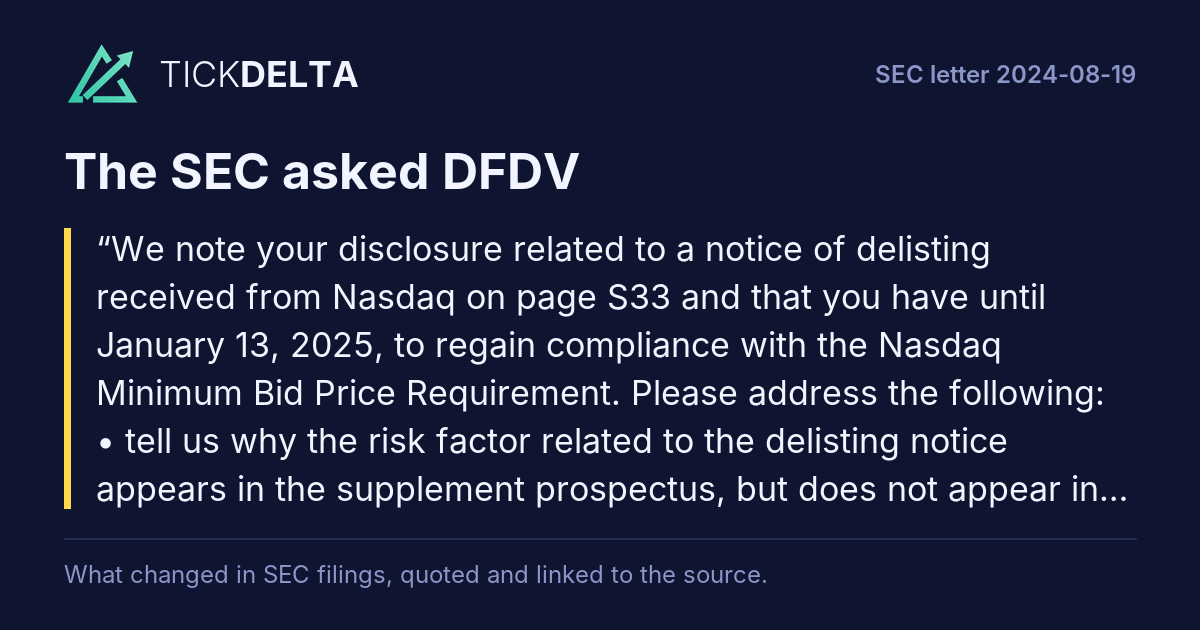
We note your disclosure related to a notice of delisting received from Nasdaq on page S33 and that you have until January 13, 2025, to regain compliance with the Nasdaq Minimum Bid Price Requirement. Please address the following: • tell us why the risk factor related to the delisting notice appears in the supplement prospectus, but does not appear in the delayed shelf offering prospectus, and how you plan to inform
Rest of the question

investors not participating in the at-the-market offering of the Nasdaq delisting risk; • tell us how you plan to monitor and, if needed, terminate the at-the-market offering if you are not able to comply with Nasdaq Minimum Bid Price Requirement in a timely manner; and • revise the prospectus to disclose material risks to investors in the at-the-market offering related to possible Nasdaq delisting.

DFDV answered
The Company acknowledges the Staff’s comment and update(s) the Staff, as follows:

· The Company has updated the current section ‘Risk

Factors’ in the shelf offering prospectus and in the prospectus supplement, ensuring adequate disclosure related to the Nasdaq delisting notice. Additionally, the Company will ensure that each prospectus supplement filed hereafter maintains and/or includes the said disclosure

(and any updates thereto), ensuring adequate notice to prospective investors to the Company’s securities.

· The Company was granted an initial 180-day period expiring on January 13,
Rest of the answer

2025 to regain compliance with the Nasdaq’s Minimum Bid Price Requirement and may be eligible for an additional

180-calendar day compliance period such date. The Company is currently exploring its options to achieve compliance prior to the expiry of the initial 180-calendar day period and intends to seek stockholder approval for a reverse-stock split prior to the expiry of the initial

180-calendar day period. Additionally, the Company will terminate its current shelf offering and the at-the-market offering thereunder, if needed, if the Company is not able to regain compliance with the Nasdaq Minimum Bid Price Requirement in accordance with the time provided therefor by Nasdaq.

· The Company has updated the prospectus to disclose material risks to investors in the at-the-market offering related to possible Nasdaq delisting.

Read in the reply ↗
SEC asked (2)
Given recent decline in your stock price and the limitation of selling no more than onethird of all your common voting and nonvoting equity held by non-affiliates, please tell us how you plan to monitor that the at-the-market offering sales agent does not exceed the maximum number of shares you can sell in the offering. Refer to General Instruction I.B.6(a) to Form S-3.
DFDV answered
The Company acknowledges the Staff’s comment and notes that the current at-the-market offering is up to the amount provided and is based on assumptions as of the initial date of filing. The Company would continue to comply with General Instruction I.B.6(a) to Form S-3, and notes that the proposed at-the-market offering and any future offerings would be conducted after consultation with the relevant stakeholders, ensuring the Company does not exceed the maximum number of shares that can be sold. Read in the reply ↗
SEC asked (3)
Please note that under General Instruction I.B.6(c), you are required to have at least one class of common equity securities listed and registered on a national securities exchange and your current Form S-3 eligibility depends on maintaining a listing on Nasdaq. You also disclose that you received a delisting notice from the exchange.
Rest of the question

Please tell us your plans as to this shelf offering in the event that your securities are delisted from Nasdaq.

DFDV answered
As noted in the third bullet of the Company’s response to Comment #1 above, in case the Company is delisted from Nasdaq, the Company will terminate its current shelf offering and the at-the-market offering thereunder. Read in the reply ↗
Cover Page
SEC asked (4)
Due to the recent decline in your stock price and the limitation of selling no more than one-third of all your common voting and nonvoting equity held by non-affiliates, please update the disclosure on the cover page relating to the market value of your common stock held by non-affiliates.
DFDV answered
The Company acknowledges the Staff’s comment and notes that the Company has made the requested changes.

Risk Factors, Read in the reply ↗
Risk Factors, page 9
SEC asked (5)
Please add a separately captioned risk factor here and in the risk factors section starting on page S-11 to disclose the dilutive effect of this offering and the continued downward pressure on your market price. In this regard, we note that you have received a notice from Nasdaq relating to possible delisting after your stock price declined below $1.00 per share.
DFDV answered
The Company acknowledges the Staff’s comment and notes that the Company has made the requested changes in both Risk Factor sections of the Registration

Statement, and in the prospectus supplement.

We hope that the foregoing has been responsive to the Staff’s comments. Read in the reply ↗

Form S-1

2023-05-04 to 2023-07-19 · 4 questions · 2 letters from the SEC, 4 from the company
No closing letter
RevenueResults discussion (MD&A)
Pre-effective Amendment No. 2 to Registration Statement on Form S-1 filed April 17, 2023 · The Offering, page 9
SEC asked (1)
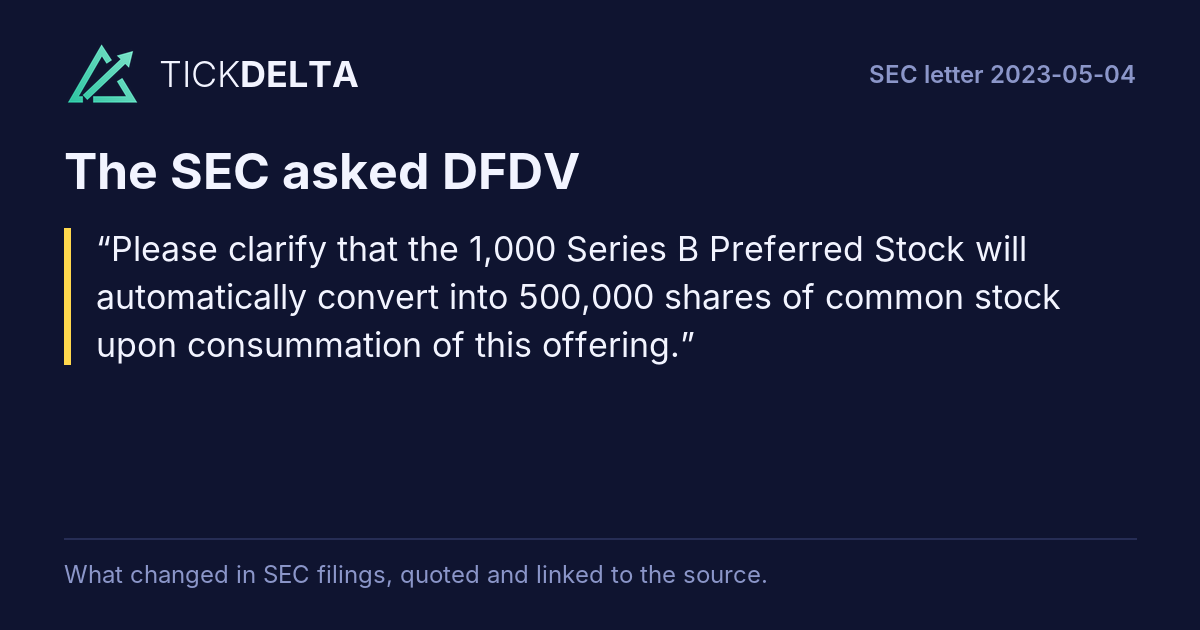
Please clarify that the 1,000 Series B Preferred Stock will automatically convert into 500,000 shares of common stock upon consummation of this offering.
DFDV answered
Please be advised that we have revised the registration statement to include an additional disclosure in our offering summary, clarifying that the 1,000 Series

B Preferred Stock, issued on April 14, 2023, will automatically convert into 500,000 shares of common stock upon consummation of this offering. Read in the reply ↗
Report of Independent Registered Public Accounting Firm, page F-3
SEC asked (2)
Please note that a signed, dated, and unrestricted auditor´s report must be included in the filing prior to effectiveness. See Rule 2-02 of Regulation S-X. Please make sure the audit report and auditor consent include the proper date. It appears that both currently reference 2022.
DFDV answered
Per the Staff’s comment, please note that we have added and included a signed, dated, and unrestricted auditor´s report from the Company’s independent registered public accounting firm, dbbmckennon, dated April 5, 2023, and have added the dated auditor consent as Exhibit 23.1 to Amendment No. 3. Read in the reply ↗
Notes to Financial Statements · Note 5. Future Equity Obligations, page F-13
SEC asked (3)
We note your disclosure to, "See Note 3 for fair value disclosures" on page F-14. Please revise your next amendment to include the proper reference to "Note 4."
DFDV answered
In response to the Staff’s comment, the Company has revised the disclosure in Amendment No. 3 as follows: “As of December 31, 2022 and 2021, the fair value of SAFEs was $539,582 and $1,356,704, respectively. See Note 4 for fair value disclosures.”

We trust that the above is responsive to your comments. Read in the reply ↗
SEC asked
Please enhance your revenue discussion to disclose the number of transactions closed and average revenue per transaction for the periods present consistent with your revenue discussion for years ended December 31, 2022 and December 31, 2021, and discuss underlying changes in trends. Refer to Item 303(c) of Regulation S-K.
DFDV answered
Per the Staff’s comment, the Company has revised the disclosure.

We trust that the above is responsive to your comments. Read in the reply ↗

Also in this review: company letter, 2023-07-19, company letter, 2023-07-19

Form S-1

2022-06-01 to 2022-10-27 · 42 questions · 3 letters from the SEC, 0 from the company
No closing letter
Risk factorsResults discussion (MD&A)RevenueIncome taxesDerivatives and hedgingLegal and contingenciesAcquisitionsLiquidity and cash
SEC letter of 2022-06-01 ↗ no reply letter on EDGAR (the company may have answered in an amended filing)
Draft Registration Statement on Form S-1 Submitted on May 2, 2022 · Cover Page
SEC asked (1)
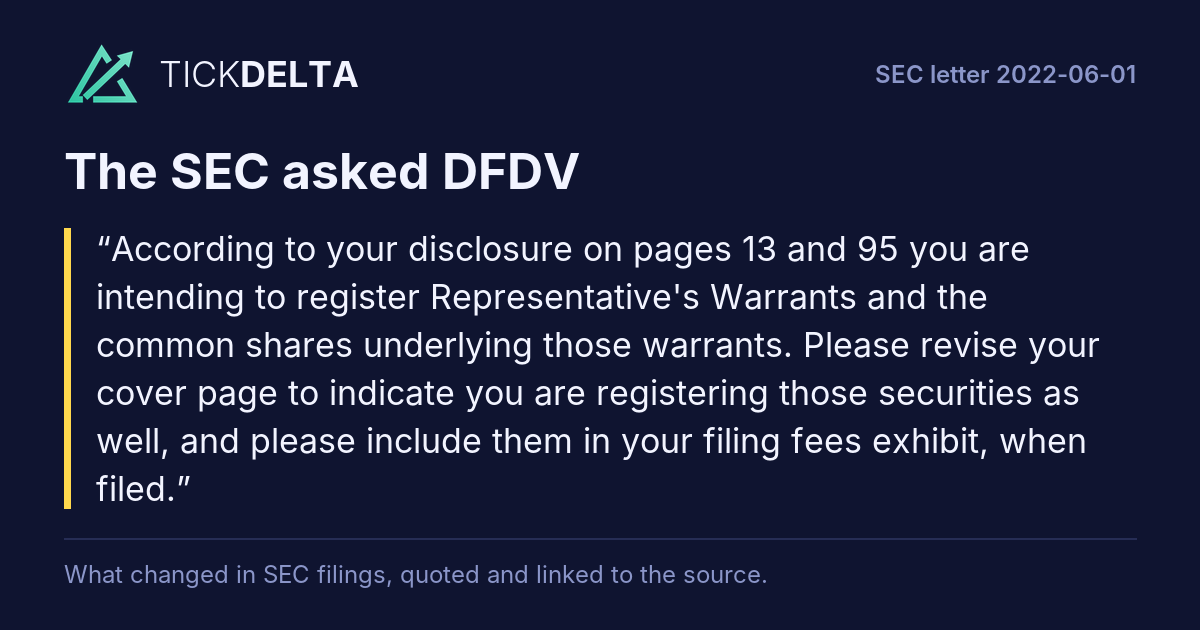
According to your disclosure on pages 13 and 95 you are intending to register Representative's Warrants and the common shares underlying those warrants. Please revise your cover page to indicate you are registering those securities as well, and please include them in your filing fees exhibit, when filed.
DFDV answered

No reply letter found.

Draft Registration Statement on Form S-1 Submitted on May 2, 2022 · Cover Page
SEC asked (2)
Please revise your cover page to better describe the different classes of stock you have that are currently outstanding. This would include disclosure related to what series/class/share ownership structure creates Mr. Janover's 99% voting interest in you.
Rest of the question

Also include disclosure that will indicate what said structure will be following the offering, specifically noting what the public will own in terms of series/class/shares of common stock and what voting and economic interests that will translate to for public shareholders. Prospectus Summary, page 1

DFDV answered

No reply letter found.

Draft Registration Statement on Form S-1 Submitted on May 2, 2022 · Cover Page
SEC asked (3)
In one of the opening paragraphs, please disclose your revenues and net losses for the most recent audited period to provide a snapshot of the company, and balance your summary disclosure.
DFDV answered

No reply letter found.

Our Future, page 6
SEC asked (4)
Please revise this section to indicate the percentage of your loan fees that come from lender networks and your borrower networks, or advise.
DFDV answered

No reply letter found.

Our Competitive Advantages, page 7
SEC asked (5)
Please provide support for your assertion that you "dominate Google for multifamily financing organic search results." Also provide more details on how you determined that Google "appreciates" what you do and how you are able to make that assertion.
Rest of the question

We also note your statements that you are democratizing commercial real estate finance and your marketplace is flexible (both on page 1), the statement on page 4 that the last significant innovation in commercial property finance was Microsoft excel, the statement that commercial lending is antiquated at page 5, and your statement on page 7 that it is hard to compete with you. Please revise to state these as beliefs or substantiate these claims to us.

DFDV answered

No reply letter found.

Our Competitive Advantages, page 7
SEC asked (6)
In order to balance the disclosures in this section, please include a section that describes your Competitive Disadvantages. This would be separate and apart from the summary of your risk factors that begin on page 9.
DFDV answered

No reply letter found.

The Offering, page 12
SEC asked (7)
Please revise this section to include disclosure regarding the outstanding shares of common and preferred stock both prior to and following the offering. Also ensure that your footnotes on page 14 properly refer to shares outstanding prior to and after the offering as appropriate.
DFDV answered

No reply letter found.

We are subject to concentration risk, page 20
SEC asked (8)
Please identify any lenders that generate more then 10% of your platform generated revenue. Our amended and restated certificate of incorporation and amended and restated bylaws designate a state or federal court..., page 42
DFDV answered

No reply letter found.

We are subject to concentration risk, page 20
SEC asked (9)
We note that your forum selection provision identifies the Court of Chancery of the State of Delaware as the exclusive forum for certain litigation, including any “derivative action.” Please disclose whether this provision applies to actions arising under the Exchange Act.
Rest of the question

In that regard, we note that Section 27 of the Exchange Act creates exclusive federal jurisdiction over all suits brought to enforce any duty or liability created by the Exchange Act or the rules and regulations thereunder.

DFDV answered

No reply letter found.

Risk Factors · Our current lack of geographic diversity, page 43
SEC asked (10)
We note your disclosure regarding geographic concentration in the U.S. Please revise to clarify if you have any regional geographic concentration, or within particular states, and any risks that may arise from such concentration.
DFDV answered

No reply letter found.

Use of Proceeds, page 47
SEC asked (11)
Please revise this section so that it is consistent with the disclosure you make in The Offering section regarding your intended use of proceeds. We also note the disclosure that the use of proceeds could include acquisitions. Please clarify if you have any current plans for acquisitions, including identifying the business, or advise. Refer to Item 504, Instruction 6, of Regulation S-K.
DFDV answered

No reply letter found.

Management's Discussion and Analysis of Financial Condition and Results of Operations · Comparison of the Year Ended December 31, 2021 and 2020, page 52
SEC asked (12)
Please conform your dollar/expense reference and presentation, e.g. stock based compensation of $330,314 instead of approximately $330 thousand.
DFDV answered

No reply letter found.

Management's Discussion and Analysis of Financial Condition and Results of Operations · Comparison of the Year Ended December 31, 2021 and 2020, page 52
SEC asked (13)
Please revise your next amendment to break out the material components of expense categories within Sales and Marketing and General and Administrative (e.g. salaries, commission and benefits, stock compensation expense). Consider using a tabular format to the extent it would helpful to investors. Also, discuss and analyze any known material trends, events, demands, commitments and uncertainties between periods.
Rest of the question

Refer to SEC Release 33-8350.

DFDV answered

No reply letter found.

Management's Discussion and Analysis of Financial Condition and Results of Operations · Comparison of the Year Ended December 31, 2021 and 2020, page 52
SEC asked (14)
Please revise your next amendment to classify 'Net Income' as 'Net Income (Loss)' where applicable.
DFDV answered

No reply letter found.

Growth Opportunities, page 67
SEC asked (15)
Please disclose in this section more information regarding how you determined that your future projections are fair and accurate.
DFDV answered

No reply letter found.

Competitive Advantage, page 70
SEC asked (16)
We note your disclosure that you have multiple websites. Please clarify if you have more than the two websites that you disclose and please list any others as well, or advise. Please briefly expand upon your discussion regarding involvement with cmbs financing. For instance, clarify if you securitize pools of loans, or just work with lenders that do cmbs financing.
DFDV answered

No reply letter found.

Employees, page 73
SEC asked (17)
Please indicate whether these 13 employees are full or part time employees. Also indicate here, as well as in the risk factor section the begins on page 37 the amount of time that Mr. Janover commits to you relative to his other multiple businesses.
DFDV answered

No reply letter found.

Current relationships and Related Party Transactions , page 84
SEC asked (18)
Please enhance your disclosure to clarify if the transactions with your Founder are integral to the operations of Janover Inc. and if so, how.
DFDV answered

No reply letter found.

Statements of Cash Flows, page F-7
SEC asked (19)
Please tell us and revise your disclosures as necessary, how proceeds from future equity obligations, net of financing fees of $191,851 reconciles to the Level 3 rollforward on page F-12 and the new and return of SAFEs of $50,000 and $115,662, respectively as disclosed on page F-13.
DFDV answered

No reply letter found.

Note 2. Summary of Significant Accounting Policies · Accounts Receivable, page F-9
SEC asked (20)
Please expand your disclosure related to 'Accounts Receivable' to provide the following: • the specific GAAP guidance you followed to form your accounting policy for your allowance for doubtful accounts; • if you have had any receivables charged-off in the periods presented; and • your charge-off policy under ASC 310-10-35-41.
DFDV answered

No reply letter found.

Stock-Based Compensation, page F-10
SEC asked (21)
Once you have an estimated offering price or range, please explain to us how you determined the fair value of the shares underlying your equity issuances and the reasons for any differences between the recent valuations of your shares leading up to the IPO and the estimated offering price. This information will help facilitate our review of your accounting for equity issuances including equity compensation.
DFDV answered

No reply letter found.

Notes to Financial Statements · Note 3. Fair Value Measurement, page F-11
SEC asked (22)
Please tell us, and revise your next amendment, to provide quantitative information about significant unobservable inputs used in the fair value measurement of future equity obligations. Please also separately disclose the new and return 2021 SAFE activity in the Level 3 rollfoward and disclose how you considered these and 2021 equity transactions in the SAFE fair value determination at December 31, 2021.
Rest of the question

Refer to ASC 820-10-50-2bbb(2).

DFDV answered

No reply letter found.

Note 4 Future Equity Obligations, page F-13
SEC asked (23)
Please tell us and revise your disclosures as necessary, how you accounted for the 2020 subscription receivable of $257,513, including how reflected in the Level 3 rollforward on page F-12.
DFDV answered

No reply letter found.

Note 6. Income Taxes, page F-16
SEC asked (24)
Please revise your next amendment to disclose the components of the net deferred tax liability or asset measured under ASC 740-10-30-5 as required by ASC 740-10-50. General
DFDV answered

No reply letter found.

Note 6. Income Taxes, page F-16
SEC asked (25)
Please provide us with supplemental copies of all written communications, as defined in Rule 405 under the Securities Act, that you, or anyone authorized to do so on your behalf, have presented or expect to present to potential investors in reliance on Section 5(d) of the Securities Act, whether or not you retained, or intend to retain, copies of those communications.
DFDV answered

No reply letter found.

Note 6. Income Taxes, page F-16
SEC asked (26)
Please provide us mockups of any pages that include any additional pictures or graphics to be presented, including any accompanying captions. Please keep in mind, in scheduling your printing and distribution of the preliminary prospectus, that we may have comments after our review of these materials.
DFDV answered

No reply letter found.

SEC letter of 2022-08-11 ↗ no reply letter on EDGAR (the company may have answered in an amended filing)
Cover Page
SEC asked (1)
We note your response to comment 2. Please revise the cover to include a discussion of any other rights or interests that Mr. Janover will have as a result of his preferred share ownership that will supersede the rights and interests of common stock holders.
Rest of the question

Please disclose that each share of Series A Preferred Stock is entitled to 10,000 votes on all matters on which common stock shall be entitled to vote, as applicable.

DFDV answered

No reply letter found.

The Current Industry Problem and Our Opportunity, page 1
SEC asked (2)
We note your response to comment 5. Please revise the disclosure in the bulleted points discussing the current commercial lending industry to state those are your beliefs regarding the industry or substantiate your claims.
Rest of the question

Please revise the footnote related disclosure in the last paragraph in this section so your registration statement includes all of the information without directing to a third party document that is not an exhibit.

DFDV answered

No reply letter found.

Risk Factors · There is ambiguity in our Simple Agreements for Future Equity, page 34
SEC asked (3)
Please further explain the terms of the SAFEs and why you believe the terms are uncertain and ambiguous, so that investors can assess the risk of whether the company will need to repay the purchase amount or issue shares of common stock. Please quantify in the risk factor the number of shares you may need to issue upon consummation of the offering.
Rest of the question

Our amended and restated certificate of incorporation and amended and restated bylaws designate a state or federal court, page 36

DFDV answered

No reply letter found.

Risk Factors · There is ambiguity in our Simple Agreements for Future Equity, page 34
SEC asked (4)
We note your response to our prior comment 9 and reissue in part. The heading to the risk factor seems to indicate that the exclusive forum is a state or federal court located within the State of Delaware, but the risk factor discussion seems to indicate that the Court of Chancery for the State of Delaware is the exclusive forum for certain actions, including any "derivative action." Please revise for consistency.
Rest of the question

Please also clarify if the exclusive forum provision applies to actions arising under the Securities Act. In that regard, we note that Section 27 of the Exchange Act creates exclusive federal jurisdiction over all suits brought to enforce any duty or liability created by the Exchange Act or the rules and regulations thereunder, and Section 22 of the Securities Act creates concurrent jurisdiction for federal and state courts over all suit brought to enforce any duty or liability created by the Securities Act or the rules and regulations thereunder. Please also provide disclosure of the exclusive forum provision under "Description of Securities," at page 74.

DFDV answered

No reply letter found.

Results of Operations · The Fiscal Year Ended December 31, 2021, compared to the Fiscal Year Ended December 31, 2020, page 47
SEC asked (5)
We note your response to prior comment 14 in our letter dated May 2, 2022. Please revise your next amendment to classify "Net Income" as "Net Income (Loss)" in the table on page 47 that provides certain selected financial information for the 2021 as compared to 2020.
DFDV answered

No reply letter found.

Competitive Advantages, page 61
SEC asked (6)
We note your response to comment 16. Please expand your discussion as to how your multiple websites work as part of your "top of funnel" universe in your market. If true, clarify that these multiple websites and search engine results are not directing customers to multiple products and services, but rather directing them to types of financings the lenders you work with offer.
Rest of the question

Also indicate how you are able to determine that you have "used [y]our formula to create multiple websites that perform very well on search engines."

DFDV answered

No reply letter found.

SEC letter of 2022-10-27 ↗ no reply letter on EDGAR (the company may have answered in an amended filing)
Cover Page
SEC asked (1)
We note the disclosure on the cover page that the Selling Shareholder shares will not be purchased by the underwriters in the underwritten offering. Please disclose the offering price for the Selling Shareholder shares. Refer to Item 501(b)(3) of Regulation S-K. We also note that the Selling Shareholder shares will not be sold until after the closing of this offering.
Rest of the question

Please advise us why you are including the selling shareholder offering in the same prospectus as your underwritten offering or have not elected to use a prospectus supplement for the selling shareholder offering.

DFDV answered

No reply letter found.

We are subject to concentration risk, page 17
SEC asked (2)
We refer to comment 8 in our letter dated June 1, 2022. In that comment we asked you to identify any lenders that generate more that 10% of your platform generated revenue. Your response and revised disclosure indicated that Arbor Realty Trust, Inc. and Greystone & Co. II LLC are two such lenders. In your registration statement filed on October 14, 2022, you have removed these lenders from this risk factor.
Rest of the question

We therefore reissue the comment asking you to identify any lenders that generate more that 10% of your platform generated revenue, or please explain to use why such lenders no longer meet this criteria.

DFDV answered

No reply letter found.

Capitalization, page 43
SEC asked (3)
You disclose that As Adjusted Capitalization reflects actual capitalization as of June 30, 2022 adjusted to reflect the issuance of 1,700,000 shares of common stock in the offering, after deducting underwriting discounts and commissions and estimated offering expenses payable by you which you estimate an to be approximately $9.17 million.
Rest of the question

Please enhance your disclosures to clarify how the increase in As Adjusted Total stockholder's equity of $10.77 million reconciles to the estimated proceeds.

DFDV answered

No reply letter found.

Dilution, page 45
SEC asked (4)
You disclose that concurrent with the effective date of the registration statement you will affect a 1-for-6.82 stock split and that share and per share information in the prospectus has been adjusted to reflect the stock split.
Rest of the question

Please clarify how 9,695,582 shares of common stock to be outstanding following the offering based on your common stock outstanding of 6,845,236 at June 30, 2022 reconciles to common stock outstanding on page F-21 based on activity disclosed on pages 44, 45, 52, F-28, II-2, including the 7,057,903 shares of common stock outstanding before the offering on page 9, and revise your disclosures accordingly. Further, please adjust all share amounts in the registration statement to reflect the stock split, including the financial statements for June 30, 2022, December 31, 2021 and December 31, 2020. Refer to SAB Topic 4.C. Changes in Capital Structure.

DFDV answered

No reply letter found.

Selling Stockholders, page 82
SEC asked (5)
We note your disclosure in the first paragraph regarding the possible resale by the Selling Shareholders of common stock. Please briefly explain here the transactions from which the Selling Shareholders originially received the options, SAFEs or shares, including the exemption relied upon.
Rest of the question

Please also include disclosure regarding your outstanding options and SAFEs under "Description of Securities," at page 86, or advise.

DFDV answered

No reply letter found.

Selling Stockholders, page 82
SEC asked (6)
We note that you have added a secondary offering of selling stockholders that you intend to commence "after the closing of this offering." Please provide us with your analysis as to whether the transaction should be viewed as a secondary offering eligible to be made on a shelf basis under Rule 415(a)(1)(i) or a primary, at-the-market offering being made pursuant to Rule 415(a)(4).
Rest of the question

Please include a discussion of the relationships of the investors with you and the fact that the shares you are seeking to register do not appear to have been issued yet, and tell us why the offering should not be viewed as an indirect, primary transaction and why the selling shareholders should not be viewed as underwriters. Refer to Interpretation 612.09 in our Securities Act Rules Compliance and Disclosure Interpretations.

DFDV answered

No reply letter found.

Selling Stockholders, page 82
SEC asked (7)
Please include a column in your table that shows the percentage of common stock that the selling shareholders will beneficially own after the completion of your primary offering, but before they have sold any of their shares.
DFDV answered

No reply letter found.

Selling Stockholders, page 82
SEC asked (8)
Please indicate here which, if any, of the selling shareholders are considered to be related parties.
DFDV answered

No reply letter found.

Note 2. Summary of Significant Accounting Policies · Stock-Based Compensation, page F-10
SEC asked (9)
The Staff references prior comment 21 in our letter dated June 1, 2022. Once you have an estimated offering price or range, please explain to us how you determined the fair value of the shares underlying your equity issuances and the reasons for any differences between the recent valuations of your shares leading up to the IPO and the estimated offering price.
Rest of the question

This information will help facilitate our review of your accounting for equity issuances including equity compensation.

DFDV answered

No reply letter found.

Exhibits
SEC asked (10)
We note the opinion in clause (ii) of Exhibit 5.1 that, "The Selling Stockholders Shares, having already been issued, are validly issued, fully paid and non-assessable." However on page 82 of your registration statement, you indicate the selling shareholders shares have not been issued. Please revise your disclosure and/or opinion as necessary.
DFDV answered

No reply letter found.

8 other letters: notices that a filing will not be reviewed, requests to declare a registration effective, and the like

From the SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), 26 letters filed since 2022-06-01. Questions and answers are matched by their numbers; topics come from words in each question. The reports are compared word for word (same form, before the first SEC letter against the first report after the company's reply). No AI.

Next in Owners and insiders Insider trades →

Work on DFDV in a spreadsheet: Excel workbook (a sheet per section, ten years by column, charts, links to the filings) · CSV. For a Google Sheet that stays up to date, paste =IMPORTDATA("https://tickdelta.com/company/DFDV/export.csv") into a cell.