Screener / SEC EDGAR /CIK 0001599617 /10-K filed Feb 26, 2026, compared with Feb 18, 2025 /Numbers from the XBRL of the 10-Ks
NYSE Industrials · Oilfield Equipment

DNOW Inc. DNOW

Compare with peers Embed
SEC comment letters, last 20 years

2 reviews of DNOW's filings by SEC staff

UPLOAD and CORRESP
Reviews 2 latest letter Nov 12, 2024
Questions asked 29 each answered in the company's own letter
No closing letter 1 reviews without a letter saying the staff completed it

When the SEC's staff reviews a filing, it writes to the company with numbered questions, and the company answers each one in a letter. SEC publishes the exchange once the review is over, at least 20 business days later. A question is not an accusation; most reviews end with the company adding detail to its next filing.

How the reviews went

Every review on EDGAR, from the first staff letter to the letter that closes it

  1. 1. Staff letters 3 UPLOAD
  2. 2. Questions in them 29 numbered comments
  3. 3. Company replies 3 CORRESP
  4. 4. Reviews closed 1 of 2 closing letter

Half the closed reviews took 23 days or less from the first letter to the closing letter.

Form 10-K for the Year Ended December 31, 2023

2024-11-12 to 2024-12-05 · 5 questions · 1 letter from the SEC, 1 from the company
Review closed 2024-12-05
Non-GAAP measuresLiquidity and cashIncome taxes
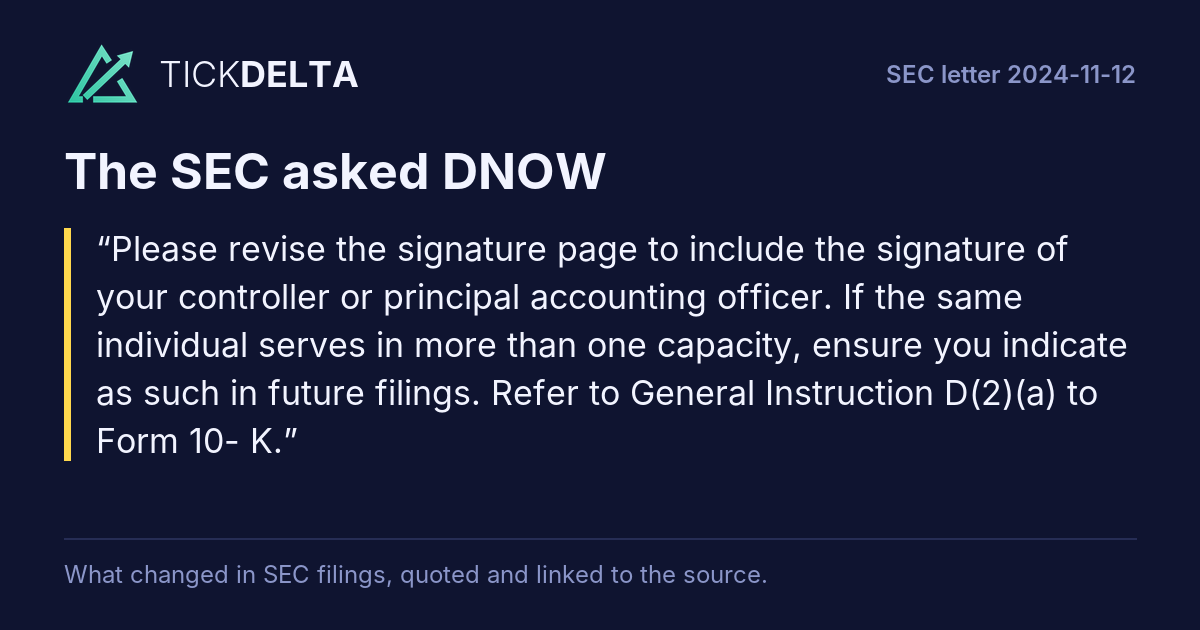
After reviewing your response to this letter, we may have additional comments. Signatures, page 44
SEC asked (1)
Please revise the signature page to include the signature of your controller or principal accounting officer. If the same individual serves in more than one capacity, ensure you indicate as such in future filings. Refer to General Instruction D(2)(a) to Form 10- K.
DNOW answered
The Company acknowledges the Staff’s request, and it will revise its future filings in accordance with General Instruction D(2)(a) to Form 10-K to include the signature of the Company’s controller or principal accounting officer. Presently, and for the avoidance of doubt, Mr. Mark Johnson, the Company’s Senior Vice President and Chief Financial Officer, serves as the Company’s principal financial officer and principal accounting officer. In future filings, Mr. Johnson’s signature will reference his status as principal financial officer and principal accounting officer.
Read in the reply
In its next report

First report after the company's reply of Nov 22, 2024: 10-K filed Feb 18, 2025 ↗, against the 10-K filed Feb 15, 2024 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Exhibit 99.1
SEC asked (2)
We note your discussion and presentation of the non-GAAP financial measure of EBITDA % excluding other costs. Please revise future filings, including your periodic reports, to also present the percentage calculated using the most directly comparable GAAP measure with equal or greater prominence. Refer to Item 10(e)(1)(i)(A) of Regulation S-K.
DNOW answered
The Company acknowledges the Staff’s request, and it will revise its future filings, including its periodic reports, to also present the percentage calculated using the most directly comparable GAAP measure with equal or greater prominence when presenting or discussing non-GAAP financial measures in accordance with Item 10(e)(1)(i)(A) of Regulation S-K.
Read in the reply
In its next report

First report after the company's reply of Nov 22, 2024: 10-K filed Feb 18, 2025 ↗, against the 10-K filed Feb 15, 2024 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Exhibit 99.1
SEC asked (3)
We note the President and CEO’s discussion of free cash flow. Please ensure that future presentations of this non-GAAP measure are accompanied by the disclosures required by Item 10(e)(1)(i) of Regulation S-K.
DNOW answered
The Company acknowledges the Staff’s request, and it will revise its future presentations of a non-GAAP measure to be accompanied by the disclosures required by Item 10(e)(1)(i) of Regulation S-K.
Read in the reply
In its next report

First report after the company's reply of Nov 22, 2024: 10-K filed Feb 18, 2025 ↗, against the 10-K filed Feb 15, 2024 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Exhibit 99.1
SEC asked (4)
Please ensure that you provide an explanation of the other adjustments to non-GAAP financial measures for each of the prior periods presented.
DNOW answered
The Company acknowledges the Staff’s request, and it will revise its future presentations to provide an explanation of the other adjustments to non-GAAP financial measures for each of the prior periods presented.
Read in the reply
In its next report

First report after the company's reply of Nov 22, 2024: 10-K filed Feb 18, 2025 ↗, against the 10-K filed Feb 15, 2024 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Exhibit 99.1
SEC asked (5)
To the extent material, please revise future presentations of non-GAAP measures to include income tax adjustments as a separate line item in your non-GAAP reconciliations and explain how the tax impact is calculated. Refer to Question 102.11 of the Non-GAAP Compliance and Disclosure Interpretations.
DNOW answered
The Company acknowledges the Staff’s request, and it will revise its future presentations of non-GAAP measures, to the extent material, to include income tax adjustments as a separate line item in the Company’s non-GAAP reconciliations and explain how the tax impact is calculated in accordance with Question 102.11 of the Non-GAAP Compliance and Disclosure Interpretations.
Read in the reply
In its next report

First report after the company's reply of Nov 22, 2024: 10-K filed Feb 18, 2025 ↗, against the 10-K filed Feb 15, 2024 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Also in this review: closing letter, 2024-12-05
Form 10-12B

2014-03-26 to 2014-04-23 · 24 questions · 2 letters from the SEC, 2 from the company
No closing letter
RevenueResults discussion (MD&A)Liquidity and cashSegmentsExecutive payRisk factorsClimateAcquisitionsNon-GAAP measuresInventoryDebtLegal and contingencies
General
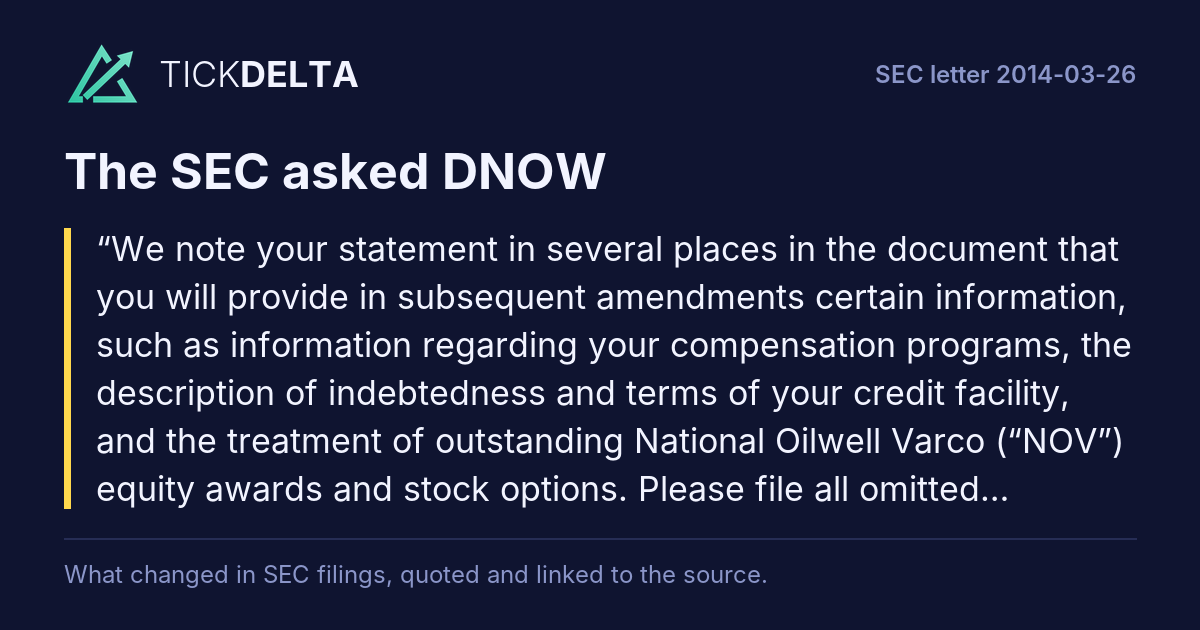
SEC asked (1)
We note your statement in several places in the document that you will provide in subsequent amendments certain information, such as information regarding your compensation programs, the description of indebtedness and terms of your credit facility, and the treatment of outstanding National Oilwell Varco (“NOV”) equity awards and stock options.
Rest of the question

Please file all omitted exhibits and provide other omitted disclosure as soon as possible. We will need adequate time to review and, if necessary, comment upon your disclosure.

DNOW answered
The Company has considered the comment and revised the disclosures on page 6, 7 and 45.
Read in the reply
Information Statement · Our Competitive Strengths, page 6
SEC asked (2)
We note your disclosure here that you are one of the “global market leaders” in the distribution of MRO products to the energy market. You make similar disclosures regarding your leadership position elsewhere in your information statement, including on pages 7 and 45. Please provide the basis for these statements.
DNOW answered
The Company’s

Compensation Committee will determine the performance metric or metrics applicable to the equity or other incentive awards granted to the Company’s executives. To ensure investors can understand the Company’s incentive awards and the payouts made thereunder, the Company will disclose the relevant performance metrics and, upon completion of the performance period or periods, disclose the Company’s actual performance and, as applicable, the actual performance of any comparator indices or other similar benchmarks.
Read in the reply
Our Business Strategy, page 7 · Questions and Answers about the Separation and the Distribution, page 9
SEC asked (3)
Please add a question and answer discussing the estimated costs you expect to incur in connection with the separation and distribution.
DNOW answered
The separation of NOV’s distribution business into NOW will not trigger change in control payments to any executive officer. We have added disclosure on page 106 of our amended information statement confirming same.

Financial Statements of NOW Inc.
Read in the reply
Risks Relating to Our Business, page 21
SEC asked (4)
We note your disclosure on page 24 under the risk factor titled “If steel prices rise...” that you manufacture many of your products from steel. To help the investor assess the magnitude of this risk, please disclose the proportion of overall revenue derived from your sale of products manufactured from steel.
DNOW answered
The Company has considered the comment and revised the disclosure on page F-24.

In providing this response letter to the Staff, the Company acknowledges that (i) the Company is responsible for the adequacy and accuracy of the disclosure in the above-referenced filing, (ii) Staff comments or changes to disclosure in response to Staff comments do not foreclose the Commission from taking any action with respect to the above-referenced filing, and (iii) the Company may not assert Staff comments as a defense in any proceeding initiated by the Commission or any person under the federal securities
Rest of the answer

laws of the United States.

If you or any member of the Staff has any questions regarding the responses set forth herein, please contact the undersigned at (713) 346-7607.

Read in the reply
Cautionary Statement Concerning Forward-Looking Statements, page 32
SEC asked (5)
It does not appear appropriate to suggest that the word ''will'' identifies the uncertainties associated with forward-looking statements. Please revise accordingly.
DNOW answered

No numbered answer found in the reply. Read the reply ↗

Management’s Discussion and Analysis, page 62
SEC asked (6)
Your MD&A should provide a disclosure of all material trends or uncertainties that have reasonably affected or are likely to impact your operating results. In this regard, please consider supplementing your discussion of rig counts and hydrocarbon prices with a discussion of the trends in steel prices. We note your related disclosure on pages 24, 25, 66, and 79.
DNOW answered

No numbered answer found in the reply. Read the reply ↗

Results of Operations, page 66
SEC asked (7)
Please revise and expand your disclosure for each period presented to quantify underlying activities that generated income statement variances. For example, please quantify the year-over-year changes in revenues and costs attributable to the Wilson and CE Franklin acquisitions versus other factors, if material. Your revised disclosure should address causal factors impacting each income statement line item.
Rest of the question

Please also consider this comment as it relates to the pro forma analysis beginning on page 70 of your filing. Refer to Item 303(A)(3) of Regulation S-K and related guidance.

DNOW answered

No numbered answer found in the reply. Read the reply ↗

Results of Operations, page 66
SEC asked (8)
Please expand this section to include a discussion of your operating expenses. In this regard, we note the disclosure on page F-4 that you incurred $3.9 billion in cost of revenue during the fiscal year ended December 31, 2013. Describe any significant components of your expenses that are necessary to an understanding of your operating results.
DNOW answered

No numbered answer found in the reply. Read the reply ↗

Results of Operations, page 66
SEC asked (9)
Your discussion under this section should provide enough detail to allow investors to gauge whether your past operating results are indicative of future performance. In this regard, we note your attribution of operating profit percentage gains on page 69 to “synergies realized in the business.” Please explain the nature of these synergies.
DNOW answered

No numbered answer found in the reply. Read the reply ↗

Pro Forma Results of Operations, page 70
SEC asked (10)
We note that you have provided a supplemental discussion regarding operating results based upon pro forma information. Please expand your disclosure to explain why you believe the presentation of a pro forma discussion is useful and identify any potential risks associated with using such a presentation.
Rest of the question

In addition, please provide narrative disclosure explaining the adjustments made to calculate the pro forma information presented.

DNOW answered

No numbered answer found in the reply. Read the reply ↗

Pro Forma Results of Operations, page 70
SEC asked (11)
In connection with the preceding comment, we note that you have provided pro forma analysis comparing the fiscal years ended December 31, 2012 and December 31, 2011. However, it appears that an analysis for these periods should be limited to a discussion of pro forma revenue and costs of revenue. Please revise your disclosure accordingly.
DNOW answered

No numbered answer found in the reply. Read the reply ↗

Non-GAAP Financial Measures and Reconciliations, page 73
SEC asked (12)
Please revise your disclosure to explain the nature of the “Other costs” that are added to GAAP operating profit as part of the non-GAAP reconciliation presented in your filing. Refer to Item 10(e)(i)(B) of Regulation S-K.
DNOW answered

No numbered answer found in the reply. Read the reply ↗

Liquidity and Capital Resources, page 74
SEC asked (13)
Please expand your discussion of capital expenditures to disclose how much you have spent and anticipate spending in 2014 and how you intend to finance such expenditures following your separation from NOV.
DNOW answered

No numbered answer found in the reply. Read the reply ↗

Liquidity and Capital Resources, page 74
SEC asked (14)
You state that “Net cash flows provided by operating activities in 2013 were $317 million, up from $12 million used in 2012 driven by net income of $147 million, a $23 million reduction in receivables as a result of improved collections and a decrease of $158 million in inventory as management actively reduced inventory levels in line with lower market volumes.” Please expand your discussion to better explain the
Rest of the question

variance in net cash provided by operating activities in 2013 and the net cash used in operating activities in 2012. In this regard, we note that net income in 2012 was $108 million, such that the difference in net income, reduction in receivables and decrease in inventory would not adequately explain the $329 million variance between 2012 and 2013.

DNOW answered

No numbered answer found in the reply. Read the reply ↗

Liquidity and Capital Resources, page 74
SEC asked (15)
Once you enter into the credit facility contemplated in the “Description of Indebtedness” section on page 95, please be sure to expand this section to discuss any terms or restrictive covenants that may have a material impact on your ability to fulfill your commitments for capital expenditures.
DNOW answered

No numbered answer found in the reply. Read the reply ↗

Liquidity and Capital Resources, page 74
SEC asked (16)
You state on page 75 your belief that “cash on hand, cash generated from operations and amounts available under our credit facilities will be sufficient to fund operations . . .” As it appears you currently intend to secure only one credit facility, please revise this statement. Certain Relationships and Related-Party Transactions, page 86 Financial Statements of NOW, Inc.
DNOW answered

No numbered answer found in the reply. Read the reply ↗

Combined Statements of Income, page F-4
SEC asked (17)
Disclosure in your filing regarding your Energy Branches states that you have a team of technical professionals who provide expertise in applied products, and applications, such as artificial lift systems, coatings, electrical products, gas meter runs, and valve actuation.
Rest of the question

Please tell us whether you offer services to your customers and explain your consideration of the requirement to separately present revenues from the sale of tangible products and revenues from services on the face of your statement of income. Refer to Rules 5-03(b)(1) and 5-03(b)(2) of Regulation S-X.

DNOW answered

No numbered answer found in the reply. Read the reply ↗

Note 2 - Summary of Significant Accounting Policies, page F-8 · Revenue Recognition, page F-10
SEC asked (18)
Please revise to provide revenue recognition policy disclosure tailored to your business. Your revised policy should address your policies with regard to both products and services offered to your customers. With regard to product sales, please address sales from supply stores, sales from your website, and sales from dedicated customer on-site locations. Refer to SAB Topic 13.
DNOW answered

No numbered answer found in the reply. Read the reply ↗

Note 9 – Commitments and Contingencies, page F-15
SEC asked (19)
You refer here to “the specific case referred to above,” but it is not clear to which case you are referring. Please revise your disclosure for clarity.
DNOW answered

No numbered answer found in the reply. Read the reply ↗

Note 12 – Business Segments and Primary End-Market, page F-21
SEC asked (20)
We note that you have provided disclosure of revenues by primary end-market (i.e., Energy Branches and Supply Chain locations). Please provide us with your analysis of FASB ASC 280-10-50-40 to explain your basis for grouping multiple products offered to your customers.
Rest of the question

In this connection, it appears that similar products are offered by both your Energy Branches and Supply Chain locations such as pipe, valves, fittings, tools, and safety supplies.

DNOW answered

No numbered answer found in the reply. Read the reply ↗

SEC letter of Apr 18, 2014 ↗ no reply letter on EDGAR
Exhibit 99.1 · Our Competitive Strengths, page 6
SEC asked (1)
We note your response to our prior comment 2 and your amended disclosure on pages 6, 7, and 45. However, the three specific sources you cite in your response refer to your position in the industrial distribution market, such as with respect to the HVAC and PVF markets. Please clarify how these sources demonstrate your position in the energy market or your position as a leading provider of supply chain solutions.
Rest of the question

Otherwise, please revise to limit your claims accordingly, or provide us with sources specifically supporting your claims.

DNOW answered

No reply letter found.

Compensation Discussion and Analysis, page 85 · Long-Term Incentive Compensation, page 95
SEC asked (2)
We note in your discussion regarding NOV’s 2013 long-term incentive compensation that the performance share awards are subject to two separate performance metrics: 50% with a TSR (total shareholder return) goal and 50% with an internal ROC goal (return on capital). We further note that payout levels are tied to NOV’s performance when compared with the performance of the members of the OSX index.
Rest of the question

To the extent that NOW’s compensation programs will have performance metrics, please be sure to disclose the specific performance metric goals as well as NOW’s specific performance so that investors may understand the payouts. For example, if NOW will use metrics similar to those used by NOV, please disclose the TSR performance of the members of the OSX index as well as the TSR performance of NOW. Employment Contracts and Termination of Employment and Change-in-Control Arrangements,

DNOW answered

No reply letter found.

Compensation Discussion and Analysis, page 85 · Long-Term Incentive Compensation, page 95
SEC asked (3)
Please clarify whether the separation of NOV’s distribution business into NOW would trigger change in control payments to any of the executive officers. Financial Statements of NOW Inc.
DNOW answered

No reply letter found.

Note 12 – Business Segments and Primary End-Market, page F-21
SEC asked (4)
We note your response to comment 20 in our letter dated March 26, 2014 and the related revisions to your filing. Please revise the disclosure of sales mix by principal product categories to show the dollar amount of revenue from the sale of each product. Refer to FASB ASC 280-10-50-40.
DNOW answered

No reply letter found.

Also in this review: company letter, Apr 8, 2014

Letters without questions

Other letters

UPLOAD and CORRESP
5 other letters: notices that a filing will not be reviewed, requests to declare a registration effective, and the like

From the SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), 12 letters filed since 2014-03-26. Questions and answers are matched by their numbers; topics come from words in each question. The reports are compared word for word (same form, before the first SEC letter against the first report after the company's reply). No AI.

Sources

The SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), matched question by question. No AI.

Also

Filings: the letters in the filing list.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/DNOW/export.csv") into a cell.

Next in Owners and insiders:Insider trades
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.