Leonardo DRS, Inc. DRS
New risk paragraphs, branching off last year
Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Mar 3, 2025. A box jumps to the paragraph as filed, below.
Paragraphs with nothing like them in last year's 10-K
12 paragraphs in Risk Factors of the 10-K filed Feb 27, 2026 with nothing like them in the 10-K filed Mar 3, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.
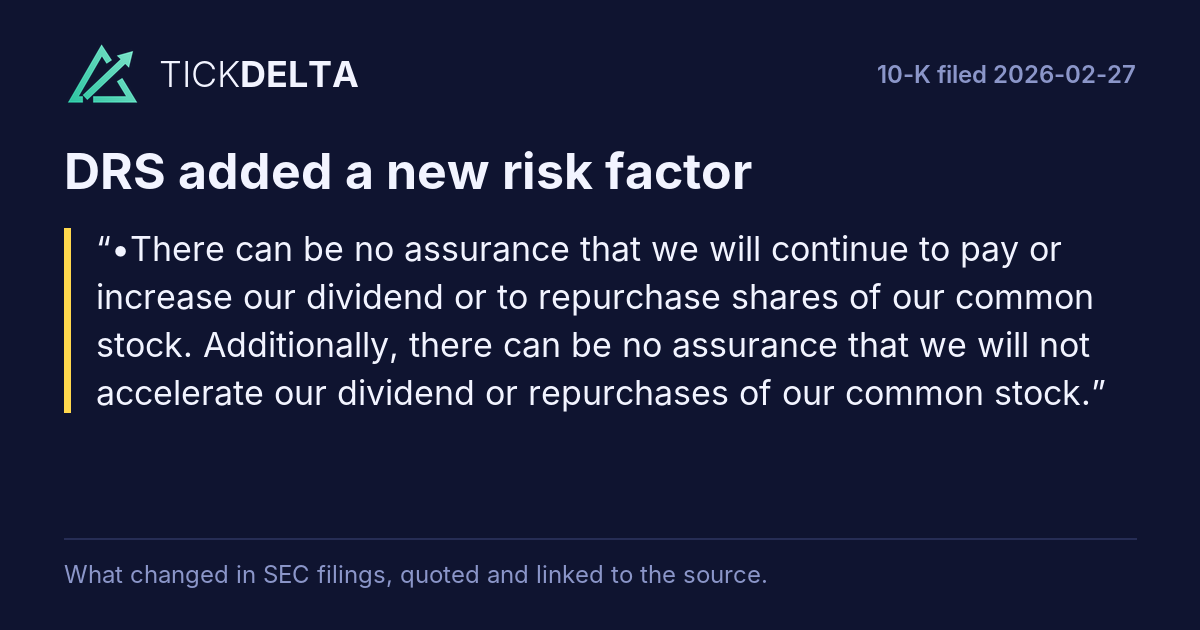
•There can be no assurance that we will continue to pay or increase our dividend or to repurchase shares of our common stock. Additionally, there can be no assurance that we will not accelerate our dividend or repurchases of our common stock.
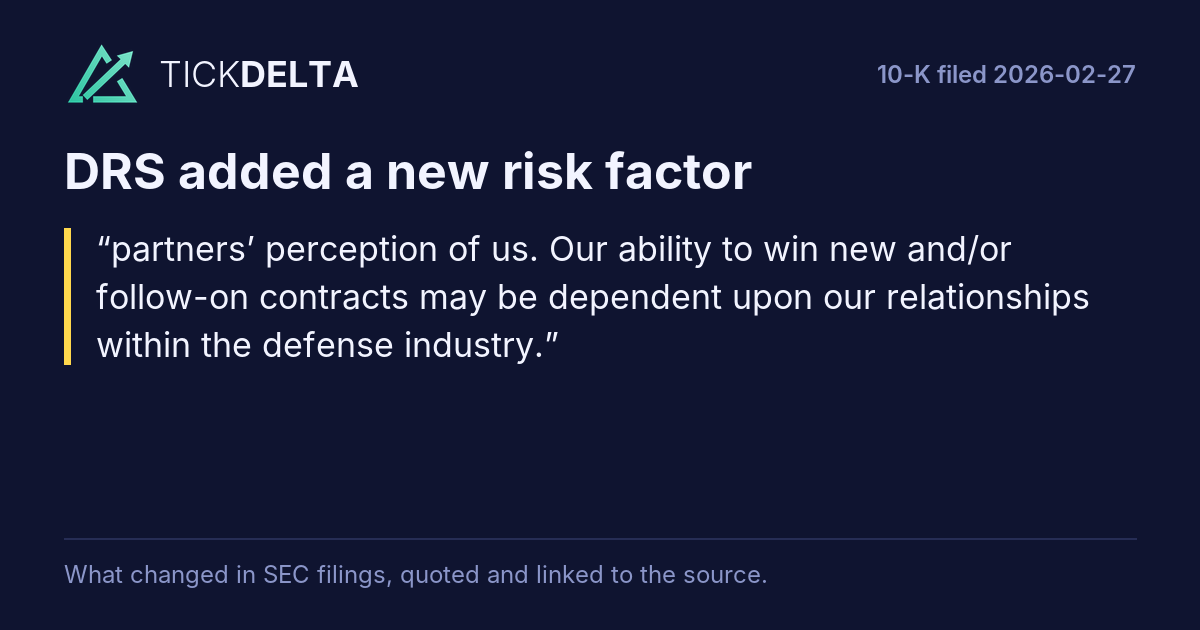
partners’ perception of us. Our ability to win new and/or follow-on contracts may be dependent upon our relationships within the defense industry.
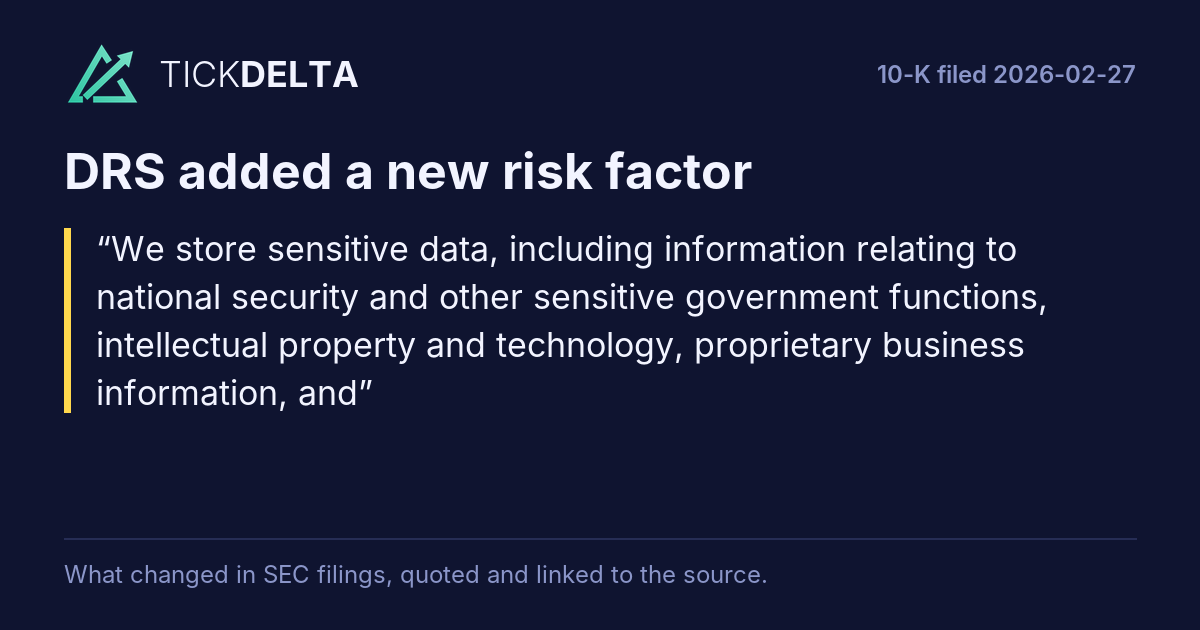
We store sensitive data, including information relating to national security and other sensitive government functions, intellectual property and technology, proprietary business information, and
We seek to protect our competitive position by seeking patents, proprietary information and other intellectual property protections when possible and appropriate. However, we do not have the right to prohibit the U.S. government from using certain technologies developed by us or to prohibit third-party
programs, and renewable portfolio standards by utility companies. The cost of complying, or of failing to comply, with these and other climate change and emissions regulations could have an adverse impact on our business, financial condition and results of operations.
Show the other 7
These risks differ in some respects from those associated with our U.S. business and our exposure to such risks may increase if our international business continues to grow.
international expansion, or our investments in these regions do not yield expected returns, our business, financial condition, and operating results may be adversely affected.
Separately, the Executive Order issued on January 7, 2026, relating to executive salaries and incentive compensation metrics applicable for defense contractors could adversely impact our ability to attract or retain executive officers.
Risks Relating to Our Ownership and Status under the Amended and Restated Proxy Agreement
restated proxy agreement with the DoW. Among other things, the amended and restated proxy agreement:
Under our existing AOP services agreements, we continue to provide Leonardo S.p.A. and its affiliates with services in support of its U.S. operations (aside from us), including services related to tax,
There can be no assurance that we will continue to pay or increase our dividend or to repurchase shares of our common stock. Additionally, there can be no assurance that we will not accelerate our dividend or repurchases of our common stock.
Paragraphs in the 10-Q filed Oct 29, 2026 that were not in the one before
New in the latest 10-Q
13 paragraphs in the 10-Q filed Oct 29, 2026 with nothing like them in the 10-Q filed Jul 30, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.
Financial statements and notes
Adjustments to reconcile net earnings to net cash provided by (used in) operating activities:
Read in the 10-Q
disclosures accordingly to reflect the impact of negotiations, settlements, rulings, advice of legal counsel, and updated information. Significant judgment is required to determine both the probability and the estimated amount of any potential losses.
Read in the 10-Q
Russia’s ongoing war in Ukraine continues to affect European security and defense priorities. In the Middle East, the conflict involving Iran, the U.S. and Israel, continuing hostilities involving regional armed groups, and the risk of renewed or broader escalation remain sources of significant uncertainty. Threats to maritime security in the Persian Gulf, including the Strait of Hormuz, and other regional waterways can disrupt commercial shipping, energy supplies and global trade. In the Indo-Pacific, tensions involving China and Taiwan and competing territorial claims in the South China Sea continue to underscore the importance of regional deterrence and maritime security. These conflicts and tensions, together with other regional instability, present evolving security requirements for the U.S. and its allies.
Read in the 10-Q
We believe these conditions continue to underscore the need for strong deterrence, resilient defense industrial capacity and advanced capabilities, including integrated air and missile defense, C-UAS, intelligence, surveillance and reconnaissance, EW, cyber resilience, secure communications and naval capabilities. These priorities may create additional demand for our products and services; however, the timing and extent of any resulting orders depend on customer procurement decisions, appropriations, program priorities and applicable regulatory approvals.
Read in the 10-Q
At the same time, these conditions may increase operational and financial risks, including supply-chain and transportation disruptions, higher energy and material costs, cybersecurity threats, and changes in sanctions, export controls or other regulatory requirements. The duration, scope and ultimate effects of these developments remain uncertain. We continue to evaluate the opportunities and risks associated with the global security environment and their potential effects on our business.
Read in the 10-Q
Show the other 8
For FY2027, which began on October 1, 2026, the President’s budget request released in April 2026 proposed approximately $1.15 trillion in discretionary funding for the national defense function and an additional $350 billion in mandatory funding through reconciliation, for approximately $1.5 trillion in proposed total national defense resources. Full-year FY2027 defense appropriations, the FY2027 NDAA and the proposed additional reconciliation funding has not been enacted to date. The proposed increases remain subject to congressional approval and do not represent enacted funding or committed orders for our products and services.
Read in the 10-Q
The Continuing Appropriations and Extensions Act, 2027, signed on September 2, 2026, provides temporary funding for federal agencies, including the DoW, through December 11, 2026, unless superseded by applicable appropriations legislation. Funding under the Continuing Appropriations and Extensions Act, 2027, generally continues at FY2026 rates, subject to statutory exceptions, and restrictions on new program starts, increased production rates and certain multi-year procurements may affect the timing of customer awards and program execution. The timing, amount and composition of final FY2027 funding remains uncertain. Additional continuing resolutions or a lapse in appropriations could delay awards or funding actions and affect the timing of our revenues and cash flows. We continue to monitor these developments and their potential effects on our business.
Read in the 10-Q
schedules for government testing or deploy our staff to customer locations or facilities as a result of such disruptions.
Read in the 10-Q
Other information
(1) Each trading arrangement listed is a “Rule 10b5-1 Trading Arrangement” and is intended to satisfy the affirmative defense of Rule 10b5-1(c), as amended.
Read in the 10-Q
(2) Transactions under each Rule 10b5-1 Plan commence no earlier than 90 days after adoption, or such later date as required by Rule 10b5-1.
Read in the 10-Q
(3) Each Rule 10b5-1 Plan may expire on such earlier date as all transactions are completed.
Read in the 10-Q
(4) Each Rule 10b5-1 Plan provides for shares to be sold on multiple predetermined dates.
Read in the 10-Q
(5) The actual number of shares under each Rule 10b5-1 Plan may be different than the aggregate number of shares listed based on tax withholdings and performance and vesting conditions of performance-based stock units and restricted stock units (as applicable).
Read in the 10-Q
The 10-Q's risk factors against the 10-K
Item 1A of the 10-Q filed Oct 29, 2026 against Item 1A of the 10-K filed Feb 27, 2026.
A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed.
Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed,
Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal
(cut words struck through, new words highlighted).
Text on the page, not a score; each links to the filing at sec.gov.
What the 10-Q itself says about its risk factors:As of the date of this Quarterly Report, there have been no material changes to the risk factors discussed under “Risk Factors” in Part I, Item 1A of our Annual Report on Form 10-K for the year ended December 31, 2025.
Read in the 10-Q
1 paragraph in the 10-Q's Item 1A, and none of them adds, rewords or quietly edits a paragraph of the 10-K's.
Phrases used for the first time
Two-word phrases in Risk Factors of the 10-K filed Feb 27, 2026 that are in none of the 1 earlier 10-Ks stored, back to Mar 3, 2025
Where each one is used
- restated proxy: •We operate under an amended and restated proxy agreement with the DoW that regulates significant areas of our governance. If we fail to comply with the amended and restated proxy agreement our classified U.S. government contracts could be terminated, which could have a material adverse impact on our business,...
- government shutdowns: •We depend on U.S. defense spending for the vast majority of our revenues. Disruptions, including from government shutdowns, or deteriorations in our relationships with the relevant agencies of the U.S.
- third amended: opportunities that could be advantageous to Leonardo S.p.A., and they may pursue acquisition opportunities that may be complementary to our business. As a result, those acquisition opportunities may not be available to us. Under the terms of our third amended and restated certificate of incorporation, neither...
- dow’s national: •We are subject to the U.S. government’s requirements, including the DoW’s National Industrial Security Program Operating Manual, for our facility security clearances, which are prerequisites to our ability to perform on classified contracts for the U.S. government.
- dow budget: The availability of U.S. government funding for significant programs in which we participate may be impacted by a number of factors beyond our control including full or partial government shutdowns, the overall federal budget, changes in spending priorities and defense spending levels, sequestration, the...
- dow regarding: unclassified information under its jurisdiction if it considers it necessary to protect national security. Failure to maintain an agreement with the DoW regarding the appropriate FOCI mitigation arrangement could result in invalidation or termination of our facility security clearances, which in turn would mean...
- discount rate: We have unfunded obligations under our pension, postretirement and supplemental retirement plans, see Note 13: Pension and Other Postretirement Benefits to the Consolidated Financial Statements. The process of determining the funded status of these plans and our pension plan expense or income involves judgment,...
- restated cooperation: On November 28, 2022, the Company entered into the Registration Rights Agreement and on June 18, 2025, the Amended and Restated Cooperation Agreement with Leonardo S.p.A and US Holding, which are both subject to the amended and restated proxy agreement. The Registration Rights Agreement, among other things,...
Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.
What was taken out
14 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.
Sources
Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.
Also
10-K change: what was reworded or cut, section by section.
Work with it
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/DRS/export.csv") into a cell.