Eagle Materials Inc EXP
New risk paragraphs, branching off last year
Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed May 20, 2025. A box jumps to the paragraph as filed, below.
Paragraphs with nothing like them in last year's 10-K
2 paragraphs in Risk Factors of the 10-K filed May 19, 2026 with nothing like them in the 10-K filed May 20, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.
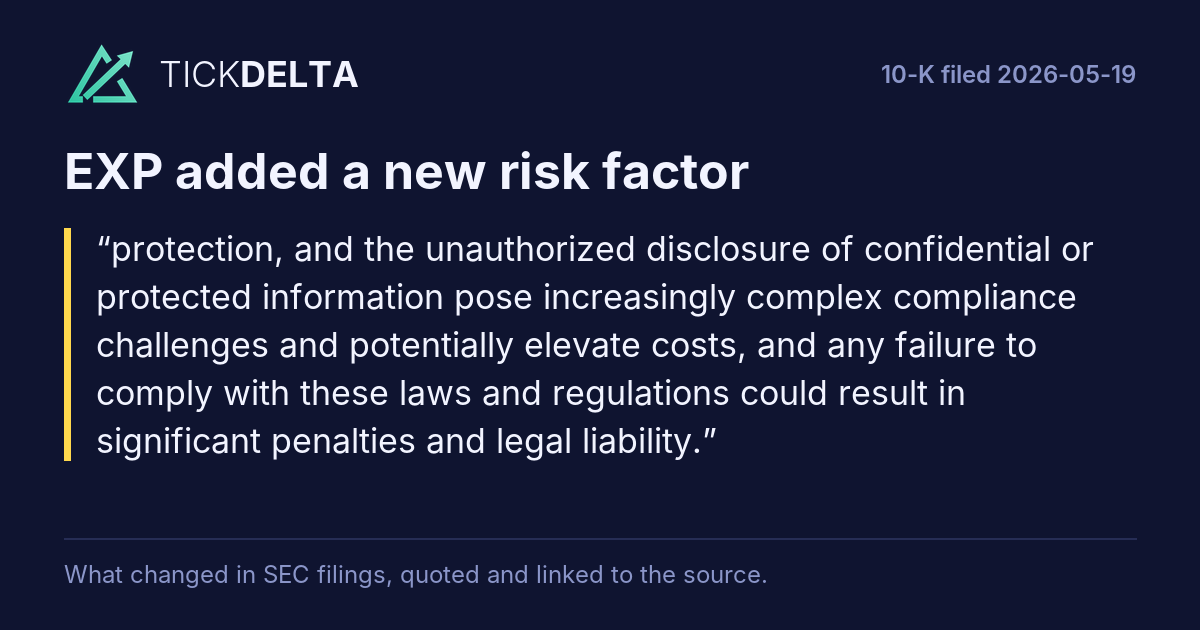
protection, and the unauthorized disclosure of confidential or protected information pose increasingly complex compliance challenges and potentially elevate costs, and any failure to comply with these laws and regulations could result in significant penalties and legal liability.
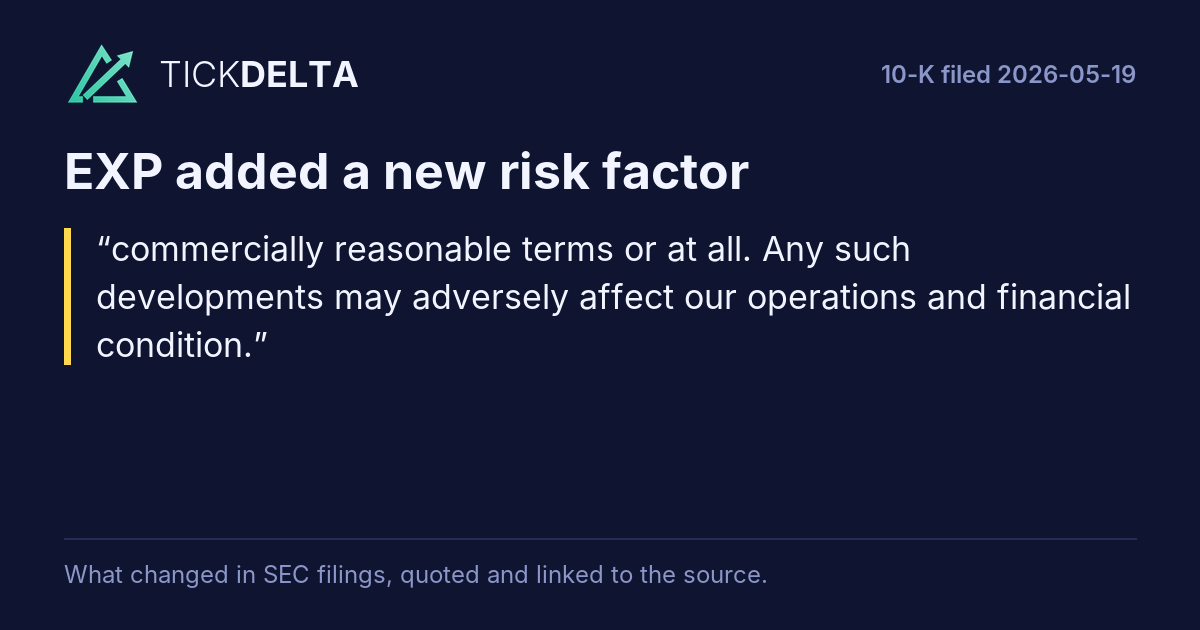
commercially reasonable terms or at all. Any such developments may adversely affect our operations and financial condition.
Paragraphs in the 10-Q filed Nov 4, 2026 that were not in the one before
New in the latest 10-Q
8 paragraphs in the 10-Q filed Nov 4, 2026 with nothing like them in the 10-Q filed Jul 29, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.
Financial statements and notes
Vesting Stock Compensation Expense — 5,468 — — 5,468 Shares Redeemed to Settle Employee Taxes — (5,947) 5,914 — (33) Purchase and Retirement of Common Stock (4) — (89,971) — (89,975) Dividends to Stockholders — — (8,079) — (8,079) Unfunded Pension Liability, net of tax — — — 41 41 Balance at September 30, 2025 $ 322 $ — $ 1,539,779 $ (3,043) $ 1,537,058 Common Capital in Retained Accumulated Total
Read in the 10-Q
Statements. The new standard is effective for fiscal years beginning after December 15, 2026, and is to be applied prospectively. Early adoption is permitted. The Company is currently evaluating the impact of adopting this guidance on its Consolidated Financial Statements.
Read in the 10-Q
(I) COMPUTATION OF EARNINGS PER SHARE The calculation of basic and diluted common shares outstanding is shown in the table below. For the Three Months Ended For the Six Months Ended
Read in the 10-Q
Stock Outstanding Effect of Dilutive Shares: Assumed Exercise of Outstanding 166,182 175,755 167,851 177,256
Read in the 10-Q
(N) INTEREST EXPENSE The following components are included in Interest Expense, net. For the Three Months Ended For the Six Months Ended
Read in the 10-Q
Show the other 3
Our business continued to perform well during our fiscal 2027 second quarter despite a challenging operating environment characterized by elevated diesel fuel prices and higher interest rates, driven by ongoing macroeconomic and geopolitical uncertainty. Against this backdrop, we generated record Revenue of $652.7 million, Net Earnings of $111.5 million, and Diluted Earnings per share of $3.63. Year-over-year sales volume increased in our Heavy Materials Sector, with the exception of Aggregates, and also increased in our Light Materials Sector.
Read in the 10-Q
(2) Excluding the cost of freight from our plants to our distribution terminals.
Read in the 10-Q
Item 6
(principal executive officer) November 4, 2026 /s/ D. CRAIG KESLER D. Craig Kesler
Read in the 10-Q
The 10-Q's risk factors against the 10-K
Item 1A of the 10-Q filed Nov 4, 2026 against Item 1A of the 10-K filed May 19, 2026.
A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed.
Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed,
Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal
(cut words struck through, new words highlighted).
Text on the page, not a score; each links to the filing at sec.gov.
What the 10-Q itself says about its risk factors:There have been no material changes to the risk factors as disclosed in Part 1. Item 1A. Risk Factors in our Form 10-K for the fiscal year ended March 31, 2026, filed with the Securities and Exchange Commission on May 19, 2026.
Read in the 10-Q
1 paragraph in the 10-Q's Item 1A, and none of them adds, rewords or quietly edits a paragraph of the 10-K's.
Phrases used for the first time
Two-word phrases in Risk Factors of the 10-K filed May 19, 2026 that are in none of the 1 earlier 10-Ks stored, back to May 20, 2025
Where each one is used
- good neighbor: Our operations are subject to certain federal environmental regulations, including those discussed above in “Environmental Matters” in the Cement and Gypsum Wallboard sections. These regulations include the CISWI Rule which applies to one of our facilities' kilns; certain permitting and control requirements for...
- neighbor plan: Our operations are subject to certain federal environmental regulations, including those discussed above in “Environmental Matters” in the Cement and Gypsum Wallboard sections. These regulations include the CISWI Rule which applies to one of our facilities' kilns; certain permitting and control requirements for...
Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.
What was taken out
7 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.
Sources
Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.
Also
10-K change: what was reworded or cut, section by section.
Work with it
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/EXP/export.csv") into a cell.