Screener / SEC EDGAR /CIK 0001023313 /10-K filed Mar 13, 2026, compared with Mar 7, 2025 /Numbers from the XBRL of the 10-Ks
Nasdaq Industrials · Professional Services

Forrester Research, Inc. FORR

Compare with peers Embed
New in the 10-K 1 paragraphs with nothing like them in the 10-K filed Mar 7, 2025 New in the 10-Q 0 paragraphs not in the 10-Q filed Aug 6, 2026 10-Q against the 10-K 1 risk factor paragraphs and sentences added or reworded

New risk paragraphs, branching off last year

Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Mar 7, 2025. A box jumps to the paragraph as filed, below.

1 new

Paragraphs with nothing like them in last year's 10-K

Quoted exactly

1 paragraph in Risk Factors of the 10-K filed Mar 13, 2026 with nothing like it in the 10-K filed Mar 7, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.

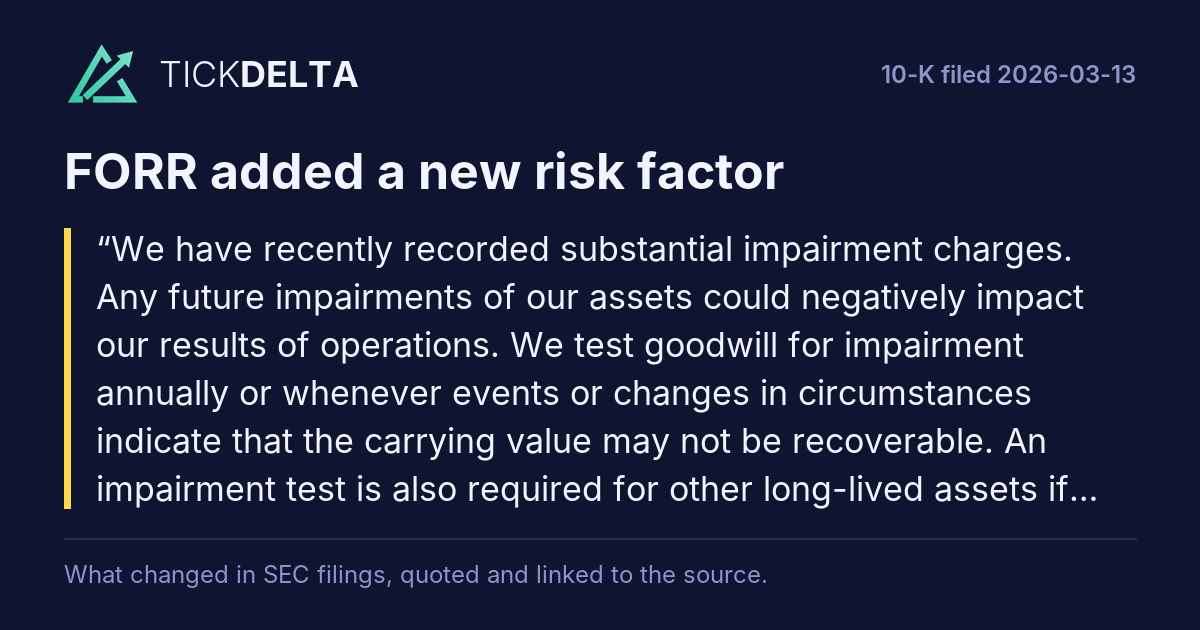
We have recently recorded substantial impairment charges. Any future impairments of our assets could negatively impact our results of operations. We test goodwill for impairment annually or whenever events or changes in circumstances indicate that the carrying value may not be recoverable. An impairment test is also required for other long-lived assets if events or changes in circumstances indicate that the carrying value may not be recoverable. Examples of events or changes in circumstances indicating that the carrying value of such long-lived assets may not be recoverable could be a significant decline in our stock price for a sustained period; significant negative industry or economic trends; our overall financial performance, such as negative or declining cash flows or a decline in actual or planned revenue or earnings compared with actual and projected results of relevant prior periods; other relevant entity-specific events including changes in management, key personnel, strategy, or customers; and other events affecting our reporting units. During the three months ended March 31, 2025, we recorded an impairment of goodwill in the amount of $83.9 million related to our Research reporting unit as a result of a triggering event arising from a sustained decline in our share price and our overall market capitalization from mid-February 2025 through March 31, 2025, along with other qualitative considerations, including the continued impact from the conditions in the macroeconomic environment, uncertainty created by changes in the United States’ trade policies, and the larger than expected decline in contract bookings during the first quarter of 2025. We performed our annual impairment test as of November 30, 2025 utilizing a quantitative assessment to determine if the fair values of each of our reporting units was less than their respective carrying values. We determined goodwill was impaired for our Research reporting unit and recorded an additional goodwill impairment charge of $26.8 million during the three months ended December 31, 2025. Any future impairment of goodwill or other long-lived assets could have a negative impact on our profitability and financial results.

Read in the 10-K

Paragraphs in the 10-Q filed Nov 6, 2026 that were not in the one before

New in the latest 10-Q

0 paragraphs in the 10-Q filed Nov 6, 2026 with nothing like them in the 10-Q filed Aug 6, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.

Nothing in the latest 10-Q is new compared with the one before it.

The 10-Q's risk factors against the 10-K

Item 1A of the 10-Q filed Nov 6, 2026 against Item 1A of the 10-K filed Mar 13, 2026. A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed. Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed, Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal (cut words struck through, new words highlighted). Text on the page, not a score; each links to the filing at sec.gov.

Added10-Q Nov 6, 2026 vs 10-K Mar 13, 2026
In addition to the other information set forth in this Form 10-Q, you should carefully consider the factors discussed in Part I, “Item 1A: Risk Factors” in our Annual Report on Form 10-K for the year ended December 31, 2025, which could materially affect our business, financial condition or future results. The risk factors described in our Annual Report on Form 10-K remain applicable to our business. The risks described in our Annual Report on Form 10-K are not the only risks that we face. Additional risks and uncertainties not currently known to us or that we currently deem to be immaterial also may materially adversely affect our business, financial condition and/or operating results.

Read it in the 10-Q at sec.gov

Phrases used for the first time

Two-word phrases in Risk Factors of the 10-K filed Mar 13, 2026 that are in none of the 1 earlier 10-Ks stored, back to Mar 7, 2025

carrying value ×3long-lived assets ×3circumstances indicate ×2impairment test ×2reporting units ×2three months ×2months ended ×2research reporting ×2reporting unit ×2
Where each one is used
  • carrying value: We have recently recorded substantial impairment charges. Any future impairments of our assets could negatively impact our results of operations. We test goodwill for impairment annually or whenever events or changes in circumstances indicate that the carrying value may not be recoverable. An impairment test is...
  • long-lived assets: We have recently recorded substantial impairment charges. Any future impairments of our assets could negatively impact our results of operations. We test goodwill for impairment annually or whenever events or changes in circumstances indicate that the carrying value may not be recoverable. An impairment test is...
  • circumstances indicate: We have recently recorded substantial impairment charges. Any future impairments of our assets could negatively impact our results of operations. We test goodwill for impairment annually or whenever events or changes in circumstances indicate that the carrying value may not be recoverable. An impairment test is...
  • impairment test: We have recently recorded substantial impairment charges. Any future impairments of our assets could negatively impact our results of operations. We test goodwill for impairment annually or whenever events or changes in circumstances indicate that the carrying value may not be recoverable. An impairment test is...
  • reporting units: We have recently recorded substantial impairment charges. Any future impairments of our assets could negatively impact our results of operations. We test goodwill for impairment annually or whenever events or changes in circumstances indicate that the carrying value may not be recoverable. An impairment test is...
  • three months: We have recently recorded substantial impairment charges. Any future impairments of our assets could negatively impact our results of operations. We test goodwill for impairment annually or whenever events or changes in circumstances indicate that the carrying value may not be recoverable. An impairment test is...
  • months ended: We have recently recorded substantial impairment charges. Any future impairments of our assets could negatively impact our results of operations. We test goodwill for impairment annually or whenever events or changes in circumstances indicate that the carrying value may not be recoverable. An impairment test is...
  • research reporting: We have recently recorded substantial impairment charges. Any future impairments of our assets could negatively impact our results of operations. We test goodwill for impairment annually or whenever events or changes in circumstances indicate that the carrying value may not be recoverable. An impairment test is...

The 10-K at sec.gov

Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.

Sources

Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.

Also

10-K change: what was reworded or cut, section by section.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/FORR/export.csv") into a cell.

Next:10-K change
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.