Form 10-K for the Fiscal Year Ended December 31, 2024
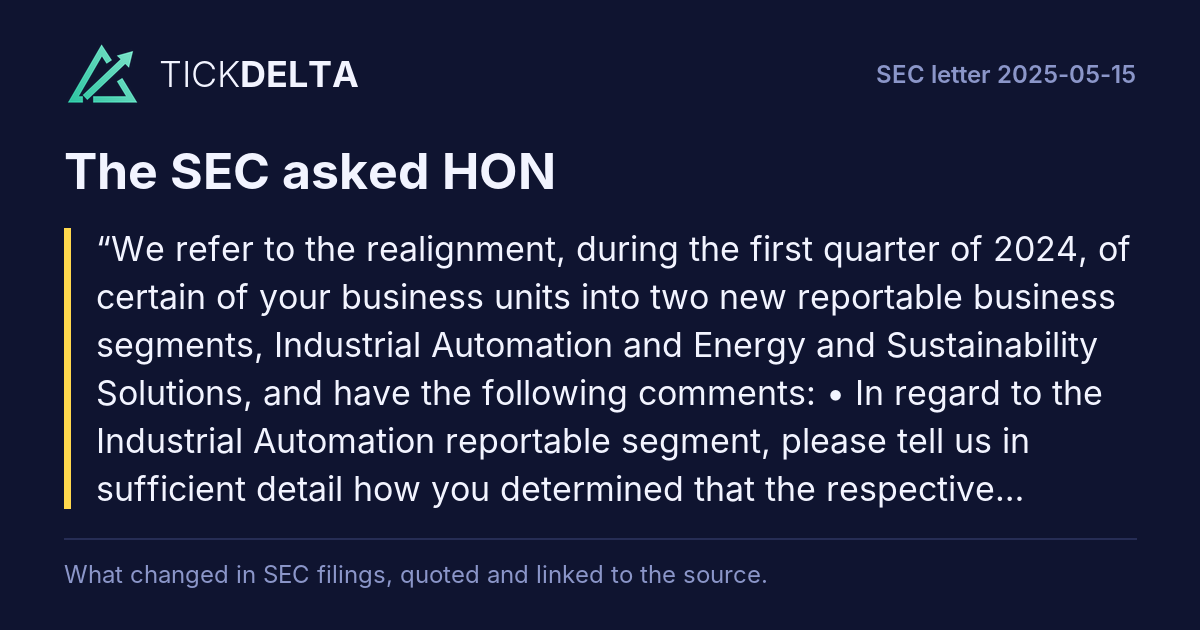
We refer to the realignment, during the first quarter of 2024, of certain of your business units into two new reportable business segments, Industrial Automation and Energy and Sustainability Solutions, and have the following comments: • In regard to the Industrial Automation reportable segment, please tell us in sufficient detail how you determined that the respective operating segments met the aggregation criteriaRest of the question
upon the addition of the Process Solutions business unit. Refer to ASC 280-10-50-11. • Please tell us whether the change in reportable segments impacted your existing reporting units prior to the realignment. If so, please tell us whether you performed an interim goodwill impairment test related to the existing reporting units before the change. Refer to ASC 350-20-35-3C(f) and ASC 350-20-35-45. In closing, we remind you that the company and its management are responsible for the accuracy and adequacy of their disclosures, notwithstanding any review, comments, action or absence of action by the staff.
The Company identifies operating segments in accordance with ASC 280-10-50-1. In October 2023, Honeywell announced plans to realign our business portfolio to three compelling megatrends. As part of this realignment, effective January 2024, the Company changed its organization structure, combining the Process Solutions business unit with the former Safety and Product Solutions business units to form our Industrial Automation segment.
On January 1, 2024, the Company appointed a President and Chief Executive Officer (CEO) of Industrial Automation, reporting directly to the chief operatingRead in the reply ↗Rest of the answer
decision maker (CODM). In the first quarter of 2024, the information regularly reviewed by the CODM changed to include the operating results and budget of the Industrial Automation segment and this information is used by the CODM to assess its performance and allocate resources. The compensation structure for the President and CEO of Industrial Automation is partially based on the performance of the Industrial Automation business.
Based on these considerations, the Company identified Industrial Automation as an operating segment and reports information on that operating segment under ASC 280-10-50-10. The Company does not maintain operating segments below Industrial Automation to aggregate. Since it combined the Process Solutions business unit and former Safety and Products Solutions business units collectively together as one new operating segment under ASC 280-10-50-1, the Company was not required to and has not applied the separate aggregation criteria outlined in ASC 280-10-50-11 to the Industrial Automation segment because it was determined to be one operating segment.
Honeywell's realignment during the first quarter of 2024 did not impact the Company's reporting units. The reporting unit composition is unchanged before and after the reorganization. As a result of the realignment, the Process Solutions reporting unit moved to the Industrial Automation segment with no changes in the composition or carrying amount of its net assets. In addition, there were no events or changes in circumstances identified that would more likely than not reduce the fair value of an existing reporting unit below its carrying amount as a result of this move. Therefore, the Company was not required to perform an interim goodwill impairment test.
First report after the company's reply of 2025-06-09: 10-Q filed 2025-07-24 ↗, against the 10-Q filed 2025-04-29 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: request for more time, 2025-05-21, closing letter, 2025-07-10