Screener / SEC EDGAR /CIK 0001955520 /Numbers from the XBRL of the 10-Ks
NYSE Materials · Aggregates

Knife River Corp KNF

Compare with peers Embed
SEC comment letters, last 20 years

2 reviews of KNF's filings by SEC staff

UPLOAD and CORRESP
Reviews 2 latest letter May 8, 2025
Questions asked 29 each answered in the company's own letter
No closing letter 1 reviews without a letter saying the staff completed it

When the SEC's staff reviews a filing, it writes to the company with numbered questions, and the company answers each one in a letter. SEC publishes the exchange once the review is over, at least 20 business days later. A question is not an accusation; most reviews end with the company adding detail to its next filing.

How the reviews went

Every review on EDGAR, from the first staff letter to the letter that closes it

  1. 1. Staff letters 6 UPLOAD
  2. 2. Questions in them 29 numbered comments
  3. 3. Company replies 6 CORRESP
  4. 4. Reviews closed 1 of 2 closing letter

Half the closed reviews took 19 days or less from the first letter to the closing letter.

Form 10-K for the fiscal year ended December 31, 2024

2025-05-08 to 2025-05-27 · 2 questions · 1 letter from the SEC, 1 from the company
Review closed 2025-05-27
RevenueSegmentsIncome taxes
Notes to Financial Statements · Note 15 - Business Segment Data, page 99
SEC asked (1)
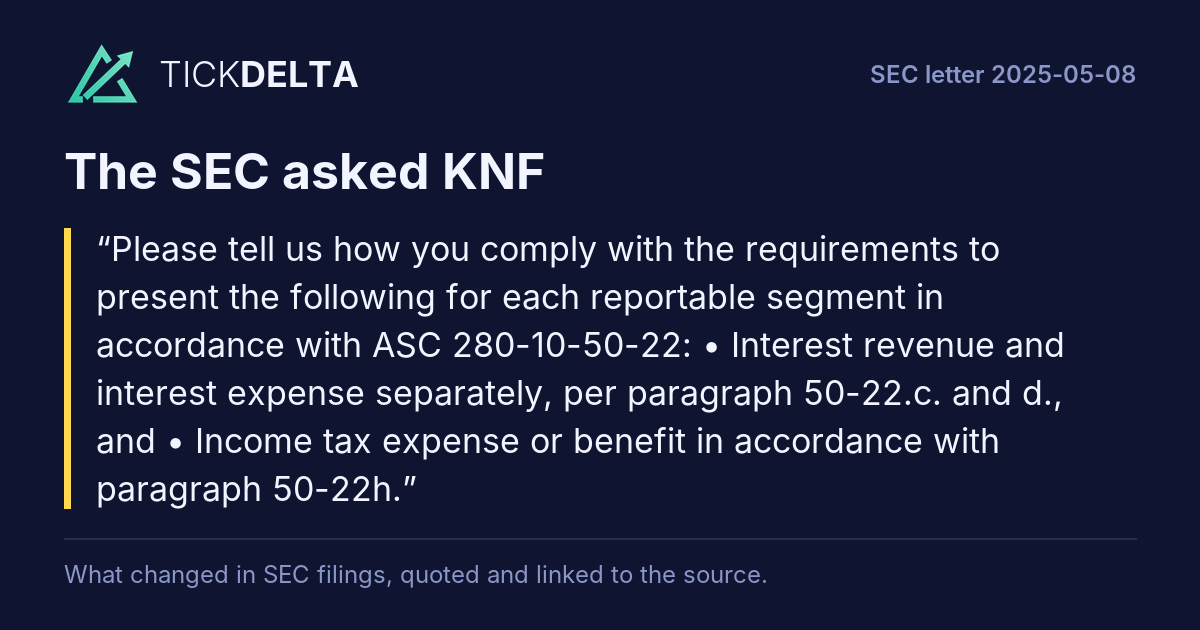
Please tell us how you comply with the requirements to present the following for each reportable segment in accordance with ASC 280-10-50-22: • Interest revenue and interest expense separately, per paragraph 50-22.c. and d., and • Income tax expense or benefit in accordance with paragraph 50-22h.
KNF answered
We acknowledge the Staff’s comment and respectfully advise the Staff that in accordance with ASC 280-10-50-22, a public entity shall disclose the amounts noted in 50-22c. and d. if the specified amounts are included in the measure of segment profit or loss reviewed by the chief operating decision maker or are otherwise regularly provided to the chief operating decision maker, even if not included in that measure of segment profit or loss.
Rest of the answer

The measure of segment profit or loss reviewed by our chief operating decision maker is earnings before interest, taxes, depreciation, depletion and amortization, which does not include the effects of interest revenue, interest expense or income tax expense or benefit. Further, our chief operating decision maker is not provided financial information for our segments that includes interest revenue, interest expense or income tax expense or benefit.

Based on the above discussion, the Company believes that its current presentation is acceptable under ASC 280-10-50-22.

Read in the reply
In its next report

First report after the company's reply of May 14, 2025: 10-Q filed Aug 5, 2025 ↗, against the 10-Q filed May 6, 2025 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Notes to Financial Statements · Note 15 - Business Segment Data, page 99
SEC asked (2)
Please tell us why segment revenues disclosed on page 100 do not reconcile with the corresponding segment revenues disclosed on pages 46-51 for all periods presented. For example, $493,066 of revenue from external customers for Pacific in 2024 corresponds with $493.1 on page 46 but the revenue amounts for Northwest, Mountain, Central, and Energy Services segments do not reconcile.
Rest of the question

We remind you that the company and its management are responsible for the accuracy and adequacy of their disclosures, notwithstanding any review, comments, action or absence of action by the staff.

KNF answered
We acknowledge the Staff’s comment and respectfully advise the Staff that the difference noted between the segment revenues on page 100 and those disclosed on pages 46-51 are related to intersegment revenues for sales between segments. The intersegment sales amounts included in the Business Segment Data footnote disclosure in the notes to the financial statements includes both intersegment revenues and intra segment revenues (sales between companies within the segment), whereas the internal sales disclosed in the Management’s Discussion and Analysis of Financial Condition and Results of
Rest of the answer

Operations only includes the sales between companies within the segment.

The following reconciles the amounts reported in the Management’s Discussion and Analysis of Financial Condition and Results of Operations to the Business Segment Data footnote disclosure in the notes to the financial statements for 2024.

Pacific

Northwest

Mountain

Central

Energy Services

(In millions)

Aggregates $ 112.3 $ 184.8 $ 101.8 $ 157.2 $ —

Ready-mix concrete 145.8 167.8 117.1 224.8 —

Asphalt 30.7 104.6 120.9 185.3 —

Liquid Asphalt

— — — — 238.9

Other 149.3 18.1 — 31.7 50.6

Contracting Services 141.9 324.8 459.0 432.5 —

Internal Sales1

(86.9) (107.7) (135.7) (213.4) (13.8)

Total

493.1 692.4 663.1 818.1 275.7

Intersegment revenues1

— (2.5) (0.2) (0.2) (41.0)

Revenues from external customers $ 493.1 $ 689.9 $ 662.9 $ 817.9 $ 234.7

1.The total of internal sales and intersegment revenues ties to the amount disclosed in the Business Segment Data disclosure for intersegment revenues in the filed Form 10-K for the year ended December 31, 2024.

In future filings, we will revise our disclosures in the Business Segment Data footnote disclosure in the notes to the financial statements to present total segment revenue net of sales between companies within the segment and also remove the sales between companies within the segment from the intersegment revenue line. The total segment revenues will then reconcile to the revenues disclosed in the Management’s Discussion and Analysis of Financial Condition and Results of Operations and only intersegment sales will be included in intersegment revenues line in the Business Segment Data footnote disclosure in the notes to the financial statements. See the following for the 2024 Business Segment Data footnote revised for these changes.

For the year ended December 31, 2024 Pacific Northwest Mountain Central Energy Services Total

(In thousands)

Revenues from external customers $ 493,066 $ 689,893 $ 662,892 $ 817,872 $ 234,652 $ 2,898,375

Intersegment revenues 47 2,542 173 194 41,040 43,996

Total segment revenue 493,113 692,435 663,065 818,066 275,692 2,942,371

Other revenues

1,149

Less: Elimination of intersegment revenue 44,515

Total consolidated revenue $ 2,899,005

* * * * *

In connection with our response to the Staff’s comments, we acknowledge that the Company and its management are responsible for the accuracy and adequacy of its disclosures, notwithstanding any review, comments action or absence of action by the Staff.

Read in the reply
In its next report

First report after the company's reply of May 14, 2025: 10-Q filed Aug 5, 2025 ↗, against the 10-Q filed May 6, 2025 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Also in this review: closing letter, 2025-05-27
Form 10-12B

2023-01-13 to 2023-05-08 · 27 questions · 5 letters from the SEC, 5 from the company
No closing letter
RevenueSegmentsNon-GAAP measuresReserves and insuranceLiquidity and cashResults discussion (MD&A)DebtRisk factorsIncome taxesLeasesGoodwill and impairmentCritical estimatesLegal and contingenciesDerivatives and hedgingInventory
SEC letter of Jan 13, 2023 ↗ no reply letter on EDGAR
Summary Historical Consolidated Financial Data · Consolidated Balance Sheet, page 18
SEC asked (1)
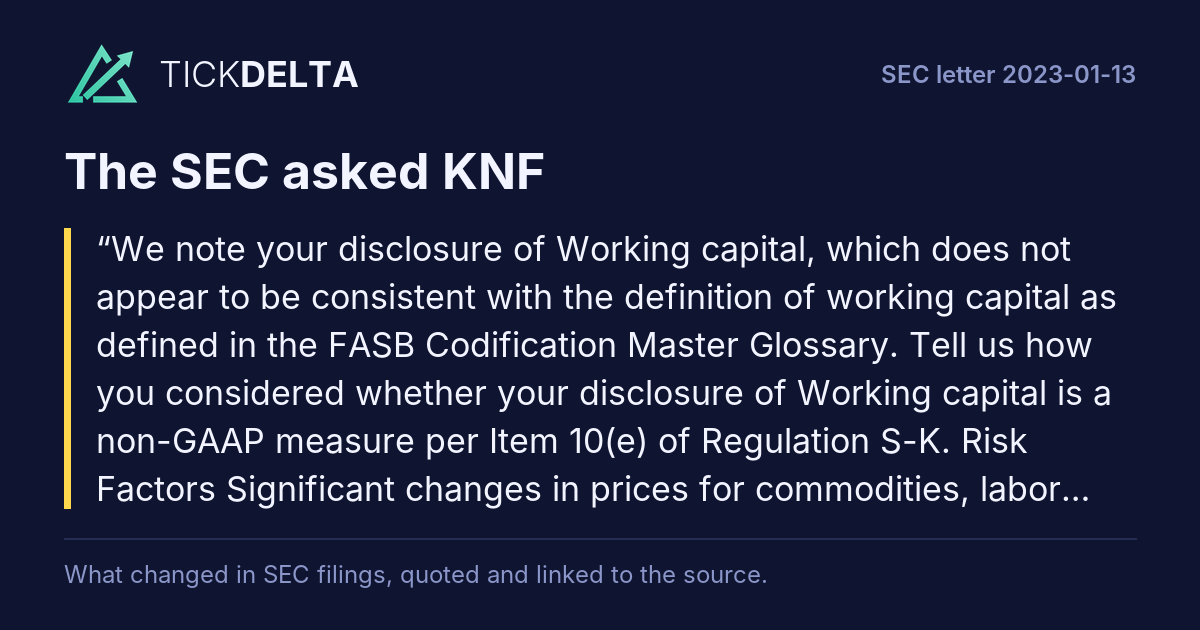
We note your disclosure of Working capital, which does not appear to be consistent with the definition of working capital as defined in the FASB Codification Master Glossary. Tell us how you considered whether your disclosure of Working capital is a non-GAAP measure per Item 10(e) of Regulation S-K.
Rest of the question

Risk Factors Significant changes in prices for commodities, labor, or other production and delivery inputs could negatively affect ..., page 19

KNF answered

No reply letter found.

Summary Historical Consolidated Financial Data · Consolidated Balance Sheet, page 18
SEC asked (2)
We note your risk factor indicating that inflationary pressures could affect your prices and supply and demand for your products and services, etc. We further note disclosure on page 73 regarding the inflationary impact on your margins. Please update this risk factor if recent inflationary pressures have materially impacted your operations.
Rest of the question

In this regard, identify the types of inflationary pressures you are facing and how your business has been affected. As part of your disclosure, identify actions planned or taken, if any, to mitigate inflationary pressures.

KNF answered

No reply letter found.

The Separation and Distribution, page 40
SEC asked (3)
Please revise to disclose whether the MDU Resources board of directors considered alternatives to the spin-off transaction, or a spin-off of Knife River and MDU's Construction Services business as a combined entity, and, if so, why those alternatives were not pursued.
KNF answered

No reply letter found.

Selected Historical Consolidated Financial Data · Non-GAAP Financial Measures, page 49
SEC asked (4)
We note your presentation of EBITDA and your statement that it is “calculated by adding back interest expense and depreciation, depletion and amortization expense to income (loss) before income taxes.” However, net income as presented in the statement of operations is the GAAP measure intended by the term "earnings" in the calculation of EBITDA in Exchange Act Release No. 47226.
Rest of the question

Refer to Item 10(e)(i)(B) of Regulation S- K and Questions 103.01 and 103.02 of the Compliance and Disclosure Interpretations for Non-GAAP Financial Measures, and revise your disclosure accordingly. This comment applies to the qualitative and quantitative reconciliation disclosures on page 87 as well.

KNF answered

No reply letter found.

Selected Historical Consolidated Financial Data · Non-GAAP Financial Measures, page 49
SEC asked (5)
We note the disclosure of EBITDA margin in other sections of your submission. Please expand your disclosures here to identify EBITDA Margin as a Non-GAAP measure and provide the disclosures required by Item 10(e) of Regulation S-K and Regulation G. Business
KNF answered

No reply letter found.

Business Segments, page 56
SEC asked (6)
We note your reference under this heading and elsewhere in the submission to “net revenue.” Please clarify what is meant by referring to revenue on a net basis, which is not consistent with the presentation of revenue on the consolidated statements of income. Aggregate sites and reserves, page 68
KNF answered

No reply letter found.

Business Segments, page 56
SEC asked (7)
We reviewed your reserve disclosure and noted the sale price for your salable products which serves as a basis for your reserve determination was not disclosed in your filing as required by the footnotes to Tables 1 and 2 of paragraph (b) of Item 1303 of Regulation S- K. Please modify your filing to include your reserve price for your properties with your reserve tables.
KNF answered

No reply letter found.

Business Segments, page 56
SEC asked (8)
Please report your mine site production and ownership/lease status by division (regional) and type (aggregate or sand and gravel) to correspond to your reserve reporting.
KNF answered

No reply letter found.

Management's Discussion and Analysis of Financial Condition and Results of Operations · Business Segment Financial and Operating Data, page 76
SEC asked (9)
Please revise the discussion and analysis of operating results where the financial statements reflect material changes from period-to-period in one or more line items, including where material changes within a line item offset one another, to describe the underlying reasons for these material changes in quantitative and qualitative terms. Refer to Item 303 of Regulation S-K.
Rest of the question

As one example, we note the decrease in gross profit experienced in the Pacific reportable segment on page 77 is attributed to higher fuel, material and production costs, partially as a result of inflationary pressures, but that these costs were somewhat offset by the higher average selling prices. As another example, the increase in net revenue in the Northwest reportable segment is attributed to higher sales volumes and higher average selling prices on products. Refer to Item 303(b)(2)(iii)) for guidance on describing the reasons for changes from period to period in revenue.

KNF answered

No reply letter found.

Critical Accounting Estimates · Goodwill, page 86
SEC asked (10)
We note your statement that “At October 31, 2021, the fair value of Knife River substantially exceeded the carrying value.” Please further revise this statement to clarify that material goodwill does not exist at reporting units that are at risk of failing step one or that no reporting units are at risk.
KNF answered

No reply letter found.

Description of Knife River Holding Company's Capital Stock · Exclusive Forum , page 113
SEC asked (11)
We note your disclosure here and on page 37 that your forum selection provision in your amended and restated certificate of incorporation will identify the state courts located within the State of Delaware (or, if no state court located within the State of Delaware has jurisdiction, the federal district court for the District of Delaware) as the exclusive forum for certain litigation, including any “derivative
Rest of the question

action.” Please disclose whether this provision applies to actions arising under the Securities Act or Exchange Act. If so, please also state that there is uncertainty as to whether a court would enforce such provision. If the provision applies to Securities Act claims, please also state that investors cannot waive compliance with the federal securities laws and the rules and regulations thereunder. In that regard, we note that Section 22 of the Securities Act creates concurrent jurisdiction for federal and state courts over all suits brought to enforce any duty or liability created by the Securities Act or the rules and regulations thereunder. If this provision does not apply to actions arising under the Securities Act or Exchange Act, please also ensure that the exclusive forum provision in the governing documents states this clearly.

KNF answered

No reply letter found.

Note 3 - Significant Accounting Policies · Revenue recognition, page F-12
SEC asked (12)
We note your statement that the “nature of the services provided generally include integrating a set of services and related construction materials into a single project to create a distinct bundle of goods and services, which is then evaluated to determine whether a separate performance obligation exists.” Please revise to disclose how you determine the transaction price for your contracts, including any methods,
Rest of the question

inputs and assumptions used, and how you allocate the transaction price, including how you estimate the stand-alone selling price. Refer to FASB ASC 606-10-50-20.

KNF answered

No reply letter found.

Note 3 - Significant Accounting Policies · Revenue recognition, page F-12
SEC asked (13)
Your disclosure indicates that you estimate the amount of revenue to be recognized on variable consideration using estimation methods that best predict the most likely amount of consideration you expect to be entitled to or expect to incur.
Rest of the question

Please revise to disclose information about the methods, inputs, and assumptions used in estimating variable consideration and in assessing whether an estimate of variable consideration is constrained. Refer to FASB ASC 606-10-50-20.

KNF answered

No reply letter found.

Property, plant and equipment, page F-14
SEC asked (14)
We note that additions to property, plant and equipment are recorded at cost and that you deplete Aggregate reserves using the units-of-production method based on recoverable aggregate reserves. Please expand your disclosures to explain how you account for your mining activities. Specifically, we note your properties are currently in various stages of exploration, development and production.
Rest of the question

The expanded disclosures should identify how you account for these activities at each stage as well as identify where these amounts are accounted for in your financial statements. For example, identify where you have expensed exploration and evaluation costs. Clarify your capitalization policy for your Aggregate reserves balance and the type(s) of reserves used as the basis for your units-ofproduction method. Describe the production costs incurred and what amounts are included in inventory or cost of revenue.

KNF answered

No reply letter found.

Note 4 - Disaggregation of Revenue, page F-16
SEC asked (15)
Please tell us your consideration of providing additional disaggregation of revenue based on the disclosures on page 65 for Contracting Services Revenue Breakdown.
KNF answered

No reply letter found.

Note 16 - Business Segment Data, page F-28
SEC asked (16)
We note you include the All Other category in the reconciliations provided on pages F-28 and F-29. Please tell us how these disclosures provided in response to FASB ASC 280-1050-30 appropriately reflect reconciliations of the total of the reportable segments to your consolidated amounts. Refer also to FASB ASC 280-10-50-15 and FASB ASC 280-1055-48 and 55-49.
KNF answered

No reply letter found.

Exhibits
SEC asked (17)
We note your disclosure that in connection with the separation and distribution, Knife River Holding Company anticipates that it will incur short-term and long-term debt. Please file a copy of these agreements as exhibits when they are available. Refer to Item 601(b) of Regulation S-K.
KNF answered

No reply letter found.

General
SEC asked (18)
We note your disclosure that no vote of MDU Resources stockholders is required in connection with the spin-off. Please provide us with a legal analysis regarding the basis for that statement.
KNF answered

No reply letter found.

General
SEC asked (19)
Please provide an analysis of whether the distribution of the Knife River Holding Co. shares to the shareholders of MDU Resources Group constitutes a sale under Section 2(a)(3) of the Securities Act. We note your disclosure that MDU Resources will retain up to 19.9 percent of the outstanding shares of Knife River Holding Company common stock following the distribution.
Rest of the question

You further discuss that MDU Resources intends to dispose of all shares of Knife River Holding Company common stock that it retains after the distribution; such dispositions may include one or more exchanges of shares of the Knife River Holding Company common stock for debt, distributions to MDU Resources stockholders, exchanges for MDU Resources shares or one or more sales of such shares for cash. As part of your response, explain whether the transactions in connection with the distribution would fundamentally alter the nature of the MDU Resources shareholders’ investment such that the shareholders are providing value for the Knife River shares, and discuss the shareholders economic and voting interests in MDU Resources prior to the transactions compared to their economic and voting interests in MDU Resources and Knife River after the transactions.

KNF answered

No reply letter found.

Notes to Consolidated Financial Statements · Note 16 - Business Segment Data, page F-28
SEC asked
We note your revisions to this footnote for the reconciliations of reportable segment revenues and assets to the consolidated totals in response to prior comment 16. However, it appears that the reconciliation of reportable segment profit or loss (i.e. Total segment EBITDA) was not similarly revised.
Rest of the question

In addition, as noted in FASB ASC 280-10-55-49, reconciliations are also required to be shown for every other significant item of information disclosed (see paragraph 280-10-50-30(d)). Please further revise your disclosures accordingly.

KNF answered
The Company respectfully directs the Staff to pages F-29 – F-31 of the Form 10, where the business segment information is presented. The additional significant items disclosed would be EBITDA, capital expenditures, and property, plant and equipment. The Company feels they adequately include the information necessary for both capital expenditures and property, plant and equipment and do not require further reconciliations within the footnote.
Rest of the answer

Further, the Company did include a reconciliation for EBITDA but it required revision and is noted below as such.

The presentation of capital expenditures can be reconciled to the statement of cash flows using the footnote that is currently included at the bottom of the table. The purpose of the footnote is to include non-cash amounts that are included in these totals but not included in the statement of cash flows. The Company has revised the footnote to include the dollar amounts in thousands instead of millions. Please see the following table that shows this reconciliation:

2022

2021

2020

Business Segment Note

Capital Expenditures

181,847

417,524

191,635

Non-Cash Adjustments from Footnote

(5,430)

(8,077)

916

Total

176,417

409,447

192,551

Statement of Cash Flows

(178,162)

(174,229)

(135,870)

Acquisitions, net of cash acquired

1,745

(235,218)

(56,681)

(176,417)

(409,447)

(192,551)

The presentation of property, plant and equipment currently ties to both the balance sheet and the Note 7 – Property, Plant and Equipment.

The Company has revised the disclosure on page F-31 of the Form 10 to include a table presenting the reconciliation of reportable segment EBITDA to consolidated income before income taxes following the example in

ASC 280-10-55-48 and 49.

Read in the reply
Notes to Unaudited Pro Forma Consolidated Financial Statements · Note 2 - Transaction Accounting Adjustments, page 58
SEC asked (1)
Please expand your disclosure to clarify the nature of the additional employee-related assets and obligations that will be given pro forma effect in adjustment C.
KNF answered
In response to the Staff’s comment, the Company respectfully advises the Staff that it has revised the disclosure in Note 2 adjustment C on page 59 of the Information Statement to provide the requested information.
Read in the reply
Notes to Unaudited Pro Forma Consolidated Financial Statements · Note 2 - Transaction Accounting Adjustments, page 58
SEC asked (2)
We note the reclassification of certain transactions historically included in related-party accounts to be given pro forma effect in adjustment D. Please tell us more about your conclusion that the 19.9% retention of Knife River Holding Company by MDU Resources is not reflective of a related-party relationship as contemplated in FASB ASC 850.
KNF answered
In response to the Staff’s comment, the Company respectfully advises the Staff that it has reviewed the definition of Related Parties in ASC 850-10-20 and determined that MDU Resources does not meet the definition to be considered a related party. The Company also reviewed the significant influence indicators in ASC 323-10-15-6 through ASC 323-10-15-8 and concluded that MDU Resources will not have significant influence over the Company at the time of the separation.
Rest of the answer

The Company revised the disclosure on page 136 to clarify that MDU Resources will not exert any control over the Company through the shares of common stock it retains. The Company has provided its detailed analysis of these sections of the codification below.

FASB Accounting Standards Codification (ASC) 850-10-20 defines related parties as:

a.

“Affiliates of the entity b.

Entities for which investments in their equity securities would be required, absent the election of the fair value option under the Fair Value Option Subsection of Section 825-10-15, to be accounted for by the equity method by the investing entity c.

Trusts for the benefit of employees, such as pension and profit-sharing trusts that are managed by or under the trusteeship of management d.

Principal owners of the entity and members of their immediate families e.

Management of the entity and members of their immediate families f.

Other parties with which the entity may deal if one party controls or can significantly influence the management or operating policies of the other to an extent that one of the transacting parties might be prevented from fully pursing its own separate interest g.

Other parties that can significantly influence the management or operating policies of the transacting parties or that have an ownership interest in one of the transacting parties and can significantly influence the other to an extent that one or more of the transaction parties might be prevented from fully pursuing its own separate interests.”

Additionally, the FASB ASC master glossary provides the following definitions for affiliates and principal owners:

“Affiliate: A party that, directly or indirectly through one or more intermediaries, controls, is controlled by, or is under common control with an entity.”

“Principal Owner: Principal owners are owners of record or known beneficial owners of more than 10 percent of the voting interest of the entity.”

As discussed below, we do not consider MDU Resources to be a related party post separation. MDU Resources expects to retain 19.9% or less of the shares of the Company of which the exact amount is undetermined at this time. Analysis of the retention of such shares, has indicated that MDU Resources would not meet the definition of a related party as it will not be considered an “Affiliate,” is expected to record its investment in the Company using the fair value method of accounting under ASC 820, does not meet the definition of a “Principal Owner” and does not have significant influence over the management or policies of the Company. The Company considered the following factors when reviewing ASC 850-10-20 and assessing whether MDU Resources is a related party:

Affiliates of the entity.

Following the completion of the separation, MDU Resources and the Company will no longer be affiliated entities. The Company will enter into a Stockholder and Registration Rights Agreement, the form of which is attached as Exhibit 4.1 to the Form 10, which is designed to ensure that MDU Resources does not have the power to direct the voting of the retained equity interest. Sections 3.01(a) and 3.01(b) of Exhibit 4.1 state that:

“From the date of this Agreement and until the date that the Parent Group ceases to own any Remaining Shares, Parent shall, and shall cause each other member of the Parent Group to (in each case, to the extent that they then own any Remaining Shares), be present, in person or by proxy, at each and every SpinCo stockholder meeting, and otherwise to cause all Remaining Shares then owned by them to be counted as present for purposes of establishing a quorum at any such meeting, and to vote or consent on any matter (including waivers of contractual or statutory rights), or cause to be voted or consented on any such matter, all such Remaining Shares in proportion to the votes cast by the other holders of

SpinCo Shares on such matter.”

“From the date of this Agreement and until the date that the Parent Group ceases to own any Remaining Shares, Parent hereby grants (emphasis added), and shall cause each other member of the Parent Group (in each case, to the extent that they own any Remaining Shares) to grant, an irrevocable proxy (emphasis added), which shall be deemed coupled with an interest sufficient in Law to support an irrevocable proxy to SpinCo (emphasis added) or its designees, to vote (emphasis added), with respect to any matter (including waivers of contractual or statutory rights), all Remaining Shares owned by them in proportion to the votes cast by the other holders of SpinCo Shares on such matter; provided that (i) such proxy shall automatically be revoked as to a particular Remaining Share upon any Transfer of such Remaining Share from a member of the Parent Group to a Person other than a member of the Parent Group and (ii) nothing in this Section 3.01(b) shall limit or prohibit any such Transfer.”

The language included in the Stockholder and Registration Rights Agreement provides that MDU Resources will vote its retained equity interest in proportion to the vote of the non-MDU Resources stockholders of the Company

(See Section 3.01(a) in Exhibit 4.1). In addition, MDU Resources will grant the Company an irrevocable proxy to vote its shares in such proportion, which will preclude MDU Resources’ ability to influence the Company (See Section 3.01(b) in Exhibit

4.1). Based on this, the Company has determined that MDU Resources will not exert any control over Knife River through the retained shares and therefore would not be considered an affiliate.

Entities for which investments in their equity securities would be required to be accounted for by the equity method by the investing entity.

See the analysis completed under the criteria of ASC 323-10-15-6 below where it has been identified that MDU Resources would not have significant influence over the Company. MDU Resources, therefore, will not be required to account for its investment in the Company under the equity method and expects to account for its investment in the Company under the fair value method of accounting under ASC 820.

Read in the reply
Note 3 - Autonomous Entity Adjustments, page 60
SEC asked (3)
Please expand your disclosures for pro forma adjustments J and K to describe any material uncertainties and assumptions associated with each autonomous entity adjustment.
KNF answered
Principal owners of the entity and members of their immediate families.

MDU Resources will not be a principal owner of the Company, nor will any immediate family members of the MDU Resources’ board of directors or management team. MDU Resources has not determined the expected ownership of the Company at this time; however, it will not retain more than 19.9% of the common stock of the Company.
Rest of the answer

Although the ownership percentage may exceed the 10% threshold identified in the FASB definition of “Principal Owner,” the Stockholder and

Registration Rights Agreement outlines the voting rights of MDU Resources’ and is clear that MDU Resources retained interest will be voted in proportion to the votes of the non-MDU Resources stockholders of the Company and MDU Resources will grant an irrevocable proxy to the Company to ensure enforcement of this provision. The Company has, therefore, concluded that MDU Resources will not have a voting interest of greater than 10%. MDU Resources will not have the ability to influence decisions of the Company and, as a result, MDU Resources will not meet the definition of a “Principal Owner” of the Company.

Read in the reply
Selected Historical and Pro Forma Consolidated Financial Data, page 52
SEC asked (1)
We note your disclosure of EBITDA Margin and Adjusted EBITDA Margin on a consolidated basis. Please revise your disclosure here and in other areas of the filing where these non-GAAP measures are disclosed on a consolidated basis, to provide the most directly comparable GAAP measure with equal or greater prominence to comply with Item 10(e)(1)(i)(A) of Regulation S-K.
Rest of the question

Refer to Question 102.10(a) of the Compliance and Disclosure Interpreations for Non-GAAP Measures.

KNF answered
In response to the Staff’s comment, the Company respectfully advises the Staff that it has revised the disclosure in Selected Historical and Pro Forma Consolidated Financial Data, page 52 and in other areas of the filing where these non-GAAP measures are disclosed on a consolidated basis, to provide the most directly comparable GAAP measure, net income margin, with greater prominence than the non-GAAP measures.

Management’s Discussion and Analysis of Financial Condition and Results of Operations Liquidity and Capital Resources, page 93
Read in the reply
Management's Discussion and Analysis of Financial Condition and Results of Operations · Liquidity and Capital Resources, page 92
SEC asked (2)
We note your statement that “Knife River Holding Company targets a normalized capital structure of 2.5 times EBITDA through the net working capital cycle.” Please revise to clarify your meaning of normalized capital structure and net working capital cycle. Exhibits
KNF answered
In response to the Staff’s comment, the Company respectfully advises the Staff that it has revised the disclosure in Management’s Discussion and Analysis of Financial Condition and Results of Operations

– Liquidity and Capital Resources, page 93, to clarify the intended meaning with respect to the Company’s normalized capital structure and net working capital cycle.
Read in the reply
Management's Discussion and Analysis of Financial Condition and Results of Operations · Liquidity and Capital Resources, page 92
SEC asked (3)
We note your disclosure in various places throughout your information statement that in connection with the separation and distribution, Knife River Holding Company anticipates that it will incur indebtedness in an aggregate principal amount of up to $890 million, reflecting an aggregate principal amount of up to $700 million, consisting of some combination of term loans and other debt, issued in connection with the
Rest of the question

separation, and a Revolving Credit Facility of $350 million that Knife River Holding Company expects to enter into in connection with the separation, with $190 million of the facility withdrawn as of the separation date. Please disclose the material terms of these debt and credit agreements and please file a copy of such agreements as exhibits when they are available. Refer to Item 601(b) of Regulation S-K.

KNF answered
In response to the Staff’s comment, the Company respectfully advises the Staff that it has revised the disclosure on pages 143 to 146 to provide a summary of the material terms of the financing arrangements. The Company also advises the Staff to please refer to the Indenture, filed as Exhibit 4.2.
Read in the reply
Notes to Unaudited Pro Forma Consolidated Financial Statements · Note 2 - Transaction Accounting Adjustments, page 59
SEC asked
With regard to pro forma adjustment F, please provide us with a reconciliation of the 57,033,536 shares of Knife River Holding Company common stock to be issued on a pro forma basis pursuant to the separation and distribution agreement.
KNF answered
We respectfully acknowledge the Staff’s comment and have provided below a reconciliation for the 57,033,536 shares of Knife River Holding Company common stock to be issued on a pro forma basis as outlined in adjustment F of the Notes to the Unaudited Pro Forma Consolidated Financial Statements.

The following is a reconciliation of the number of shares of Knife River Holding Company common stock to be issued on a pro forma basis:

Total shares of Knife River Holding Company common stock issued

MDU Resources – Outstanding shares as of 3/31/2023

204,162,814

MDU Resources shares held by Knife
Rest of the answer

River Corporation as “Parent stock held by subsidiary” as of 3/31/2023

538,921

Total MDU Resources outstanding shares as of 3/31/2023 (1)

203,623,893

Conversion Ratio – MDU Resources to Knife River Holding Company share conversion ratio of the 90% common stock held by the public

0.25

Knife River Holding Company common stock to be held by the public, representing 90% of the outstanding Knife River Holding Company common stock

50,905,974

% of shares owned by MDU Resources

10.0%

Shares owned by MDU Resources

5,656,219

Total shares of Knife River Holding Company common stock outstanding

56,562,193

Treasury shares issued in hook stock exchange

471,343

57,033,536

(1) Represents the number of MDU Resources common shares outstanding as of March 31, 2023, less the number of shares of MDU Resources common stock held by Knife River Corporation as Parent stock held by subsidiary as of March 31, 2023. Per the terms of the separation and distribution agreement, the conversion ratio is applied only to those MDU Resources common shares not held by

Knife River Corporation. The 538,921 shares of MDU Resources common stock held by Knife River Corporation are separately exchanged for 471,343 shares of Knife River Holding Company per the terms of the hook stock exchange.

Read in the reply

Also in this review: company letter, May 8, 2023

From the SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), 13 letters filed since 2023-01-13. Questions and answers are matched by their numbers; topics come from words in each question. The reports are compared word for word (same form, before the first SEC letter against the first report after the company's reply). No AI.

Sources

The SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), matched question by question. No AI.

Also

Filings: the letters in the filing list.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/KNF/export.csv") into a cell.

Next in Owners and insiders:Insider trades
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.