Form 10-K for the Fiscal Year Ended December 31, 2021
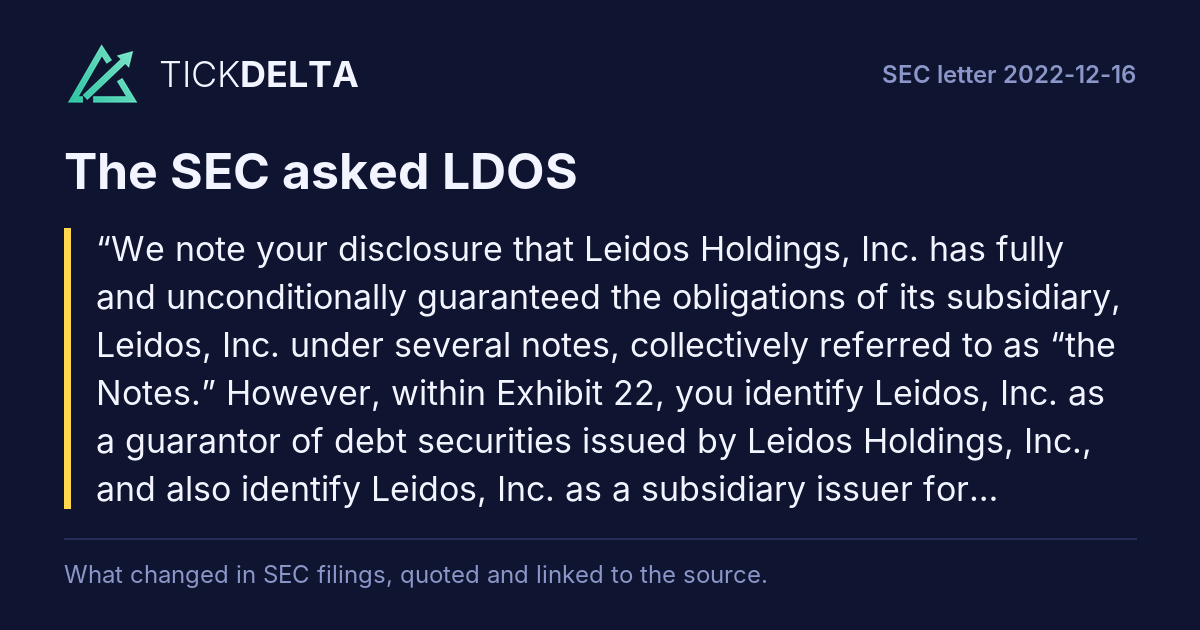
We note your disclosure that Leidos Holdings, Inc. has fully and unconditionally guaranteed the obligations of its subsidiary, Leidos, Inc. under several notes, collectively referred to as “the Notes.” However, within Exhibit 22, you identify Leidos, Inc. as a guarantor of debt securities issued by Leidos Holdings, Inc., and also identify Leidos, Inc.Rest of the question
as a subsidiary issuer for additional guaranteed securities not referenced in your disclosure on page 45. Please revise your disclosure, or update Exhibit 22, to reconcile the issuers, guarantors, and related guaranteed securities referenced on page 45 with those identified in Exhibit 22 or tell us why no revision is necessary. Refer to Rule 13-01(a) and (a)(1) of Regulation S-X and Item 601(b)(22)(i) of Regulation S-K.
No reply letter found.
First report after the SEC's letter of 2022-12-16: 10-K filed 2023-02-14 ↗, against the 10-K filed 2022-02-15 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
You disclose on page 45 that the underlying subsidiaries of Leidos, Inc. do not guarantee the obligations under the Notes and have been excluded from the financial information presented. We also note your presentation of “Investments in consolidated subsidiaries” as a line item within the summarized financial information disclosed on page 45.Rest of the question
Please tell us what this line item represents, and whether it includes investments in non-issuer and/or non-guarantor subsidiaries. In this regard, note that an issuer's or guarantor's investment in a subsidiary that is not an issuer or guarantor shall not be presented in the summarized financial information of issuers and guarantors of guaranteed securities required by Rule 13-01(a)(4) of Regulation S-X. Refer to Rule 13-01(a)(4)(iii) of Regulation S-X. In closing, we remind you that the company and its management are responsible for the accuracy and adequacy of their disclosures, notwithstanding any review, comments, action or absence of action by the staff.
No reply letter found.
First report after the SEC's letter of 2022-12-16: 10-K filed 2023-02-14 ↗, against the 10-K filed 2022-02-15 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: closing letter, 2023-02-15