Screener / SEC EDGAR /CIK 0001547903 /10-K filed Feb 12, 2026, compared with Feb 14, 2025 /Numbers from the XBRL of the 10-Ks
Nasdaq Financials · Surety Insurance

NMI Holdings, Inc. NMIH

Compare with peers Embed
New in the 10-K 4 paragraphs with nothing like them in the 10-K filed Feb 14, 2025 New in the 10-Q 20 paragraphs not in the 10-Q filed Jul 31, 2026 10-Q against the 10-K 2 risk factor paragraphs and sentences added or reworded

New risk paragraphs, branching off last year

Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Feb 14, 2025. A box jumps to the paragraph as filed, below.

4 new

Paragraphs with nothing like them in last year's 10-K

Quoted exactly

4 paragraphs in Risk Factors of the 10-K filed Feb 12, 2026 with nothing like them in the 10-K filed Feb 14, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.

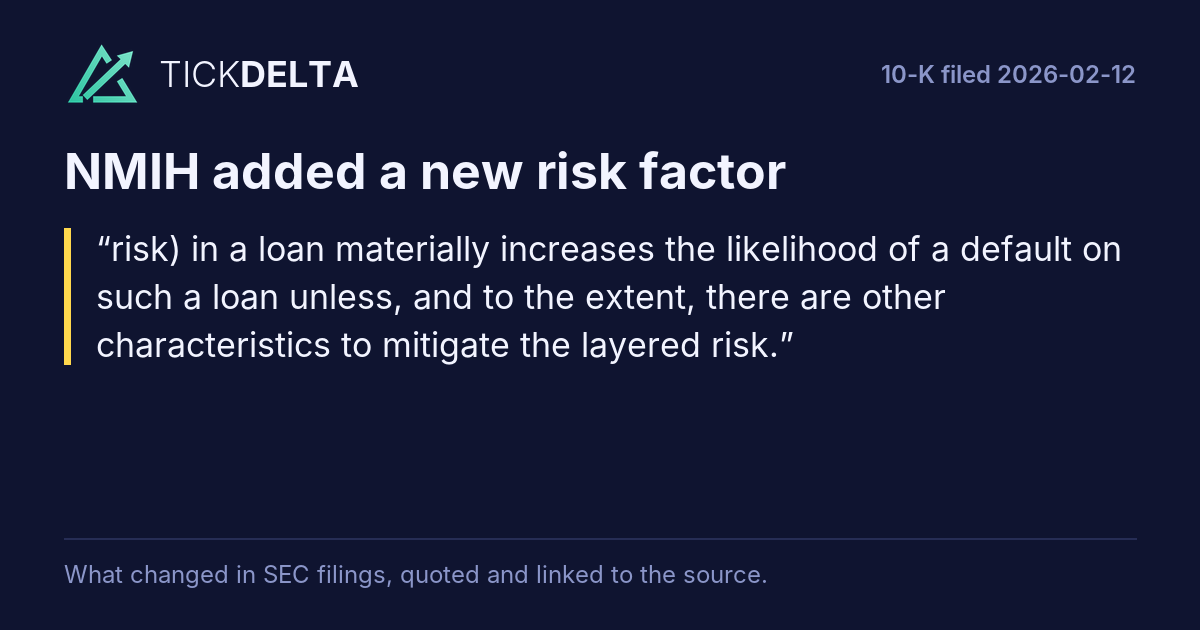
risk) in a loan materially increases the likelihood of a default on such a loan unless, and to the extent, there are other characteristics to mitigate the layered risk.

Read in the 10-K

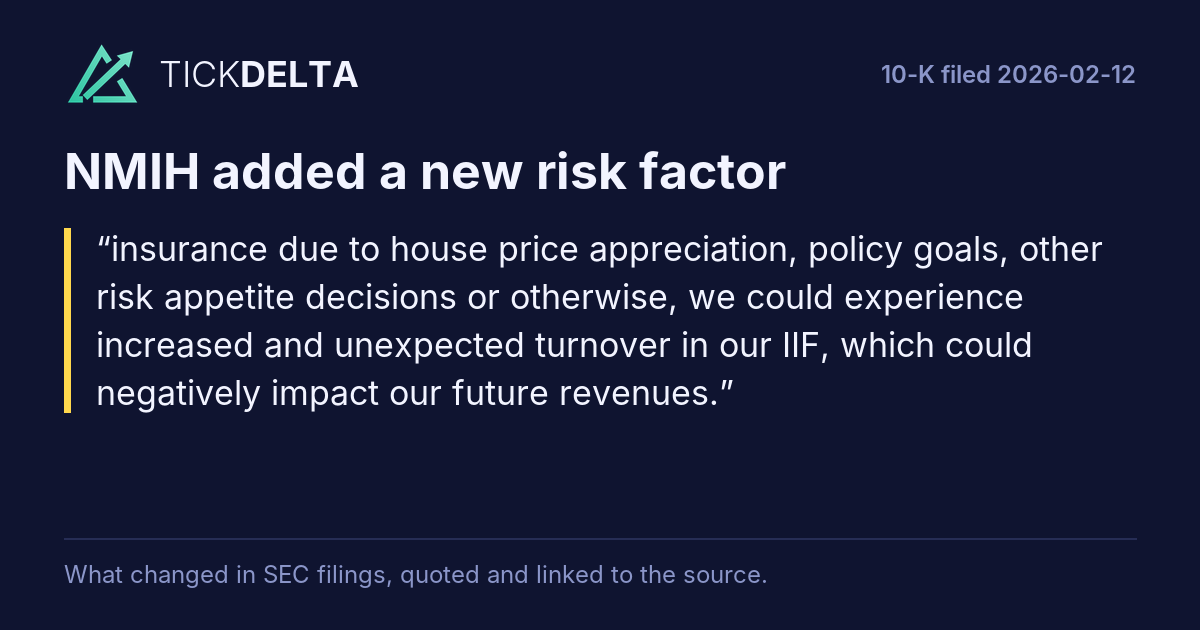
insurance due to house price appreciation, policy goals, other risk appetite decisions or otherwise, we could experience increased and unexpected turnover in our IIF, which could negatively impact our future revenues.

Read in the 10-K

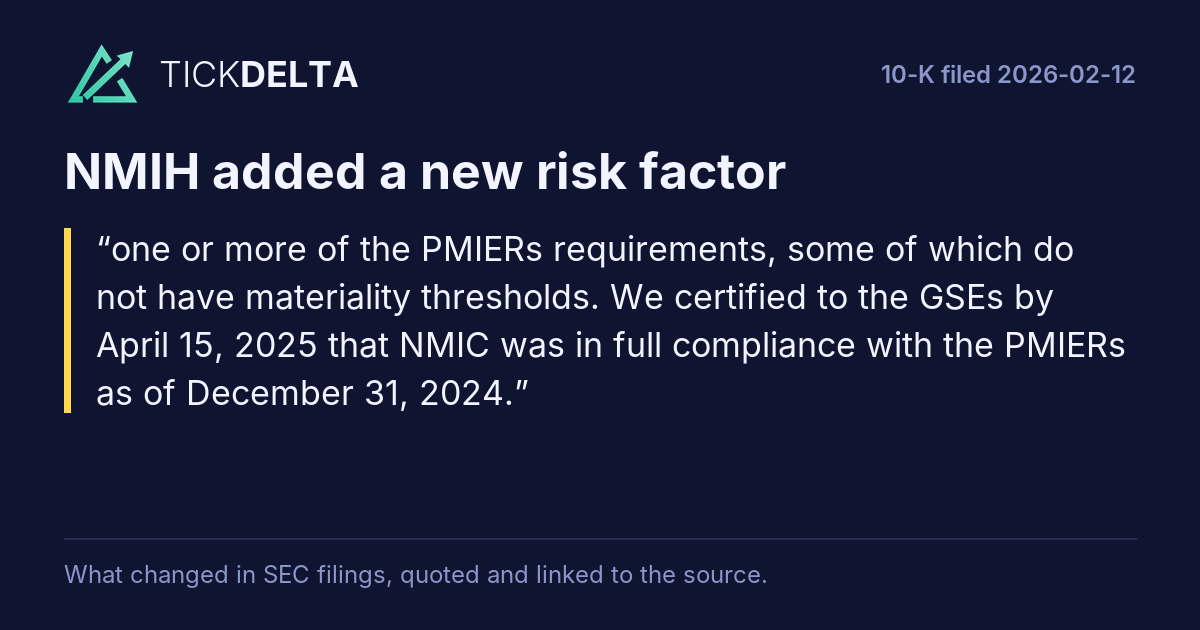
one or more of the PMIERs requirements, some of which do not have materiality thresholds. We certified to the GSEs by April 15, 2025 that NMIC was in full compliance with the PMIERs as of December 31, 2024.

Read in the 10-K

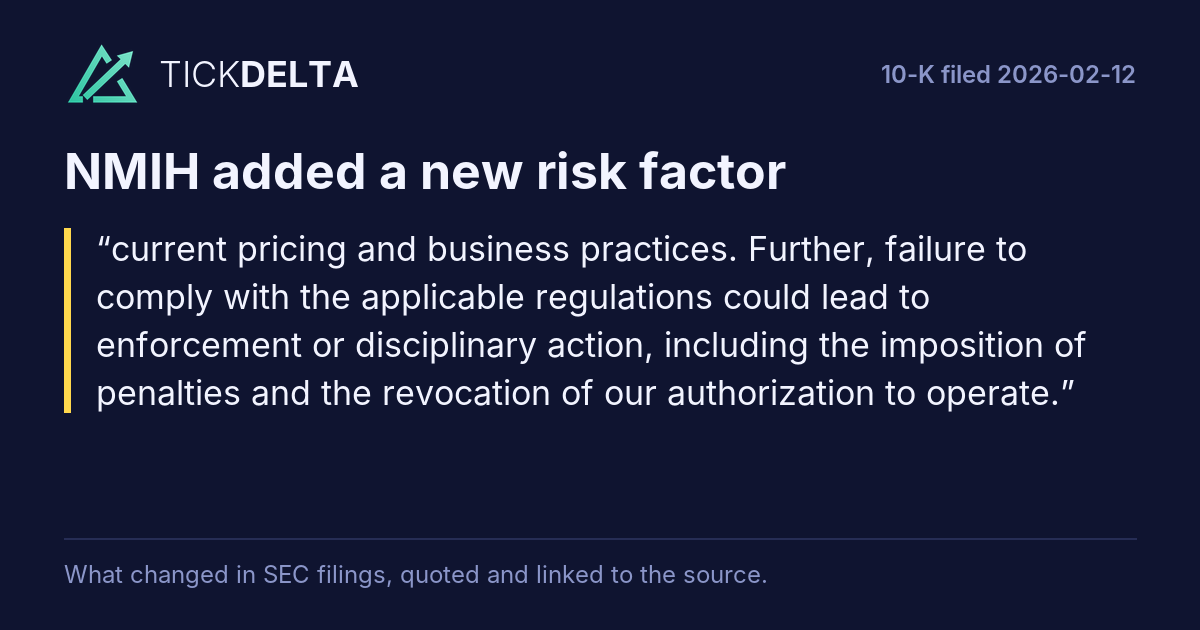
current pricing and business practices. Further, failure to comply with the applicable regulations could lead to enforcement or disciplinary action, including the imposition of penalties and the revocation of our authorization to operate.

Read in the 10-K

Paragraphs in the 10-Q filed Nov 6, 2026 that were not in the one before

New in the latest 10-Q

20 paragraphs in the 10-Q filed Nov 6, 2026 with nothing like them in the 10-Q filed Jul 31, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.

Financial statements and notes

The following table presents the components of net realized investment gains (losses):

Read in the 10-Q

(5) Includes $ 1.0 million, net of reinsurance, paid in connection with the commutation of coverage on delinquent loans during the nine months ended September 30, 2026.

Read in the 10-Q

On October 22, 2026, the President issued Executive Order "Decreasing Housing Costs for the American People," which, among other things, allows the Director of the FHFA, if he determines it to be in the best interests of the GSEs, the FHFA and the American public, to direct the GSEs to establish a pilot program to identify borrowers who satisfy equity-related and other requirements for cancellation of mortgage insurance, applicable only to mortgages made after the establishment of the pilot program. The implementation details and regulatory guidance necessary to fully assess the scope and effect of the executive order have not yet been issued, and we will continue to monitor developments as they become available.

Read in the 10-Q

(1) Includes delinquent loans removed from default inventory upon commutation of coverage.

Read in the 10-Q

(5) Includes $1.0 million, net of reinsurance, paid in connection with the commutation of coverage on delinquent loans during the three and nine months ended September 30, 2026.

Read in the 10-Q
Show the other 15

(1) Represents loans removed from default inventory upon commutation of coverage.

Read in the 10-Q

Risk Factors

Changes in the business practices of the GSEs, including a decision to decrease or discontinue the use of private MI, or changes in the terms on which mortgage insurance coverage may be canceled, federal legislation that changes their charters or a restructuring of the GSEs or changes in loan delivery pricing imposed by the GSEs could reduce the private MI market opportunity, reduce our revenues or increase our losses.

Read in the 10-Q

The requirements and practices of the GSEs impact the operating results and financial performance of approved insurers, including NMIC. Changes in the charters or business practices of the GSEs could materially reduce the number of mortgages they purchase that are insured by us and consequently diminish our franchise value. The GSEs could be directed to make such changes by the FHFA, which was appointed as their conservator in September 2008 and has the authority to control and direct the operations of the GSEs.

Read in the 10-Q

With the GSEs in a prolonged conservatorship, there has been ongoing debate over the future role and purpose of the GSEs in the U.S. housing market. The U.S. Congress may legislate, or the administration may implement through administrative reform, structural and other changes to the GSEs and the functioning of the secondary mortgage market. Since 2011, there have been numerous legislative proposals intended to incrementally scale back the GSEs (such as a statutory mandate for the GSEs to transfer mortgage credit risk to the private sector) or to completely reform the housing finance system. Congress, however, has not enacted any legislation to date. The proposals vary with regard to the government's role in the housing market and, more specifically, with regard to the existence of an explicit or implicit government guarantee. Recently, there has been increased focus on and discussion of administrative reform independent of legislative action. The former director of FHFA leadership under the first Trump administration was more focused on preparing the GSEs to exit from conservatorship by increasing the GSEs’ overall capital levels and reducing their credit risk profile. In December 2020, the FHFA published a final rule (2020 ERCF rule) establishing a new enterprise regulatory capital framework (ERCF) for the GSEs, which included provisions governing the capital

Read in the 10-Q

relief allowed to the GSEs for loans with private MI. The 2020 ERCF rule established that loans with private MI, as opposed to loans without private MI, provide more favorable capital relief to the GSEs. Additionally, while in conservatorship, each GSE has been subject to the terms of senior Preferred Stock Purchase Agreements (PSPAs) establishing Treasury's ownership of senior preferred stock and warrants in the GSEs. The PSPAs, as amended by the Treasury Department in collaboration with the FHFA, also establish Treasury's right to consent to any GSE release from conservatorship, among other rights.

Read in the 10-Q

Leadership at the FHFA changes from time to time. Given that the Director of the FHFA is removable by the President at will, the agency's agenda, policies and actions likely will be significantly influenced by the then current administration. Accordingly, it is difficult to predict whether or how the FHFA might seek to implement GSE oversight beyond the current administration's term. Between the Director of the FHFA and the Treasury Department, they possess significant capacity to effect administrative GSE reforms. Subsequent to the adoption of the 2020 ERCF rule and the PSPAs, the Director of the FHFA, together with the Treasury Department, have adopted amendments to both the 2020 ERCF and the PSPAs to help facilitate the ultimate release of the GSEs from conservatorship and additional changes could be adopted. Further changes to the ERCF, the PSPAs, or the business practices of the GSEs, including any that increase the capital required to be held by us under PMIERs, could make our products less desirable or more expensive and could have a material adverse impact on our financial condition and future business prospects.

Read in the 10-Q

Other potential GSE reforms, whether through legislation or administrative action, could impact the current role of private mortgage insurance as credit enhancement, including its reduction or elimination, which would have an adverse effect on our revenue, operating results, prospects or financial condition. Some other examples of potential GSE reforms or policy changes that could impact our business may also include, but are not limited by, the following:

Read in the 10-Q

• Policies or requirements that may result in a reduction in the number of mortgages GSEs acquire;

Read in the 10-Q

• The terms on which mortgage insurance coverage may be canceled, including GSE requirements and programs that permit cancellation prior to reaching the cancellation thresholds and conditions established by law;

Read in the 10-Q

• The terms required to be included in master policies for the mortgage insurance policies GSEs acquire;

Read in the 10-Q

• The amount of loan level price adjustments or guarantee fees that the GSEs charge on loans that require mortgage insurance; and

Read in the 10-Q

• The degree of influence that the GSEs have over a mortgage lender’s selection of the mortgage insurer providing coverage.

Read in the 10-Q

On October 22, 2026, the President issued Executive Order "Decreasing Housing Costs for the American People," which, among other things, allows the Director of the FHFA, if he determines it to be in the best interests of the GSEs, the FHFA and the American public, to direct the GSEs to establish a pilot program to identify borrowers who satisfy equity-related and other requirements for cancellation of mortgage insurance, applicable only to mortgages made after the establishment of the pilot program. The implementation details and regulatory guidance necessary to fully assess the scope and effect of the order have not yet been issued, and we will continue to monitor developments as they become available. To the extent the implementation details, regulatory guidance or other impacts of the executive order cause increased and unexpected turnover in our IIF, our future revenues may be negatively impacted. For more information see our risk factor titled “Changes in factors that impact the length of time that our policies remain in force may adversely impact our future revenues and claims experience. ”

Read in the 10-Q

As a result of these matters, it is uncertain what role private capital, including MI, will play in the domestic residential housing finance system in the future or the impact of any such changes on our business. Any changes to the charters or statutory authorities of the GSEs would require Congressional action to implement. Passage and timing of any comprehensive GSE reform or incremental change (legislative or administrative) is uncertain, making the actual impact on us and our industry difficult to predict. Any such changes that come to pass could have a significant impact on our business.

Read in the 10-Q

In recent years, the FHFA has set goals for the GSEs to transfer significant portions of the GSEs' mortgage credit risk to the private sector. To the extent any other current or potential credit risk products that may evolve in a manner that displace primary MI coverage, the amount of insurance we write may be reduced. It is difficult to predict the impact of any other current or potential alternative credit risk transfer products, if any, that are developed to meet the goals established by the FHFA.

Read in the 10-Q

The 10-Q's risk factors against the 10-K

Item 1A of the 10-Q filed Nov 6, 2026 against Item 1A of the 10-K filed Feb 12, 2026. A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed. Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed, Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal (cut words struck through, new words highlighted). Text on the page, not a score; each links to the filing at sec.gov.

Added10-Q Nov 6, 2026 vs 10-K Feb 12, 2026
Risk factors that affect our business and financial results are discussed in Part I, Item 1A of our 2025 10-K. As of the date of this report, other than as indicated below, we are not aware of any material changes in our risk factors from the risk factors disclosed in our 2025 10-K. You should carefully consider the risks and uncertainties described herein and in our 2025 10-K, which have the potential to affect our business, financial condition, results of operations, cash flows or prospects in a material and adverse manner. The risks described herein and in our 2025 10-K are not the only risks we face, as there are additional risks and uncertainties not currently known to us or that we currently deem to be immaterial, which may in the future adversely affect our business, financial condition and/or operating results.

Read it in the 10-Q at sec.gov

Added10-Q Nov 6, 2026 vs 10-K Feb 12, 2026
On October 22, 2026, the President issued Executive Order "Decreasing Housing Costs for the American People," which, among other things, allows the Director of the FHFA, if he determines it to be in the best interests of the GSEs, the FHFA and the American public, to direct the GSEs to establish a pilot program to identify borrowers who satisfy equity-related and other requirements for cancellation of mortgage insurance, applicable only to mortgages made after the establishment of the pilot program. The implementation details and regulatory guidance necessary to fully assess the scope and effect of the order have not yet been issued, and we will continue to monitor developments as they become available. To the extent the implementation details, regulatory guidance or other impacts of the executive order cause increased and unexpected turnover in our IIF, our future revenues may be negatively impacted. For more information see our risk factor titled “Changes in factors that impact the length of time that our policies remain in force may adversely impact our future revenues and claims experience. ”

Read it in the 10-Q at sec.gov

Phrases used for the first time

Two-word phrases in Risk Factors of the 10-K filed Feb 12, 2026 that are in none of the 1 earlier 10-Ks stored, back to Feb 14, 2025

third-party usps ×2canceled federal ×2
Where each one is used
  • third-party usps: •We outsource the underwriting of our mortgage insurance on certain loans to third-party USPs. If these USPs fail to adequately perform their underwriting services or place our coverage on loans we would deem ineligible, we could experience increased claims on loans underwritten by them, and our customer...
  • canceled federal: •Changes in the business practices of the GSEs, including a decision to decrease or discontinue the use of private MI, or changes in the terms on which mortgage insurance coverage may be canceled, federal legislation that changes their charters or a restructuring of the GSEs or changes in loan delivery pricing...

The 10-K at sec.gov

Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.

What was taken out

4 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.

Across all companies
We are exposed to various risks arising out of natural disasters, including pandemics, earthquakes, wildfires, hurricanes, floods, tornadoes and other events that could be related to and could be worsened by changing climatic conditions. We are also exposed to various risks arising out of man-made disasters, including acts of terrorism, and military actions. For example, a
In the 10-K filed Feb 14, 2025
observed in recent years prior to 2022, and therefore decreased turnover in our IIF. Despite the Federal Reserve lowering interest rates in 2024, the 10-year Treasury yield and 30-year fixed rate mortgage interest rates remained elevated.
In the 10-K filed Feb 14, 2025
•expenses incurred in connection with changes in our stock price, such as changes in the value of the liability reflected on our financial statements associated with outstanding warrants;
In the 10-K filed Feb 14, 2025
stolen, lost or misused, making information accessible through such devices more vulnerable to unauthorized access, including by employee malfeasance.
In the 10-K filed Feb 14, 2025

Sources

Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.

Also

10-K change: what was reworded or cut, section by section.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/NMIH/export.csv") into a cell.

Next:10-K change
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.