Screener / SEC EDGAR /CIK 0001757073 /10-K filed Feb 12, 2026, compared with Feb 13, 2025 /Numbers from the XBRL of the 10-Ks
NYSE Health care · Dental Equipment & Supplies

Envista Holdings Corp NVST

Compare with peers Embed
New in the 10-K 1 paragraphs with nothing like them in the 10-K filed Feb 13, 2025 New in the 10-Q 6 paragraphs not in the 10-Q filed Aug 5, 2026 10-Q against the 10-K 1 risk factor paragraphs and sentences added or reworded

New risk paragraphs, branching off last year

Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Feb 13, 2025. A box jumps to the paragraph as filed, below.

1 new

Paragraphs with nothing like them in last year's 10-K

Quoted exactly

1 paragraph in Risk Factors of the 10-K filed Feb 12, 2026 with nothing like it in the 10-K filed Feb 13, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.

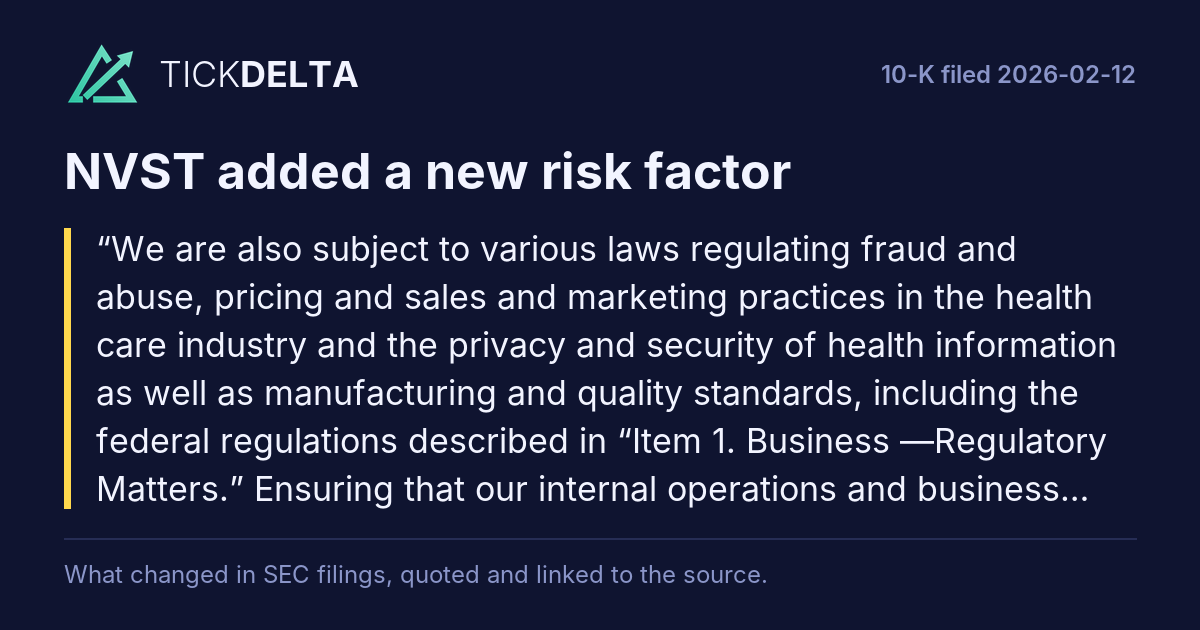
We are also subject to various laws regulating fraud and abuse, pricing and sales and marketing practices in the health care industry and the privacy and security of health information as well as manufacturing and quality standards, including the federal regulations described in “Item 1. Business —Regulatory Matters.” Ensuring that our internal operations and business arrangements with third parties comply with applicable healthcare laws and regulations involves substantial costs. It is possible that government authorities will conclude that our business practices do not comply with current or future statutes, regulations, agency guidance or case law involving applicable fraud and abuse or other healthcare laws and regulations.

Read in the 10-K

Paragraphs in the 10-Q filed Nov 4, 2026 that were not in the one before

New in the latest 10-Q

6 paragraphs in the 10-Q filed Nov 4, 2026 with nothing like them in the 10-Q filed Aug 5, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.

Financial statements and notes

October 2, 2026 December 31, 2025 ─────────────────────────────────────────────────────────────────────────────────────────── Qualifying Net Investment Hedges: Derivative hedging instruments: Other long-term liabilities $5.3 $10.2 Non-derivative hedging instruments: Long-term debt $506.3 $528.6 Non-Designated Hedge Derivatives: Accrued expenses and other liabilities, net $6.2 $—

Read in the 10-Q

On September 2, 2026, the Company entered into an agreement to lease building space in Irvine, California for its new corporate headquarters. The lease is expected to commence in early 2028, when the Company begins its regular business activities at the premises following completion of leasehold improvements. Aggregate future fixed lease payments are expected to total approximately $ 34.2 million, before the effects of contractual rent abatement and other lease provisions. Lease payments are expected to begin on October 1, 2028.

Read in the 10-Q

No right-of-use asset or lease liability has been recognized as of October 2, 2026 because the lease has not yet commenced. Accordingly, the Company did not recognize any lease expense related to this lease during the three and nine months ended October 2, 2026.

Read in the 10-Q

During the three months ended October 2, 2026, the Company completed the dissolution of certain legal entities, resulting in the reclassification of a cumulative foreign currency translation gain of $ 428.1 million from OCI to earnings and is presented within the realized cumulative foreign currency gain line item in the Condensed Consolidated Statement of Operations.

Read in the 10-Q

Realized cumulative foreign currency translation gain represents the reclassification of cumulative foreign currency translation adjustments from Accumulated Other Comprehensive Income (Loss) to earnings following the dissolution of certain legal entities during the three and nine months ended October 2, 2026. The gain was recognized within realized cumulative foreign currency translation gain in the Condensed Consolidated Statements of Operations.

Read in the 10-Q
Show the other 1

On September 2, 2026, we entered into an agreement to lease building space in Irvine, California for our new corporate headquarters. The lease is expected to commence in early 2028, when we begin our regular business activities at the premises following completion of leasehold improvements. Aggregate future fixed lease payments are expected to total approximately $34.2 million, before the effects of contractual rent abatement and other lease provisions. Lease payments are expected to begin on October 1, 2028

Read in the 10-Q

The 10-Q's risk factors against the 10-K

Item 1A of the 10-Q filed Nov 4, 2026 against Item 1A of the 10-K filed Feb 12, 2026. A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed. Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed, Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal (cut words struck through, new words highlighted). Text on the page, not a score; each links to the filing at sec.gov.

Added10-Q Nov 4, 2026 vs 10-K Feb 12, 2026
You should carefully consider the factors discussed in Part I, “Item 1A. Risk Factors” in our 2025 10-K and in Part II, “Item 1A. Risk Factors” in our Quarterly Report on Form 10-Q for the quarter ended April 3, 2026 (“Q1 10-Q”), which could materially affect our business, financial position, or future results of operations. The risks described in our 2025 10-K and Q1 10-Q, are not the only risks we face. Additional risks and uncertainties not currently known to us or that we currently deem to be immaterial also may materially adversely affect our business, financial position, or future results of operations.

Read it in the 10-Q at sec.gov

Phrases used for the first time

Two-word phrases in Risk Factors of the 10-K filed Feb 12, 2026 that are in none of the 1 earlier 10-Ks stored, back to Feb 13, 2025

intelligence systems ×4retaliatory tariffs ×4intelligence technologies ×3indenture governing ×3incorporate artificial ×2matters data ×2emissions disclosures ×2sustainability reporting ×2organizations dsos ×2
Where each one is used
  • intelligence systems: •Our growing use of artificial intelligence systems to automate processes and analyze data poses inherent risks.
  • retaliatory tariffs: In particular, trade tensions between the U.S. and China have led to increased tariffs and trade restrictions. The U.S. has significantly increased tariffs on products imported from China into the U.S. and implemented new tariffs on imports into the U.S. from other countries, particularly from Canada, Mexico, and...
  • intelligence technologies: We have and are continuing to incorporate artificial intelligence, including machine learning, in certain of our internal operations and into certain of our products and services, with the intent to enhance their operation and effectiveness. For example, we have incorporated machine-learning into certain of our...
  • indenture governing: Holders of the Notes may require us to repurchase their Notes following a fundamental change at a cash repurchase price generally equal to the principal amount of the Notes to be repurchased, plus accrued and unpaid interest, if any. In addition, upon conversion, we will satisfy part or all of our conversion...
  • incorporate artificial: We have and are continuing to incorporate artificial intelligence, including machine learning, in certain of our internal operations and into certain of our products and services, with the intent to enhance their operation and effectiveness. For example, we have incorporated machine-learning into certain of our...
  • matters data: We have and are continuing to incorporate artificial intelligence, including machine learning, in certain of our internal operations and into certain of our products and services, with the intent to enhance their operation and effectiveness. For example, we have incorporated machine-learning into certain of our...
  • emissions disclosures: The regulations surrounding greenhouse gas emissions disclosures and sustainability reporting have also continued to evolve, with compliance requirements varying by jurisdiction. Governments, regulatory bodies and other stakeholders vary in their support of or opposition to sustainability and environmental matters...
  • sustainability reporting: The regulations surrounding greenhouse gas emissions disclosures and sustainability reporting have also continued to evolve, with compliance requirements varying by jurisdiction. Governments, regulatory bodies and other stakeholders vary in their support of or opposition to sustainability and environmental matters...

The 10-K at sec.gov

Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.

What was taken out

19 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.

Across all companies
We are also subject to the General Data Protection Regulation (“GDPR”), the primary data protection law in the European Economic Area, including the European Union (collectively, the “EU”), as well as associated EU member state data protection laws and the UK GDPR in the United Kingdom. These laws impose significant requirements for covered businesses (controllers and processors) of personal data, including, for example, standards for obtaining consent from individuals to process their personal data, disclosures to individuals, an individual data rights regime, specified timelines for data...
In the 10-K filed Feb 13, 2025
Violation of state privacy, security, and breach notification laws can trigger significant monetary penalties. Certain of the states’ privacy, security, and data breach laws, including, for example, the CCPA, include private rights of action that may expose us to private litigation regarding our privacy and security practices and significant damages awards or settlements in civil litigation. The CPRA, which went into effect on January 1, 2023, significantly amended the CCPA and imposed additional data protection obligations on covered businesses, including additional consumer rights...
In the 10-K filed Feb 13, 2025
The option counterparties are financial institutions, and we will be subject to the risk that any or all of them might default under the Capped Calls. Our exposure to the credit risk of the option counterparties will not be secured by any collateral. Past global economic conditions have resulted in the actual or perceived failure or financial difficulties of many financial institutions. If an option counterparty becomes subject to insolvency proceedings, we will become an unsecured creditor in those proceedings with a claim equal to our exposure at that time under the Capped Calls with...
In the 10-K filed Feb 13, 2025
The Health Information Technology for Economic and Clinical Health (“HITECH”) Act was enacted as an update to HIPAA and makes business associates of covered entities directly liable for compliance with certain HIPAA requirements, strengthens the limitations on the use and disclosure of protected health information without individual authorizations, and contemplates enforcement of noncompliance with HIPAA due to willful neglect. These changes have stimulated increased enforcement activity and enhanced the potential that health care providers will be subject to financial penalties for...
In the 10-K filed Feb 13, 2025

Sources

Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.

Also

10-K change: what was reworded or cut, section by section.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/NVST/export.csv") into a cell.

Next:10-K change
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.