Form 10-K
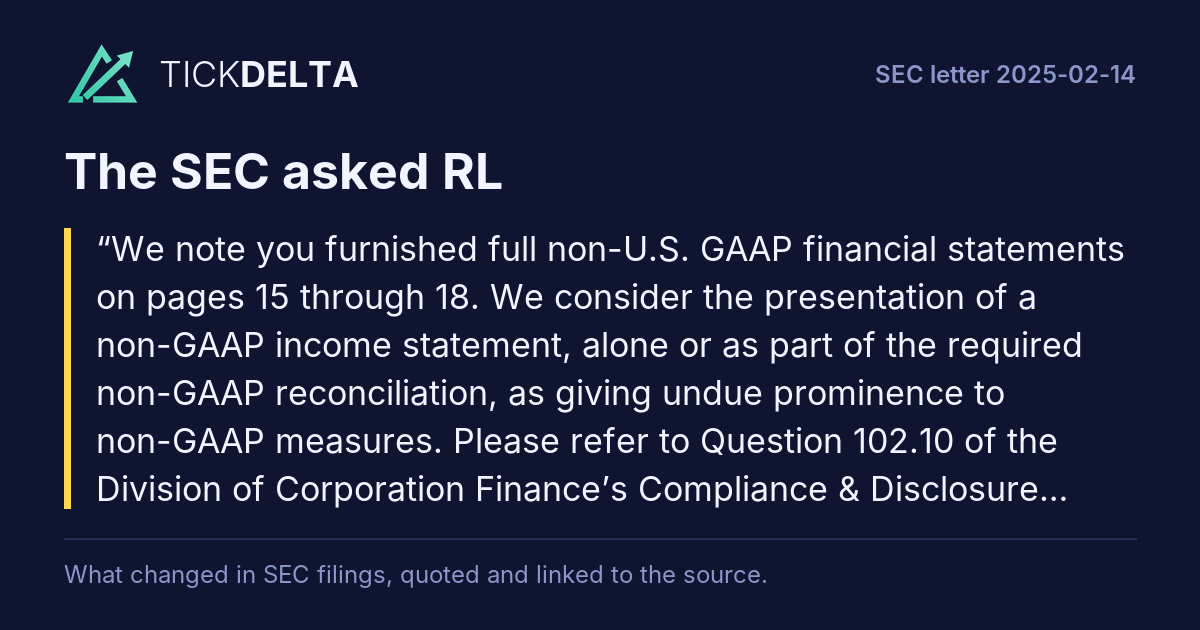
We note you furnished full non-U.S. GAAP financial statements on pages 15 through 18. We consider the presentation of a non-GAAP income statement, alone or as part of the required non-GAAP reconciliation, as giving undue prominence to non-GAAP measures.Rest of the question
Please refer to Question 102.10 of the Division of Corporation Finance’s Compliance & Disclosure Interpretations on Non-GAAP Financial Measures and revise to remove this presentation in future filings as necessary. Footnotes to Reconciliation of Non-U.S. GAAP Financial Measures, page 19 We note adjustments (f) and (g) exclude marketing and advertising expenses. Explain how you determined it is appropriate based on the guidance in Question 100.01 of the Division of Corporation Finance's Compliance & Disclosure Interpretations on Non- GAAP Financial Measures since it appears the adjustments represent normal 2. operating expenses related to your business. Please advise or revise your future filings to remove these adjustments. Management's Discussion and Analysis of Financial Condition and Results of Operations Results of Operations Gross Profit, page 52 3. We note your disclosure that gross profit as a percentage of net revenues is dependent upon a variety of factors, including changes in the relative sales mix among distribution channels, changes in the mix of products sold, pricing, the timing and level of promotional activities, foreign currency exchange rates, and fluctuations in product costs. Please revise your future filings to quantify the extent to which changes in gross profit, as well as changes in segment operating margins (discussed on page 54) were materially impacted by changes in volume, product mix, and price. In this regard, expand your disclosure to explain any increases/decreases in segment net revenues (discussion starting on page 51) resulting from changes in volume of products sold, changes in average unit retail, and to quantify the impact of each of these underlying drivers. See Item 303(b)(2)(iii) of Regulation S-K. In closing, we remind you that the company and its management are responsible for the accuracy and adequacy of their disclosures, notwithstanding any review, comments, action or absence of action by the staff.
We respectfully acknowledge the
Staff's comment. In future filings, we will revise the presentation of our non-GAAP reconciliations to provide a separate reconciliation for each non-GAAP measure. This will ensure that such reconciliations do not resemble a non-GAAP income statement, in accordance with the guidance provided in Question 102.10 of the Division of Corporation Finance’s Compliance & Disclosure Interpretations on
Non-GAAP Financial Measures. Read in the reply ↗
First report after the company's reply of 2025-02-28: 10-K filed 2025-05-22 ↗, against the 10-K filed 2024-05-23 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: closing letter, 2025-03-04