Form 10-K
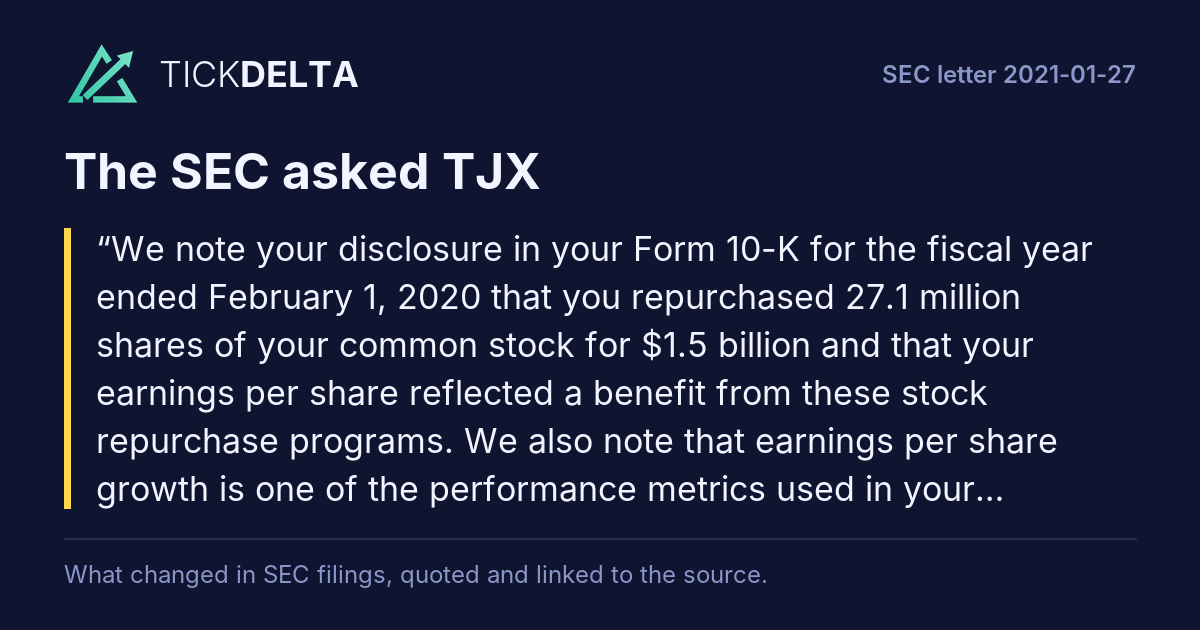
We note your disclosure in your Form 10-K for the fiscal year ended February 1, 2020 that you repurchased 27.1 million shares of your common stock for $1.5 billion and that your earnings per share reflected a benefit from these stock repurchase programs.Rest of the question
We also note that earnings per share growth is one of the performance metrics used in your longterm equity incentive programs and specifically with respect to your Performance Share Units. In future filings, please discuss if and how your stock repurchase programs affected the manner in which the Executive Compensation Committee set the relevant targets used in your long-term equity incentive programs and determined if such targets were achieved. Refer to Item 402(b)(2) of Regulation S-K.
TJX acknowledges the Staff’s comment and advises the Staff of disclosure regarding this matter on page 34 of TJX’s Definitive Proxy Statement on Schedule 14A filed April 23, 2020 (the “2020 Proxy”), where TJX discloses that it excludes the impact of unbudgeted buybacks from the EPS growth performance metric used for its long-term performance
770 Cochituate Road,
500-1CN, Framingham, Massachusetts 01701
Page share unit (PSU) program.Read in the reply ↗Rest of the answer
In future filings, TJX will include such disclosure in the section where it describes in detail the calculation of payouts based on an EPS growth performance metric for purposes of its long-term incentive program, in order to clarify that unbudgeted buybacks pursuant to the stock repurchase program do not impact the calculation of the EPS growth performance metric under the terms pre-established by the Executive Compensation Committee (the “ECC”).
First report after the company's reply of 2021-02-24: 10-K filed 2021-03-31 ↗, against the 10-K filed 2020-03-27 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
We note your disclosure on page 16 that you use both adjusted annual pre-tax income and adjusted total annual sales to determine payouts under your management incentive program. It appears that these are non-GAAP financial measures. In future filings, please provide disclosure regarding how any non-GAAP numbers are calculated from your audited financial statements.Rest of the question
We note that we are unable to determine the certain adjustments from your audited financial statements resulting in pre-tax income of $4,934,769 and total sales of $41,795,008. See Instruction 5 to Item 402(b) of Regulation S-K.
TJX acknowledges the Staff’s comment and confirms that in future filings, to the extent applicable, it will include an explanation of the calculation of adjusted annual pre-tax income and adjusted total annual sales from its audited financial statements, as well as disclosure on the calculation of other non-GAAP numbers from its audited financial statements, with respect to determination of payouts under TJX’s Management Incentive Plan (MIP).
For example, with respect to the calculation of adjusted annual pre-tax income and adjusted total annual sales applicable to the determination ofRead in the reply ↗Rest of the answer
payouts under TJX’s Management Incentive Plan (MIP) for fiscal 2020, TJX notes footnote 1 to the “Fiscal 2020 MIP Goals and Results” table that appears on page 36 of the 2020 Proxy would have been updated to clarify that (1) Actual Pre-Tax Income for MIP (in thousands) for fiscal 2020 ($4,934,768) was determined based on total segment profit (in thousands) reported in TJX’s Annual
Report on Form 10-K for fiscal 2020 ($4,972,954), adjusted under the terms pre-established by the ECC to reflect pre-established currency exchange rates (for translation of foreign income, intercompany charges and intra-division charges) and to exclude capitalized inventory costs and mark-to-market impact of inventory derivatives and (2) Actual Total Sales for MIP (in thousands) for fiscal 2020 ($41,795,008) was determined based on total net sales (in thousands) reported in TJX’s Annual Report on Form 10-K for fiscal 2020 ($41,716,977), adjusted to reflect pre-established currency exchange rates.
TJX notes that it does not anticipate disclosing non-GAAP financial measures with regard to the MIP performance goals in its filings for its fiscal year ended January 30, 2021 (“fiscal 2021”), and as a result, such disclosure regarding the calculations would not be applicable.
To the extent other non-GAAP financial measures for performance goals are included in its filings for fiscal 2021, TJX will include disclosure regarding how such non-GAAP numbers are calculated from the audited financial statements in accordance with Instruction 5 to Item 402(b) of Regulation S-K.
First report after the company's reply of 2021-02-24: 10-K filed 2021-03-31 ↗, against the 10-K filed 2020-03-27 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: request for more time, 2021-01-29, closing letter, 2021-03-04