Screener / SEC EDGAR /CIK 0001638826 /10-K filed Mar 25, 2026, compared with Apr 2, 2025 /Numbers from the XBRL of the 10-Ks
Nasdaq Technology · Software

ServiceTitan, Inc. TTAN

Compare with peers Embed
SEC comment letters, last 20 years

2 reviews of TTAN's filings by SEC staff

UPLOAD and CORRESP
Reviews 2 latest letter Oct 1, 2024
Questions asked 23 each answered in the company's own letter
No closing letter 2 reviews without a letter saying the staff completed it

When the SEC's staff reviews a filing, it writes to the company with numbered questions, and the company answers each one in a letter. SEC publishes the exchange once the review is over, at least 20 business days later. A question is not an accusation; most reviews end with the company adding detail to its next filing.

How the reviews went

Every review on EDGAR, from the first staff letter to the letter that closes it

  1. 1. Staff letters 5 UPLOAD
  2. 2. Questions in them 23 numbered comments
  3. 3. Company replies 4 CORRESP
  4. 4. Reviews closed 0 of 2 closing letter

Form S-1

2024-10-01 to 2024-12-09 · 6 questions · 3 letters from the SEC, 4 from the company
No closing letter
Revenue
SEC letter of Oct 1, 2024 ↗ no reply letter on EDGAR (the company may have answered in an amended filing)
SEC asked (1)
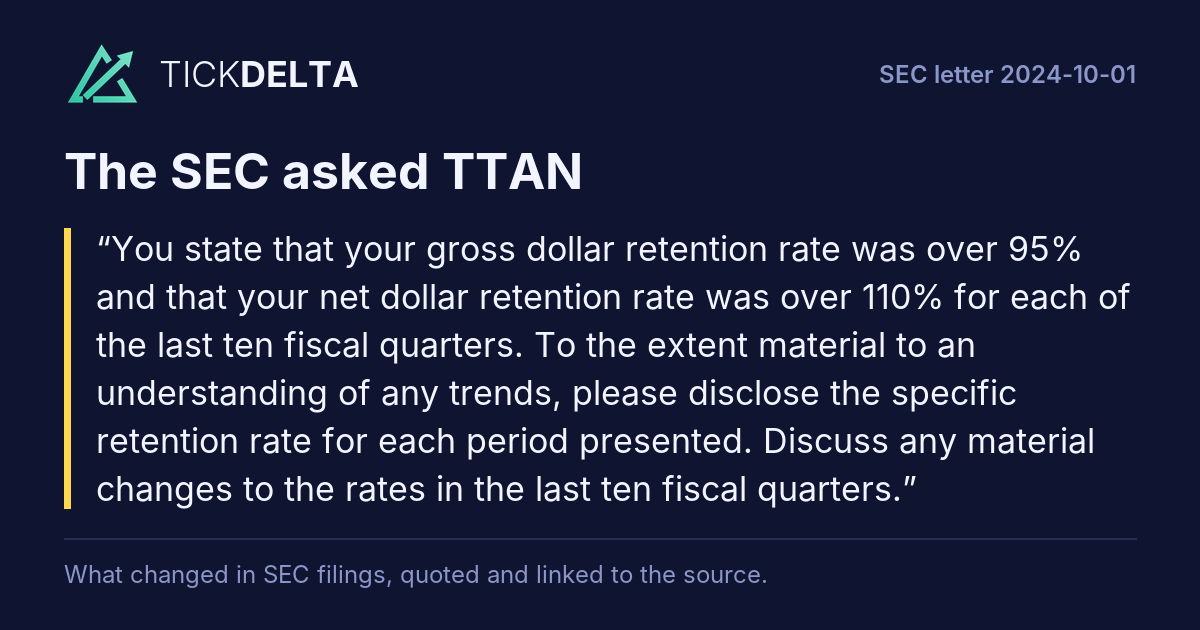
You state that your gross dollar retention rate was over 95% and that your net dollar retention rate was over 110% for each of the last ten fiscal quarters. To the extent material to an understanding of any trends, please disclose the specific retention rate for each period presented. Discuss any material changes to the rates in the last ten fiscal quarters.
TTAN answered

No reply letter found.

SEC asked (2)
You state that as of January 31, 2024, you served over 15,000 customers, and in fiscal 2023, fiscal 2024 and the 12 months ended July 31, 2023 and 2024, you processed over $40 billion, over $50 billion, over $45 billion and over $55 billion of Gross Transaction Volume. Please disclose the specific Gross Transaction Volumes and the number of customers for each of the periods.
TTAN answered

No reply letter found.

SEC asked (1)
We note your revised disclosure that your net dollar retention rate has declined slightly over the last ten fiscal quarters. Given your prominent disclosure throughout the filing that your net dollar retention rate and gross dollar retention rate is evidence of your ability to retain and expand customers, please provide balanced disclosure by providing appropriate context regarding the decrease in your net retention
Rest of the question

rate and/or gross retention rate. Disclose the amount of the decrease in rates over the period. Clarify whether management uses the annual net dollar retention rate and gross dollar retention rate to evaluate the company's business. Notes to Condensed Consolidated Financial Statements 14. Subsequent Events, page F-73

TTAN answered
The Company respectfully acknowledges the Staff’s comment and has revised the disclosure on pages 3, 92 and 122 of the Registration Statement accordingly.

The Company advises the Staff that management does not use net dollar retention rate or gross dollar retention rate to evaluate or operate the Company’s business.
Read in the reply
SEC asked (2)
You disclose the following: • Between July 31, 2024 and September 9, 2024, the Company granted 245,653 RSUs vesting over four years and subject to service-only conditions. • Between September 10, 2024 and October 21, 2024, the Company granted 51,674 • Additionally, in October 2024, the Company granted each of Ara Mahdessian and Vahe Kuzoyan an award of 3,241,544 performance-based RSUs.
Rest of the question

Please revise your subsequent events disclosure beginning on page F-74 to disclose the expected financial impact of the awards (i.e. unrecognized compensation expense) pursuant to ASC 855-10-50-2(b). In addition, please tell us the grant date fair value of the shares of common stock used to determine the amount of compensation expense attributable to each of these grants. Please reconcile and explain the differences between the fair values of a share of common stock determined on each grant date including the difference between the most recent grant date fair value and the midpoint of your offering range.

TTAN answered
The Company respectfully acknowledges the Staff’s comment and has revised the disclosure on pages F-74 and F-75 of the Registration Statement to include subsequent events through November 18, 2024, and to disclose the grant date fair value of the RSUs granted during this period.

The Company advises the Staff that the grant date fair value for the RSUs with service-only vesting conditions granted between July 31, 2024 and November 18, 2024 was $59.29 per share.
Rest of the answer

The grant date fair value of these RSUs was equal to the fair value of the Company’s common stock on the respective grant dates.

The Company further advises the Staff that the grant date fair value of the performance-based RSUs granted to the Co-Founders was estimated using a Monte Carlo simulation model, which incorporates the likelihood of achieving the stock price hurdle performance conditions and also included as an input the common stock fair value of $59.29 per share.

The fair value of the common stock of $59.29 was determined by the Company’s Board of Directors based in part on the most recent third-party valuation of the common stock as of July 31, 2024, which was received on October 14, 2024, and the Board of Directors’ evaluation that there had been no changes in fair value from that date through the grant date of the respective awards.

The Company further advises the Staff that it will provide to the Staff a reconciliation of the common stock fair value used to value these awards to the midpoint of the offering range when the range is available, if such a reconciliation is deemed necessary.

Read in the reply
General
SEC asked (3)
Please provide balanced disclosure in the graphics in the forepart of the registration statement. Please also disclose the net loss for each period that you discuss revenue and revenue growth.
TTAN answered
The Company respectfully acknowledges the Staff’s comment and has revised the graphic in the forepart of the Registration Statement accordingly.

* * *

We hope the foregoing answer is responsive to your comment. Please do not hesitate to contact me by telephone at (650) 463-3060 or by email ([email protected]) with any questions or comments regarding this correspondence.
Read in the reply
Prospectus Summary · The Offering, page 16
SEC asked
We note your disclosure here and elsewhere in your prospectus regarding your directed share program for "eligible customers; friends and family members of [y]our Co-Founders; and certain other persons." Please expand your disclosure here, and elsewhere as appropriate, to address how you will determine eligible customers and other persons, the process that prospective participants will follow to participate in the
Rest of the question

program, the manner in which you will communicate with participants and determine the amount each will receive, when and how you will determine the allocation for the program, and whether such allocation will change depending on the interest level of potential participants, as well as any other material features of the program. Advise us of the number of potential purchasers who are eligible to receive communications 1. about the directed share materials.

TTAN answered
The Company respectfully acknowledges the Staff’s comment and has revised the disclosure on the cover page and pages 18, 187 and 216 of the Registration Statement to identify the individuals by title who are eligible participants in the directed share program. The Company advises the Staff that it has removed references to “and other persons” from the description of eligible participants.

The Company has revised the disclosure on pages 216 and 217 of the Registration Statement to describe the process that prospective participants will follow to participate in the program, the manner in which
Rest of the answer

the administrator will communicate with participants, and when and how the Company will determine the allocations for the program.

The Company advises the Staff that there are approximately 15,400 individuals eligible to receive communications as prospective participants of the directed share program.

* * *

We hope the foregoing answer is responsive to your comment. Please do not hesitate to contact me by telephone at (650) 463-3060 or by email ([email protected]) with any questions or comments regarding this correspondence.

Read in the reply

Also in this review: company letter, Dec 9, 2024, company letter, Dec 9, 2024

Form S-1

2024-03-27 to 2024-04-26 · 17 questions · 2 letters from the SEC, 0 from the company
No closing letter
RevenueResults discussion (MD&A)LeasesRisk factorsCritical estimatesSegmentsRussia and UkraineLegal and contingenciesLiquidity and cash
SEC letter of Mar 27, 2024 ↗ no reply letter on EDGAR (the company may have answered in an amended filing)
Risk Factors · Russian military action against Ukraine has adversely affected,..., page 49
SEC asked (1)
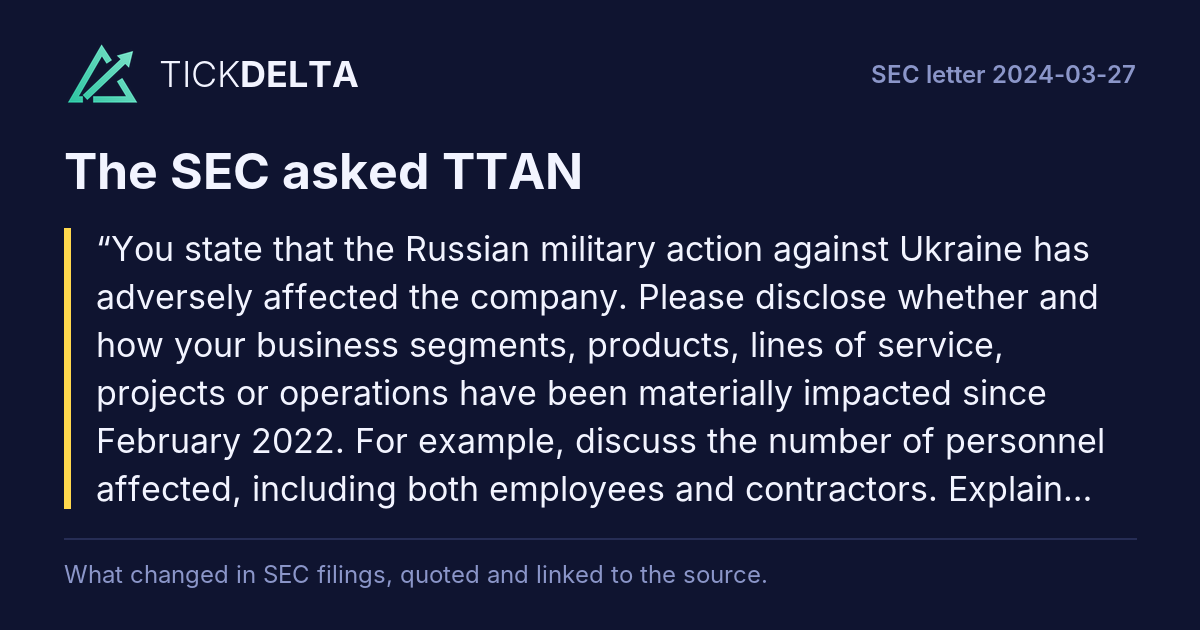
You state that the Russian military action against Ukraine has adversely affected the company. Please disclose whether and how your business segments, products, lines of service, projects or operations have been materially impacted since February 2022. For example, discuss the number of personnel affected, including both employees and contractors.
Rest of the question

Explain whether and how you have undertaken efforts to mitigate the impact and where possible quantify the impact to your business, if material.

TTAN answered

No reply letter found.

Management's Discussion and Analysis of Financial Condition and Results of Operations · Key Factors Affecting Our Business Performance, page 78
SEC asked (2)
Please revise to include the Gross Transaction Value and gross dollar retention rates for all periods presented. We note that you have provided disclosure for 2024 but did not include comparable disclosure for 2023.
TTAN answered

No reply letter found.

Management's Discussion and Analysis of Financial Condition and Results of Operations · Key Factors Affecting Our Business Performance, page 78
SEC asked (3)
Please tell us whether the “total number of customers” or “contracted annual recurring revenue” are key business metrics that management uses in managing or monitoring the performance of the company. We note that you intend to disclose the total number of customers since inception as of January 31, 2024.
Rest of the question

We also note that your annual bonuses for your executive officers are based on the certain performance goals relating to contracted annual recurring revenue. If these measures are key business metrics, please provide a quantitative discussion for all periods presented.

TTAN answered

No reply letter found.

Critical Accounting Policies and Estimates · Stock-Based Compensation, page 91
SEC asked (4)
Please provide us with a breakdown of all equity awards granted to date in fiscal 2024 and leading up to the initial public offering including the fair value of the underlying common stock used to value such awards as determined by your board of directors.
Rest of the question

To the extent there were any significant fluctuations in the fair values from period-to-period, please describe for us the factors that contributed to these fluctuations, including any intervening events within the Company or changes in your valuation assumptions or methodology. Business, page 93

TTAN answered

No reply letter found.

Critical Accounting Policies and Estimates · Stock-Based Compensation, page 91
SEC asked (5)
We note that your usage-based revenue consists primarily of fees from revenue sharing agreements with payment processing and end-customer financing partners. Please describe any material agreements with these third parties. File each material agreement as an exhibit to your registration statement or tell us why it is not required. Refer to Item 601(b)(10)(ii)(B) of Regulation S-K.
TTAN answered

No reply letter found.

The ServiceTitan Approach, page 98
SEC asked (6)
We note your statement on page 45 that you rely on open-source software. Please disclose whether the Titan Intelligence AI engine was developed by the company and clarify the extent to which you rely on existing open source licenses to support the product.
TTAN answered

No reply letter found.

The ServiceTitan Approach, page 98
SEC asked (7)
We note that you refer your “proprietary data assets” that the company intends to utilize in its AI engine. We also note your statement that your AI engine is “informed by external micro and macro data, such as local consumer behavior and credit card purchase data.” Please revise your disclosure to clarify whether you rely on historical data sets, and if so, include a risk factor highlighting any resulting risks.
TTAN answered

No reply letter found.

Principal Stockholders, page 146
SEC asked (8)
Please disclose the natural person or persons who exercise the voting and/or dispositive powers with respect to the securities owned by Battery Ventures, Bessemer Venture Partners, ICONIQ Capital, and TPG Tech Adjacencies II Sherpa, L.P.
TTAN answered

No reply letter found.

Lock-Up and Market Standoff Agreements, page 157
SEC asked (9)
We note that your lock-up agreements are subject to "certain other exceptions." Please disclose the exceptions.
TTAN answered

No reply letter found.

Cloud Computing Arrangements, page F-12
SEC asked (10)
Please clarify how your accounting for cloud computing arrangements complies with ASC 350-40-45-1 and 45-3. Please advise.
TTAN answered

No reply letter found.

Note 2 - Summary of Significant Accounting Policies · Leases, page F-12
SEC asked (11)
You disclose that your leases do not provide an implicit rate and you use an estimated incremental borrowing rate based on the information available at the lease commencement date in determining the present value of lease payments.
Rest of the question

Please revise your disclosure to clarify whether the rates implicit in your leases are not readily determinable and if that is the basis for using your incremental borrowing rate as the discount rate for your leases. Refer to “Rate Implicit in the Lease” defined in ASC 842-20-20.

TTAN answered

No reply letter found.

Revenue recognition · Subscription, page F-15
SEC asked (12)
We note your disclosure that "contracts provide for a minimum subscription fee for the contract term and in most cases, customers can expand their subscription on a monthly basis for a fee commensurate with the per unit fee defined in the contract." Please tell us how you considered whether this option qualifies as a material right. Refer to ASC 60610-55-41 to 55-45.
TTAN answered

No reply letter found.

Disaggregated Revenue and Revenue by Geography, page F-16
SEC asked (13)
Please tell us what consideration was given to disaggregating revenue by timing of transfer of goods or services (i.e. point in time, over time). Refer to ASC 606-10-55-90 and 55-91.
TTAN answered

No reply letter found.

Note 8 - Commitments and Contingencies · Indemnifications, page F-31
SEC asked (14)
We note your disclosure that "The maximum potential amount of future payments the Company could be required to make under these indemnification provisions is indeterminable." Please disclose, if true, that you did not have any material indemnification claims that were probable or reasonably possible and indemnity payments, if any, made by you have not had a material effect on your Consolidated Financial Statements.
Rest of the question

Refer to ASC 460-10-50.

TTAN answered

No reply letter found.

Note 9 - Leases, page F-31
SEC asked (15)
Please revise to disclose cash paid for amounts included in the measurement of lease liabilities included in operating cash flows. Refer to ASC 842-20-50-4(g)(1). General
TTAN answered

No reply letter found.

Note 9 - Leases, page F-31
SEC asked (16)
Please supplementally provide us with copies of all written communications, as defined in Rule 405 under the Securities Act, that you, or anyone authorized to do so on your behalf, present to potential investors in reliance on Section 5(d) of the Securities Act, whether or not they retain copies of the communications.
TTAN answered

No reply letter found.

SEC letter of Apr 26, 2024 ↗ no reply letter on EDGAR (the company may have answered in an amended filing)
Draft Registration Statement on Form S-1 submitted April 16, 2024 · Principal Stockholders, page 149
SEC asked
We note your response to prior comment 8 and reissue in part. Please revise your disclosure to identify the natural persons who exercise the voting and/or dispositive powers with respect to the securities owned by Battery Ventures, Bessemer Venture Partners, and ICONIQ Capital and clarify that no individual member exercises voting or dispositive control over the company's shares.
TTAN answered

No reply letter found.

From the SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), 9 letters filed since 2024-03-27. Questions and answers are matched by their numbers; topics come from words in each question. The reports are compared word for word (same form, before the first SEC letter against the first report after the company's reply). No AI.

Sources

The SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), matched question by question. No AI.

Also

Filings: the letters in the filing list.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/TTAN/export.csv") into a cell.

Next in Owners and insiders:Insider trades
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.