Form 10-K
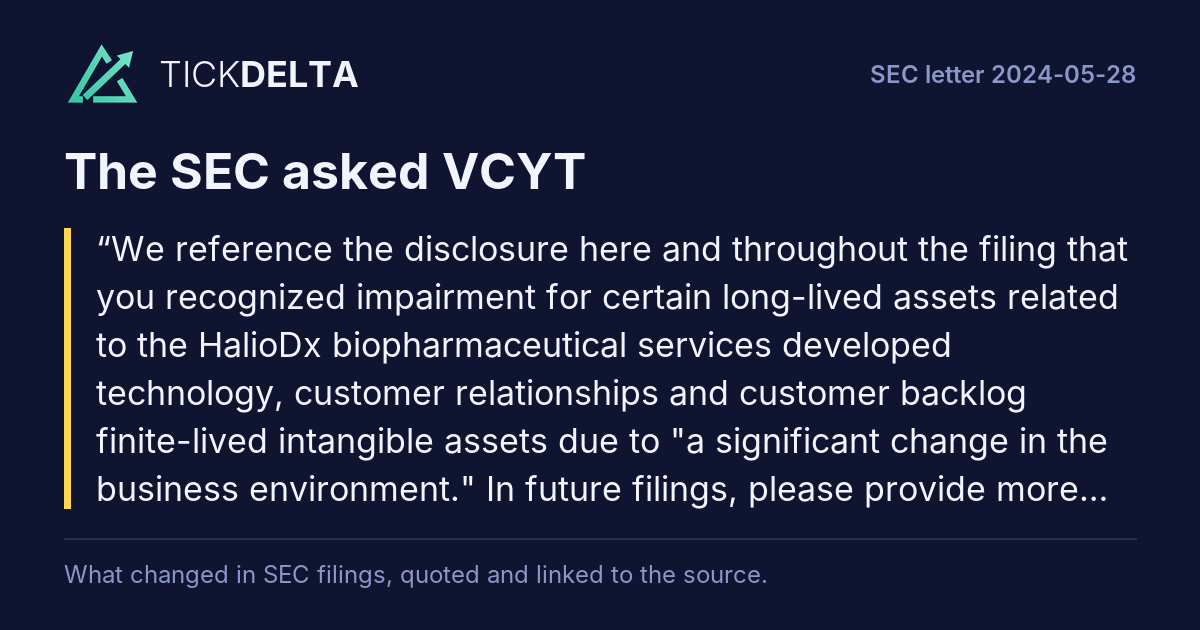
We reference the disclosure here and throughout the filing that you recognized impairment for certain long-lived assets related to the HalioDx biopharmaceutical services developed technology, customer relationships and customer backlog finite-lived intangible assets due to "a significant change in the business environment." In future filings, please provide more context regarding the nature and impact of anyRest of the question
triggering events that require assessment for impairment of your intangible assets.
The Company acknowledges the Staff’s comment and advises the Staff that it will provide further disclosure in future filings, where applicable, providing additional context regarding the nature and impact of any triggering events that require the Company to assess its intangible assets for impairment.Read in the replyRest of the answer
To that end, in response to the Staff’s comment, the Company shall update future disclosures describing the 2023 impairment of certain long-lived assets related to the HalioDx biopharmaceutical services developed technology, customer relationships and customer backlog finite-lived intangible assets to include additional context, as illustrated below:
U.S. Securities and Exchange Commission
“During 2023, the Company concluded that it had a triggering event requiring assessment of impairment for certain of its long-lived assets related to HalioDx biopharmaceutical services. This determination was due to spending constraints across the industry and loss of customers, which resulted in a significant decline in management’s current and future revenue and cashflow expectations for this product offering. As a result, the Company recorded a $32.0 million impairment charge associated with its HalioDx developed technology, customer relationships and customer backlog finite-lived intangible assets. The impairment is recorded within impairment of long-lived assets on the consolidated statement of operations.”
First report after the company's reply of Jun 7, 2024: 10-Q filed Aug 7, 2024 ↗, against the 10-Q filed May 8, 2024 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Your presentation of the reconciliation of U.S. GAAP to non-GAAP financial measures gives the appearance of a full non GAAP income statement. Please note that the presentation of a full non- GAAP income statement, or a presentation that gives the appearance of one, may place undue prominence on the non-GAAP information.Rest of the question
Under Question 102.10(c) of the C&DI's on Non-GAAP Financial Measures, a non-GAAP income statement is considered to be one that is comprised of non-GAAP measures and includes all or most of the line items and subtotals found in a GAAP income statement. Confirm to us that you will not present full non-GAAP consolidated income statements or their equivalents in future filings.
The Company acknowledges the Staff’s comment and advises the Staff that it will not present full non-GAAP consolidated income statements or their equivalents in its future filings.Read in the reply
First report after the company's reply of Jun 7, 2024: 10-Q filed Aug 7, 2024 ↗, against the 10-Q filed May 8, 2024 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
As a related matter, if you continue to present non-GAAP total operating costs excluding costs of revenue in future filings, please revise to reconcile to the most comparable GAAP measure, as required by Item 10(e)(1)(i) of Regulation S-K.
The Company acknowledges the Staff’s comment and, to the extent that it continues to present non-GAAP total operating costs excluding costs of revenue in future filings, it will reconcile such measure to the most comparable GAAP measure, as required by Item 10(e)(1)(i) of Regulation S-K.Read in the reply
First report after the company's reply of Jun 7, 2024: 10-Q filed Aug 7, 2024 ↗, against the 10-Q filed May 8, 2024 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
With reference to Note 1. to the Reconciliation of U.S. GAAP to Non-GAAP Financial Measures, please tell us the nature and composition of the non-GAAP adjustments for post-combination compensation expenses. Tell us how you determined it is appropriate to adjust for such payments in the determination of your non-GAAP measures and clarify how such compensation differs from other compensation paid to employees andRest of the question
management. Refer to Question 100.01 of the Commission's Compliance and Disclosure Interpretation for Non-GAAP measures.
The Company acknowledges the Staff’s comment and advises the Staff that all of the Company’s non-GAAP adjustments follow the Company’s non-GAAP policy. The nature of the non-GAAP adjustments for post-combination expenses referenced in Note 1. to the Reconciliation of U.S. GAAP to Non-GAAP Financial Measures is stock-based compensation expense related to certain restricted stock unit awards that were granted to the founders of HalioDx (the “Founder RSU Awards”) following the closing of the Company’s acquisition of HalioDx.Read in the replyRest of the answer
As a result, such compensation expense does not constitute a cash operating expense as contemplated in Question 100.01 of the Commission’s Compliance and Disclosure Interpretation for Non-GAAP measures. Moreover, consistent with the Company’s current policy, which provides for the adjustment of non-routine stock-based compensation, the Founder RSU Awards were comprised of non-routine, outsized retention awards outside of the Company’s standard equity award practices and bands, and were negotiated in connection with the transaction. Accordingly, the Company believes that its adjustment of such stock-based compensation relating to the Founder RSU Awards from its non-GAAP financial measures is appropriate. The Company further notes that the Founder RSU Awards have been expensed using the straight-line method over the duration of the vesting period. One founder left employment with the Company prior to the full vesting of the applicable Founder RSU Award, and so in the first quarter of 2024, the Company reversed the expense that had been recorded in prior periods for the unvested Founder RSU Awards that were forfeited, representing a $1.2 million adjustment.
*******
Should the Staff have additional questions or comments regarding the foregoing, please do not hesitate to contact the undersigned at (650) 335-7613, or, in his absence, Chelsea Anderson at (206) 389-4516.
First report after the company's reply of Jun 7, 2024: 10-Q filed Aug 7, 2024 ↗, against the 10-Q filed May 8, 2024 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: closing letter, 2024-06-13