Screener / SEC EDGAR /CIK 0001915657 /10-K filed Feb 27, 2026, compared with Feb 20, 2025 /Numbers from the XBRL of the 10-Ks
NYSE Industrials · Pipe Lines (No Natural Gas)

HF Sinclair Corp DINO

Compare with peers Embed
New in the 10-K 9 paragraphs with nothing like them in the 10-K filed Feb 20, 2025 New in the 10-Q 29 paragraphs not in the 10-Q filed Jul 30, 2026 10-Q against the 10-K 1 risk factor paragraphs and sentences added or reworded

New risk paragraphs, branching off last year

Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Feb 20, 2025. A box jumps to the paragraph as filed, below.

9 new

Paragraphs with nothing like them in last year's 10-K

Quoted exactly

9 paragraphs in Risk Factors of the 10-K filed Feb 27, 2026 with nothing like them in the 10-K filed Feb 20, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.

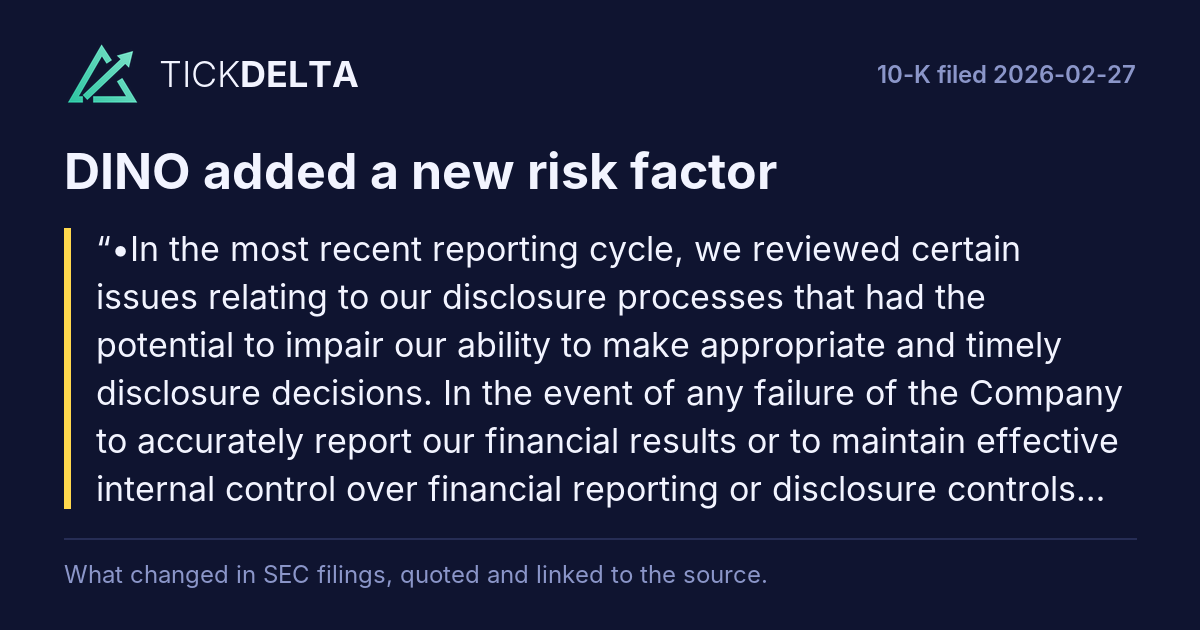
•In the most recent reporting cycle, we reviewed certain issues relating to our disclosure processes that had the potential to impair our ability to make appropriate and timely disclosure decisions. In the event of any failure of the Company to accurately report our financial results or to maintain effective internal control over financial reporting or disclosure controls and procedures, investors could lose confidence in our financial and other public reporting, which could have a material adverse effect.

Read in the 10-K

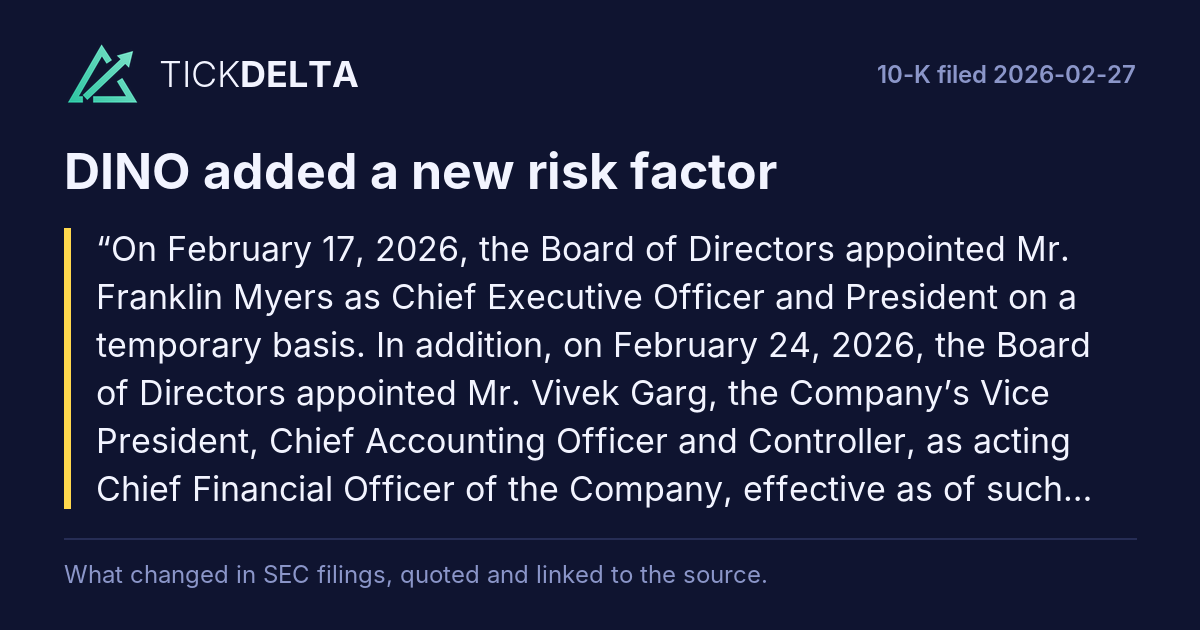
On February 17, 2026, the Board of Directors appointed Mr. Franklin Myers as Chief Executive Officer and President on a temporary basis. In addition, on February 24, 2026, the Board of Directors appointed Mr. Vivek Garg, the Company’s Vice President, Chief Accounting Officer and Controller, as acting Chief Financial Officer of the Company, effective as of such date. Both Mr. Myers and Mr. Garg have significant experience in their respective areas of responsibility but will face the challenges associated with any transition in senior executive management.

Read in the 10-K

In the most recent reporting cycle, we reviewed certain issues relating to our disclosure processes that had the potential to impair our ability to make appropriate and timely disclosure decisions. In the event of any failure of the Company to accurately report our financial results or to maintain effective internal control over financial reporting or disclosure controls and procedures, investors could lose confidence in our financial and other public reporting, which could have a material adverse effect.

Our internal control over financial reporting and disclosure controls and procedures may not prevent or detect misstatements because of its inherent limitations, including the possibility of human error, failure or interruption of information technology systems, the circumvention or overriding of controls, or fraud. Even effective internal control over financial reporting can provide only reasonable assurance with respect to the preparation and fair presentation of financial statements.

As described below under “HF Sinclair Management and Audit Committee Process” in Item 7, “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” of Part II of this Annual Report on Form 10-K, in the most recent reporting cycle, we reviewed certain issues relating to our disclosure processes that had the potential to impair our ability to make appropriate and timely disclosure decisions. Upon completion of their reviews, both the Company’s management and the Audit Committee, with the support of external legal counsel, determined that the concerns identified did not impair the Company’s ability to make appropriate and timely decisions regarding required disclosures. In addition, they have both determined that the Company’s internal control over financial reporting was effective.

If we fail to maintain the adequacy of our internal control over financial reporting or disclosure controls and procedures, including any failure to implement required new or improved controls, or if we experience difficulties in their implementation, our business and operating results could be harmed, we could fail to meet our financial reporting obligations, the material accuracy and timeliness of our public disclosures could be impaired, and we could suffer a material adverse effect. Among other things, any such failure could cause investors to lose confidence in the accuracy and completeness of our public disclosures, including our financial statements.

Read in the 10-K

Several environmental groups filed a petition under TSCA, in February 2025, requesting that the EPA promulgate a Section 6(a) rule to prohibit the use of HF in domestic oil refining, citing unreasonable risks to public health and the environment from refinery alkylation and associated transport of HF. Several of our refineries utilize HF in their alkylation process. In May 2025, the EPA denied the petition, concluding petitioners did not meet their burden under TSCA to establish that a Section 6(a) rule is necessary. Petitioners subsequently filed a lawsuit challenging EPA’s denial, and that litigation is pending and we cannot predict the outcome.

Read in the 10-K

Furthermore, the Province of Ontario implemented SO2 regulations which target industrial emissions from refineries aimed at reducing acid rain precursors and improving local air quality. The regulations impose emission limits and monitoring obligations on petroleum facilities, such as our Mississauga facility, requiring them to install Continuous Emission Monitoring Systems and report certain incidents.

Read in the 10-K
Show the other 1

Additionally, certain employment practices and social initiatives are the subject of scrutiny by both those calling for the continued advancement of such policies, as well as those who believe they should be curbed, including government actors, and the complex regulatory and legal frameworks applicable to such initiatives continue to evolve. We cannot be certain of the impact of such regulatory, legal and other developments on our business. More recent political developments could mean that we face increasing criticism or litigation risks from certain “anti-ESG” parties, including various governmental agencies. Such sentiment may focus on our Renewables segment, environmental commitments or our pursuit of certain employment practices or social initiatives that are alleged to be political or polarizing in nature or are alleged to violate laws based, in part, on changing priorities of, or interpretations by, federal agencies or state governments. Consideration of ESG-related factors in our decision making could be subject to increasing scrutiny and objection from such anti-ESG parties. As a result, we may face increased litigation risks from private parties and governmental authorities related to our efforts.

Read in the 10-K

Paragraphs in the 10-Q filed Oct 28, 2026 that were not in the one before

New in the latest 10-Q

29 paragraphs in the 10-Q filed Oct 28, 2026 with nothing like them in the 10-Q filed Jul 30, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.

10-Q

• the operation, financing and distribution decisions of our joint ventures that we do not control;

Read in the 10-Q

Financial statements and notes

Adjustments to reconcile net income to net cash provided by operating activities:

Read in the 10-Q

In August 2026, we entered into a joint venture with affiliates of Phillips 66 and Kinder Morgan to form the proposed Western Gateway Pipeline system (“Western Gateway”). We will own a 15.0 % interest in the joint venture while Phillips 66 and Kinder Morgan will own the remaining 49.9 % and 35.1 % interests, respectively. Western Gateway is a proposed 1,300-mile refined products pipeline system that would create a new fuel supply path from St. Louis, Missouri, to Arizona and California. We will account for our investment in Western Gateway under the equity method of accounting as a result of our board representation and approval rights over certain significant operating and financing decisions.

Read in the 10-Q

In July 2026, we announced plans to pursue a separation of our Lubricants & Specialties segment through the capital markets, creating a new independent, publicly traded company (the “Planned Separation”). The Planned Separation is expected to be executed in a tax-efficient manner. We expect the Planned Separation will be in the form of a distribution of at least 80.1 % of the Lubricants & Specialties company’s stock and will be substantially completed over the course of 2027. See Note 2 for additional information.

Read in the 10-Q

NOTE 2: Lubricants & Specialties Planned Separation and Mississauga Asset Retirement

Read in the 10-Q
Show the other 24

In July 2026, we announced the Planned Separation of our Lubricants & Specialties segment. Costs related to the Planned Separation for the three and nine months ended September 30, 2026 were $ 3 million.

Read in the 10-Q

In July 2026, we announced the Mississauga Asset Retirement. As a result of the decision, the following costs and charges were recorded in our Lubricants & Specialties segment:

Read in the 10-Q

Mississauga Asset Retirement Costs Statements of Operations Classification Three Months Ended September 30, Nine Months Ended September 30, 2026 2026 (In millions) ─────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────────── Incremental accelerated depreciation and amortization (1) (2) Depreciation and amortization $ 54 $ 54 Severance costs (3) Other operating expenses, net 28 28 Asset impairments (4) Other operating expenses, net 27 27 Total Mississauga Asset Retirement costs $ 109 $ 109

Read in the 10-Q

(1) We assessed the asset group that includes the Mississauga Refinery for impairment and concluded that the carrying value was recoverable. However, the useful lives of the Mississauga Refinery and associated turnaround costs were shortened to align with the estimated retirement date. As of September 30, 2026, the $ 336 million carrying value of the Properties, plants and equipment, net and Turnaround costs related to the Mississauga Refinery will be depreciated to its estimated salvage value. Incremental accelerated depreciation and amortization related to the Mississauga Refinery and associated turnaround costs are included in the Depreciation and amortization above.

Read in the 10-Q

(2) We increased our asset retirement obligations (“AROs”) by $ 140 million as of September 30, 2026, primarily reflecting a change in the estimated timing of expenditures and obligations to satisfy legal requirements associated with the Mississauga Asset Retirement. The AROs recorded require significant judgment and are subject to changes in the underlying assumptions. Depreciation of the related asset retirement costs will also be recorded through June 2027.

Read in the 10-Q

(3) Severance costs represent benefit payments payable to employees impacted by the Mississauga Asset Retirement.

Read in the 10-Q

(4) Asset impairment charges relate to the abandonment of certain assets under construction at the Mississauga Refinery.

Read in the 10-Q

(1) Includes $ 28 million of severance costs related to the Mississauga Asset Retirement. See Note 2 for additional information.

Read in the 10-Q

(2) Reflects a change in the estimated timing of expenditures and obligations to satisfy legal requirements associated with the Mississauga Asset Retirement. See Note 2 for additional information.

Read in the 10-Q

In connection with the August 2026 Stock Purchase Agreement, the Board increased the 2024 Share Repurchase Program by $ 15 million, effective July 31, 2026.

Read in the 10-Q

Separately, on April 7, 2026, the DC Circuit unanimously ruled in our favor regarding our Parco refinery’s 2024 SRE petition (the “Parco 2024 Petition”), vacating the EPA’s denial and remanding the matter to the EPA for reconsideration. The EPA issued a decision on August 3, 2026, partially granting relief on the Parco 2024 Petition. At the same time, the EPA denied a 2023 SRE petition for the Parco refinery and petitions for 2023 and 2024 for our Artesia refinery. We filed a petition for reconsideration of the EPA’s decision on the Parco 2024 Petition on August 7, 2026, asserting errors in the EPA’s analysis and requesting a full grant. On August 31, 2026, the EPA reaffirmed its partial grant for the Parco 2024 Petition. Additionally, on August 31, 2026, the EPA issued decisions partially granting or denying 2025 SRE petitions for our Woods Cross, Casper, Parco and Artesia refineries. The EPA also granted a 2025 SRE petition for our Tulsa East refinery. On October 1, 2026, certain of our subsidiaries filed lawsuits in the U.S. Court of Appeals for the Tenth Circuit challenging the EPA’s denials and partial grants for various SRE petitions for our Woods Cross, Parco and Artesia refineries for various compliance years from 2023 to 2025. On October 2, 2026, we filed protective lawsuits in the DC Circuit challenging the EPA’s denials and partial grants for the same SRE petitions.

Read in the 10-Q

The Renewable Fuels Association and Growth Energy also filed lawsuits in the DC Circuit challenging the EPA’s SRE grants and partial SRE grants in its various August 2026 decisions, including our refineries’ full grants and partial grants. On October 1, 2026, the DC Circuit granted those challengers’ motions to hold their lawsuits in abeyance pending the DC Circuit’s ruling on the challenges to the EPA’s August 2025 and November 2025 decisions. On October 19, 2026, we filed a motion to intervene to defend the full and partial SREs granted to our refineries in EPA’s August 2026 decisions.

Read in the 10-Q

In August 2026, we entered into a joint venture with affiliates of Phillips 66 and Kinder Morgan to form the proposed Western Gateway Pipeline system (“Western Gateway”). We will own a 15.0% interest in the joint venture while Phillips 66 and Kinder Morgan will own the remaining 49.9% and 35.1% interests, respectively. Western Gateway is a proposed 1,300-mile refined products pipeline system that would create a new fuel supply path from St. Louis, Missouri, to Arizona and California.

Read in the 10-Q

Depreciation and amortization increased $48 million, or 21% from $230 million for the three months ended September 30, 2025 to $278 million for the three months ended September 30, 2026, primarily due to $54 million of incremental accelerated depreciation and amortization in connection with the Mississauga Asset Retirement. See Note 2 “Lubricants & Specialties Planned Separation and Mississauga Asset Retirement” in the Consolidated Financial Statements for information regarding the Mississauga Asset Retirement.

Read in the 10-Q

Depreciation and amortization increased 8% from $681 million for the nine months ended September 30, 2025, to $735 million for the nine months ended September 30, 2026, primarily due to $54 million of incremental accelerated depreciation and amortization in connection with the Mississauga Asset Retirement. See Note 2 “Lubricants & Specialties Planned Separation and Mississauga Asset Retirement” in the Consolidated Financial Statements for information regarding the Mississauga Asset Retirement.

Read in the 10-Q

Costs associated with the Mississauga Asset Retirement are currently estimated at $140 million and will be funded with cash on hand and operating cash flows in 2027. See Note 2 “Lubricants & Specialties Planned Separation and Mississauga Asset Retirement” for additional information.

Read in the 10-Q

Share sales and buybacks

In connection with the August 2026 Stock Purchase Agreement, the Board increased the 2024 Share Repurchase Program by $15 million, effective July 31, 2026.

Read in the 10-Q

Financial statements and notes

(1) Western Gateway: In August 2026, we entered into a joint venture with affiliates of Phillips 66 and Kinder Morgan to form Western Gateway. We will own a 15.0% interest in the joint venture while Phillips 66 and Kinder Morgan will own the remaining 49.9% and 35.1% interests, respectively. Western Gateway is a proposed 1,300-mile refined products pipeline system that would create a new fuel supply path from St. Louis, Missouri, and expanded Gulf Coast origin points to Arizona and California. Our investment in Western Gateway will be funded with cash on hand and operating cash flows. We expect to invest up to $750 million, of which $20 million is expected in 2026, with the remaining investment expected primarily between 2027 and 2029. See Note 1 “Description of Business and Presentation of Financial Statements” for additional information regarding Western Gateway.

Read in the 10-Q

Westline Connect: The Company is continuing to progress the previously announced multi-phased western expansion project and expects to reach a Final Investment Decision (“FID”) in the first quarter of 2027. The first phase would increase the capacity to move product supply from our Rockies production into Utah and Nevada by 35,000 barrels per day and is targeted to be online by 2029. We expect the project to be funded with cash on hand and operating cash flows. We anticipate providing additional information on capital spend following the FID date.

Read in the 10-Q

Marketing: We plan to expand our Marketing footprint through continued investment in our non-operating joint ventures. We expect to fund this growth through cash on hand and operating cash flows.

Read in the 10-Q

During the three months ended September 30, 2026, we entered into two additional agreements in the normal course of business with fixed and determinable quantities, representing estimated commitments of $3.2 billion and $80 million that will be incurred over the next 20 and 10 years, respectively. The additional agreements commence in 2027 and actual amounts paid under the agreements may vary based on commodity prices, inflation adjustments and other contractual terms.

Read in the 10-Q

Legal proceedings

On October 1, 2026, certain of our subsidiaries filed lawsuits in the U.S. Court of Appeals for the Tenth Circuit challenging the EPA’s denials and partial grants for various SRE petitions for our Woods Cross, Parco and Artesia refineries for various compliance years from 2023 to 2025. On October 2, 2026, we filed protective lawsuits in the DC Circuit challenging the EPA’s denials and partial grants for the same SRE petitions.

Read in the 10-Q

Separately, the Renewable Fuels Association and Growth Energy filed lawsuits in the DC Circuit challenging the EPA’s SRE grants and partial SRE grants in its various August 2026 decisions, including our refineries’ grants and partial grants. On October 1, 2026, the DC Circuit granted those challengers’ motions to hold their lawsuits in abeyance pending the DC Circuit’s ruling on the challenges to the EPA’s August 2025 and November 2025 decisions. On October 19, 2026, we filed a motion to intervene to defend the full and partial SREs granted to our refineries in EPA’s August 2026 decisions.

Read in the 10-Q

Share sales and buybacks

In connection with the August 2026 Stock Purchase Agreement, the Board increased the 2024 Share Repurchase Program by $15 million, effective July 31, 2026.

Read in the 10-Q

The 10-Q's risk factors against the 10-K

Item 1A of the 10-Q filed Oct 28, 2026 against Item 1A of the 10-K filed Feb 27, 2026. A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed. Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed, Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal (cut words struck through, new words highlighted). Text on the page, not a score; each links to the filing at sec.gov.

Added10-Q Oct 28, 2026 vs 10-K Feb 27, 2026
There have been no material changes in our risk factors as previously disclosed in Part I, “Item 1A. Risk Factors” of our Annual Report on Form 10-K for the fiscal year ended December 31, 2025 (the “2025 Form 10-K”), except as supplemented in Part II, “Item 1A. Risk Factors” of our Quarterly Report on Form 10-Q for the quarterly period ended June 30, 2026. You should carefully consider the risk factors discussed in our 2025 Form 10-K and Form 10-Q for the quarterly period ended June 30, 2026, which could materially affect our business, financial condition or future results. Additional risks and uncertainties not currently known to us or that we currently deem to be immaterial also may materially adversely affect our business, financial condition or future results.

Read it in the 10-Q at sec.gov

Phrases used for the first time

Two-word phrases in Risk Factors of the 10-K filed Feb 27, 2026 that are in none of the 1 earlier 10-Ks stored, back to Feb 20, 2025

operational technology ×8make appropriate ×4disclosure controls ×4recent reporting ×3reporting cycle ×3issues relating ×3disclosure processes ×3timely disclosure ×3disclosure decisions ×3effective internal ×3lose confidence ×3increased litigation ×3audit committee ×3partial exemptions ×3feedstocks refined ×2accurately report ×2
Where each one is used
  • operational technology: •We may be subject to information and operational technology system failures, communications network disruptions and data breaches that are generally beyond our control.
  • make appropriate: •In the most recent reporting cycle, we reviewed certain issues relating to our disclosure processes that had the potential to impair our ability to make appropriate and timely disclosure decisions. In the event of any failure of the Company to accurately report our financial results or to maintain effective...
  • disclosure controls: •In the most recent reporting cycle, we reviewed certain issues relating to our disclosure processes that had the potential to impair our ability to make appropriate and timely disclosure decisions. In the event of any failure of the Company to accurately report our financial results or to maintain effective...
  • recent reporting: •In the most recent reporting cycle, we reviewed certain issues relating to our disclosure processes that had the potential to impair our ability to make appropriate and timely disclosure decisions. In the event of any failure of the Company to accurately report our financial results or to maintain effective...
  • reporting cycle: •In the most recent reporting cycle, we reviewed certain issues relating to our disclosure processes that had the potential to impair our ability to make appropriate and timely disclosure decisions. In the event of any failure of the Company to accurately report our financial results or to maintain effective...
  • issues relating: •In the most recent reporting cycle, we reviewed certain issues relating to our disclosure processes that had the potential to impair our ability to make appropriate and timely disclosure decisions. In the event of any failure of the Company to accurately report our financial results or to maintain effective...
  • disclosure processes: •In the most recent reporting cycle, we reviewed certain issues relating to our disclosure processes that had the potential to impair our ability to make appropriate and timely disclosure decisions. In the event of any failure of the Company to accurately report our financial results or to maintain effective...
  • timely disclosure: •In the most recent reporting cycle, we reviewed certain issues relating to our disclosure processes that had the potential to impair our ability to make appropriate and timely disclosure decisions. In the event of any failure of the Company to accurately report our financial results or to maintain effective...

The 10-K at sec.gov

Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.

What was taken out

2 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.

Across all companies
In 2021, the previous administration issued several executive orders that committed to substantial action on climate change, released “The Long-Term Strategy of the United States: Pathways to Net-Zero Greenhouse Gas Emissions by 2050”, which established a roadmap to net zero emissions in the United States by 2050 and called for, among other things, improving energy efficiency, decarbonizing energy sources, the increased use of zero-emission vehicles by the federal government, the elimination of subsidies provided to the fossil fuel industry, and increased emphasis on climate-related risks...
In the 10-K filed Feb 20, 2025
•REH Company became a significant holder of our common stock following the completion of the Sinclair Transactions.
In the 10-K filed Feb 20, 2025

Sources

Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.

Also

10-K change: what was reworded or cut, section by section.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/DINO/export.csv") into a cell.

Next:10-K change
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.