Added10-Q Oct 29, 2026 vs 10-K Feb 26, 2026
The following table provides information with respect to purchases we made of our common stock during the three months ended September 30, 2026:
Each branch is a paragraph in Risk Factors with nothing like it in the 10-K filed Feb 20, 2025. A box jumps to the paragraph as filed, below.
5 paragraphs in Risk Factors of the 10-K filed Feb 26, 2026 with nothing like them in the 10-K filed Feb 20, 2025. Quoted exactly. Paragraphs that were only edited are under 10-K change.
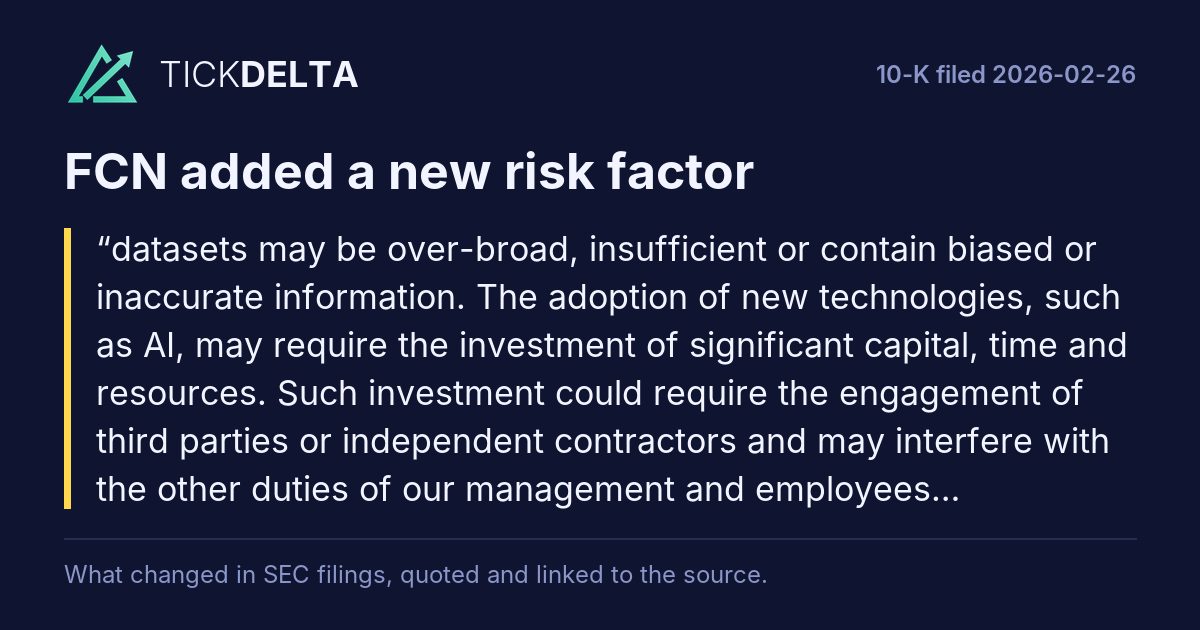
datasets may be over-broad, insufficient or contain biased or inaccurate information. The adoption of new technologies, such as AI, may require the investment of significant capital, time and resources. Such investment could require the engagement of third parties or independent contractors and may interfere with the other duties of our management and employees. Leveraging AI capabilities for our internal functions and operations presents additional risks, costs and challenges, including those discussed in these risk factors. The development, adoption and use of AI technologies are still in the early stages and involve significant risks and uncertainties, which may expose us to legal, reputational and financial harm. In addition, AI and other technologies that are open source and available for no or low cost could result in low barriers to development and utilization, and additional competition from third parties, and the adoption and deployment of AI and other new and emerging technologies by competitors more rapidly or successfully than we do could materially adversely affect our competitive position and financial results.
harm and the loss of clients and other adverse business consequences, which could negatively impact our financial results or financial condition.
and other professionals on a case-by-case basis. The aggregate amount of loans to professionals is significant. We expect to continue issuing unsecured general recourse forgivable loans.
In connection with our acquisitions, we generally obtain non-solicitation agreements from the professionals we hire, as well as non-competition agreements from senior managers and professionals. The agreements prohibit such individuals from
successful and may not permit us to meet our scheduled debt service obligations. In addition, the terms of existing or future debt agreements, including our Credit Facility, may restrict us from pursuing any of these alternatives.
New in the latest 10-Q
19 paragraphs in the 10-Q filed Oct 29, 2026 with nothing like them in the 10-Q filed Jul 30, 2026 (at least half the words must differ; new numbers alone do not count). Quoted exactly, grouped by the item heading above them. This is text that changed, not a judgement of how serious it is.
During the three months ended September 30, 2026, we recorded special charges of $ 46.0 million as part of a plan to align staffing with demand, which consisted of $ 45.5 million in salary- and benefits-related costs associated with targeted headcount reductions and $ 0.5 million in non-cash real estate-related costs. A portion of the special charges liabilities was paid during the three months ended September 30, 2026 and the remaining amounts are expected to be paid in cash in the next 12 months. Liabilities related to the special charges were $ 38.4 million as of September 30, 2026. These amounts are included in “Accounts payable, accrued expenses and other” on our Condensed Consolidated Balance Sheets.
Read in the 10-Q
September 30, 2026 December 31, 2025 Gross Accumulated Net Gross Accumulated Net
Read in the 10-Q
During the fourth quarter of 2026, we continued our plan to align staffing with demand. We expect to record a special charge of approximately $ 7 million in the fourth quarter of 2026, consisting of approximately $ 2 million in salary- and benefits-related costs associated with targeted headcount reductions and approximately $ 5 million in real estate-related costs.
Read in the 10-Q
During the three months ended September 30, 2026, we recorded special charges of $46.0 million as part of a plan to align staffing with demand, which consisted of $45.5 million in salary- and benefits-related costs associated with targeted headcount reductions and $0.5 million in non-cash real estate-related costs. A portion of the special charges liabilities was paid during the three months ended September 30, 2026 and the remaining amounts are expected to be paid in cash in the next 12 months.
Read in the 10-Q
During the fourth quarter of 2026, we continued our plan to align staffing with demand. We expect to record a special charge of approximately $7 million in the fourth quarter of 2026, consisting of approximately $2 million in salary- and benefits-related costs associated with targeted headcount reductions and approximately $5 million in real estate-related costs.
Read in the 10-Q
Three Months Ended September 30, 2026 Compared to Three Months Ended September 30, 2025
Read in the 10-Q
Nine Months Ended September 30, 2026 Compared to Nine Months Ended September 30, 2025
Read in the 10-Q
Three Months Ended September 30, 2026 Compared to Three Months Ended September 30, 2025
Read in the 10-Q
Nine Months Ended September 30, 2026 Compared to Nine Months Ended September 30, 2025
Read in the 10-Q
Three Months Ended September 30, 2026 Compared to Three Months Ended September 30, 2025
Read in the 10-Q
Nine Months Ended September 30, 2026 Compared to Nine Months Ended September 30, 2025
Read in the 10-Q
Three Months Ended September 30, 2026 Compared to Three Months Ended September 30, 2025
Read in the 10-Q
Nine Months Ended September 30, 2026 Compared to Nine Months Ended September 30, 2025
Read in the 10-Q
Three Months Ended September 30, 2026 Compared to Three Months Ended September 30, 2025
Read in the 10-Q
Nine Months Ended September 30, 2026 Compared to Nine Months Ended September 30, 2025
Read in the 10-Q
Three Months Ended September 30, 2026 Compared to Three Months Ended September 30, 2025
Read in the 10-Q
Nine Months Ended September 30, 2026 Compared to Nine Months Ended September 30, 2025
Read in the 10-Q
Nine Months Ended September 30, 2026 Compared to Nine Months Ended September 30, 2025
Read in the 10-Q
including our Chief Executive Officer and Chief Financial Officer, as appropriate, to allow timely decisions regarding required disclosure.
Read in the 10-Q
Item 1A of the 10-Q filed Oct 29, 2026 against Item 1A of the 10-K filed Feb 26, 2026.
A 10-Q repeats only the risks that changed, so a 10-K paragraph that is missing from it is not counted as removed.
Added is a paragraph with nothing like it in the 10-K, Reworded a sentence that is in both with several words changed,
Quiet changes a sentence in both where one to four words changed and one is a hedge or a modal
(cut words struck through, new words highlighted).
Text on the page, not a score; each links to the filing at sec.gov.
What the 10-Q itself says about its risk factors:There have been no material changes in any risk factors previously disclosed in Part I, Item 1A, of our Annual Report on Form 10-K for the year ended December 31, 2025 filed with the SEC. We may disclose changes to risk factors or disclose additional factors from time to time in our future filings with the SEC. Additional risks and uncertainties not presently known to us or that we currently deem immaterial also may impair our business operations.
Read in the 10-Q
Two-word phrases in Risk Factors of the 10-K filed Feb 26, 2026 that are in none of the 1 earlier 10-Ks stored, back to Feb 20, 2025
Used at least twice, small words left out. Counted, not picked: a phrase can be new because the company renamed something.
2 paragraphs of last year's Risk Factors with nothing like them now. The longest are quoted.
Item 1A of each 10-K and 10-Q on EDGAR, quoted exactly. Each paragraph links to the filing at sec.gov.
10-K change: what was reworded or cut, section by section.
Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/FCN/export.csv") into a cell.