Screener / SEC EDGAR /CIK 0001544522 /10-K filed Feb 26, 2026, compared with Feb 20, 2025 /Numbers from the XBRL of the 10-Ks
Nasdaq Technology · Software

Freshworks Inc. FRSH

Compare with peers Embed
SEC comment letters, last 20 years

2 reviews of FRSH's filings by SEC staff

UPLOAD and CORRESP
Reviews 2 latest letter Nov 17, 2022
Questions asked 43 each answered in the company's own letter
No closing letter 1 reviews without a letter saying the staff completed it

When the SEC's staff reviews a filing, it writes to the company with numbered questions, and the company answers each one in a letter. SEC publishes the exchange once the review is over, at least 20 business days later. A question is not an accusation; most reviews end with the company adding detail to its next filing.

How the reviews went

Every review on EDGAR, from the first staff letter to the letter that closes it

  1. 1. Staff letters 6 UPLOAD
  2. 2. Questions in them 43 numbered comments
  3. 3. Company replies 4 CORRESP
  4. 4. Reviews closed 1 of 2 closing letter

Half the closed reviews took 29 days or less from the first letter to the closing letter.

Form 10-K for the Fiscal Year Ended December 31, 2021

2022-11-17 to 2022-12-16 · 6 questions · 2 letters from the SEC, 2 from the company
Review closed 2022-12-16
Results discussion (MD&A)RevenueSegments
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations · Key Business Metrics, page 50
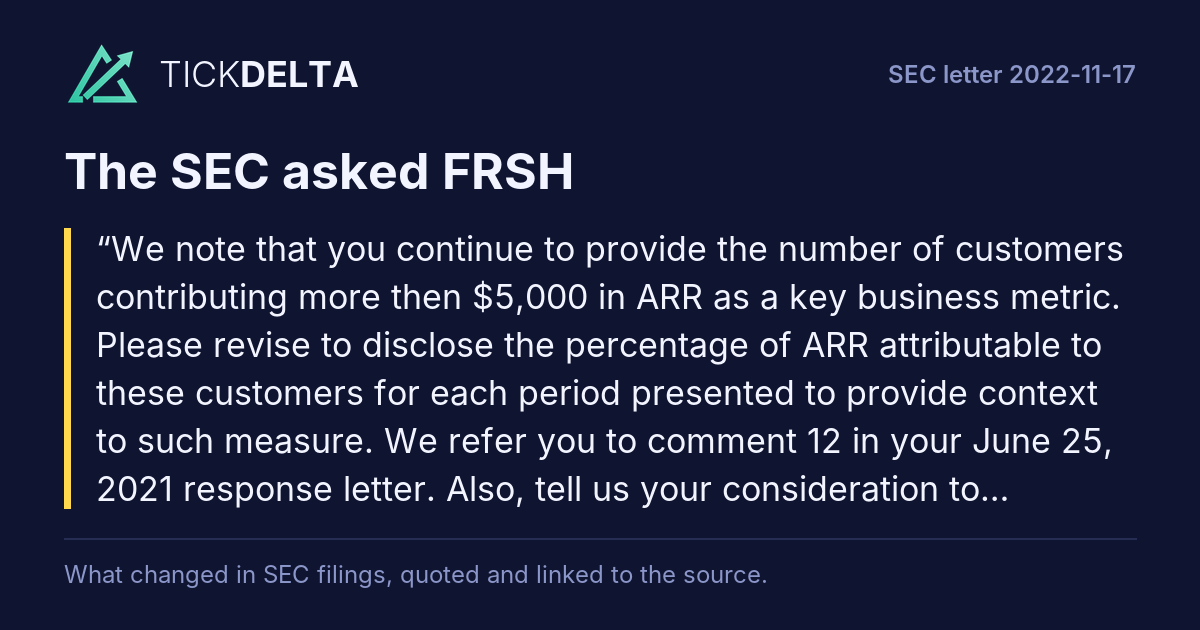
SEC asked (1)
We note that you continue to provide the number of customers contributing more then $5,000 in ARR as a key business metric. Please revise to disclose the percentage of ARR attributable to these customers for each period presented to provide context to such measure. We refer you to comment 12 in your June 25, 2021 response letter.
Rest of the question

Also, tell us your consideration to include the number of such customers and the percentage growth in ARR related to such customers for each period for which a statement of operations is presented.

FRSH answered
The Company acknowledges the Staff's comment and supplementally advises the Staff that as of December 31, 2021, 2020 and 2019, ARR from customers contributing more than $5,000 represented 85%, 82% and 78% of total ARR, respectively. In response to the Staff’s comment, we will include this disclosure in future filings.

The Company further supplementally advises the Staff that it believes the responses provided in Comment 11 in our June 25, 2021 response letter are still applicable.
Rest of the answer

The Company further confirms that the ARR from customers contributing more than $5,000 is representative of the size of customer that the Company targets. Customers of a smaller size do not meaningfully contribute to the Company’s financial success. The Company considers the number of customers contributing more than $5,000 in ARR and its net dollar retention rate to be the best indicators of trends in the Company’s business as they provide meaningful insights with respect to the Company’s operating performance and, specifically, its ability to successfully execute its strategy. This business model depends on the Company’s ability to capture new customers of a meaningful size and increase the value that it provides to such customers over a period of time in order to drive future financial results.

Read in the reply
In its next report

First report after the company's reply of Dec 2, 2022: 10-K filed Feb 23, 2023 ↗, against the 10-K filed Feb 23, 2022 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations · Key Business Metrics, page 50
SEC asked (2)
Please tell us whether you continue to include monthly subscriptions in your calculation of net dollar retention rate. If so, revise to include a discussion of how monthly subscriptions factor into such calculations and how ARR and net dollar retention rates may be impacted if such contracts are not renewed. Lastly, disclose the percentage of ARR from monthly subscriptions for each period presented.
Rest of the question

We refer to you to comment 7 in your July 19, 2021 response letter.

FRSH answered
The Company respectfully advises the Staff that the Company continues to include monthly subscriptions in the calculation of ARR, and consequently net dollar retention rate, which is calculated based on ARR. On page 49 of the Form 10-K, we discussed how the Company calculates ARR, and the impact and limitations of monthly subscriptions:

“We define annual recurring revenue (ARR) as the sum total of the subscription revenue we would contractually expect to recognize over the next 12 months from all customers at a point in time, assuming no increases, reductions, or cancellations in their
Rest of the answer

subscriptions. For monthly subscriptions, we take the recurring revenue run-rate of such subscriptions for the last month of the period and multiply it by 12 to get to ARR. While monthly subscribers as a group have historically maintained or increased their subscriptions over time, there is no guarantee that any particular customer on a monthly subscription will renew its subscription in any given month, and therefore the calculation of ARR for these monthly subscriptions may not accurately reflect revenue to be received over a 12-month period from such customers. As of December 31, 2021 and 2020, 14,814 and 11,570 of our customers contributed more than $5,000 in ARR, respectively, demonstrating the broad appeal of our products to customers of all sizes and geographies. We believe that the number of customers that contribute more than $5,000 in ARR is an indicator of our success in expanding upmarket to larger businesses.”

The Company also supplementally advises the Staff that the net dollar retention rate may reflect a higher rate than the actual rate if customers on monthly subscriptions choose not to renew during the course of the applicable 12-month period. Monthly subscriptions represented 24%, 28%, and 32% of ARR as of December 31, 2021, 2020 and 2019, respectively. In response to the Staff’s comment, in future filings, we will include a discussion of how monthly subscriptions impact the Company’s net dollar retention rate and its limitations, and the percentage of ARR from monthly subscriptions.

Read in the reply
In its next report

First report after the company's reply of Dec 2, 2022: 10-K filed Feb 23, 2023 ↗, against the 10-K filed Feb 23, 2022 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Results of Operations, page 54
SEC asked (3)
You attribute the increase in revenue for fiscal 2021 compared to 2020 to increases in additional agents enabled by your customers, sales to existing customers and the addition of new customers. Where a material changes from period-to-period is due to two or more factors, including any offsetting factors, revise to describe the underlying reasons for these material changes in both quantitative and qualitative terms.
Rest of the question

Refer to Item 303(b) of Regulation S-K.

FRSH answered
The Company acknowledges the Staff’s comment and supplementally advises the Staff that revenue increased by $121.4 million or 49% for the year ended December 31, 2021 compared to the same period in 2020, which was primarily driven by expansion within our existing customers, as reflected by the increase in our net dollar retention rate from 111% to 114% between December 31, 2020 and December 31, 2021.
Rest of the answer

While to a lesser extent than expansion, increase in revenue from new customers acquired during the year also contributed to the revenue increase year over year, as reflected by the increase in the Company's number of paying customers as of December 31, 2020 and 2021 from more than 48,500 to more than 56,000. The Company will include similar disclosure in its future filings.

Read in the reply
In its next report

First report after the company's reply of Dec 2, 2022: 10-K filed Feb 23, 2023 ↗, against the 10-K filed Feb 23, 2022 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Item 8. Financial Statements and Supplementary Data · Note 14. Geographic Information, page 96
SEC asked (4)
We note that you generate a significant amount of revenue from international operations. Please tell us whether North America is comprised of only the United States. If not, revise to disclose revenue from your country of domicile separately from all other countries.
Rest of the question

Also, tell us whether revenue from any individual country is material and if so, how you considered the guidance in ASC 280-10-50-41(a) to disclose such revenue. We remind you that the company and its management are responsible for the accuracy and adequacy of their disclosures, notwithstanding any review, comments, action or absence of action by the staff.

FRSH answered
The Company supplementally advises the Staff that revenue from North America primarily includes revenue from the United States, the Company's country of domicile. For the years ended December 31, 2021, 2020 and 2019, revenue generated from the United States was $142.9 million, $99.2 million and $72.8 million, or 39%, 40% and 42% of total revenue, respectively.
Rest of the answer

The United States represents the significant majority of the North America concentration in the geographic disclosure within Note 14 of the financial statements.

The next country with the largest concentration of the Company's revenue was the United Kingdom, which is categorized within Europe, Middle East, and Africa in Note 14 of the financial statements. The United Kingdom contributed $52.9 million, $33.2 million and $22.8 million, or 14%, 13% and 13% of total consolidated revenue for the years ended December 31, 2021, 2020 and 2019, respectively. No other country accounted for 10% or more of total consolidated revenue during the years ended December 31, 2021, 2020 and 2019.

In future filings and in response to the Staff’s comment, the Company will separately disclose revenue generated from the United States, which is our country of domicile, and foreign countries with revenues of 10% or more of total consolidated revenue.

* * * * *

Please advise us if we can provide any further information or assistance to facilitate your review. Please direct any questions or further comments regarding this response letter to the undersigned at [email protected], with a copy to Pam Sergeeff, our Chief Legal Officer, at [email protected].

Read in the reply
In its next report

First report after the company's reply of Dec 2, 2022: 10-K filed Feb 23, 2023 ↗, against the 10-K filed Feb 23, 2022 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations · Key Business Metrics, page 50
SEC asked (1)
We note from your response to prior comment 1 that you consider the number of customers contributing more than $5,000 in ARR and net dollar retention rate to be the best indicators of trends in your business. Therefore, tell us your consideration to disclose these metrics for each period in which financial statements are provided (e.g. fiscal 2019). Results of Operations, page 54
FRSH answered
The Company supplementally advises the Staff that, as disclosed in our final prospectus filed on September 22, 2021 pursuant to Rule 424(b)(4), there were 8,588 customers contributing more than $5,000 in ARR as of December 31, 2019 and net dollar retention rate was 115% for the year ended December 31, 2019. In response to the Staff's comment, in future filings, we will include the key business metrics for each period in which financial statements are provided.
Read in the reply
In its next report

First report after the company's reply of Dec 15, 2022: 10-K filed Feb 23, 2023 ↗, against the 10-K filed Feb 23, 2022 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations · Key Business Metrics, page 50
SEC asked (2)
We note your response to prior comment 3 where you state that you will disclose the net dollar retention rate and number of paying customers in future filings to explain the increase in revenue from new versus existing customers.
Rest of the question

Please also disclose the percentage or dollar amount of change in revenue attributable to both new and existing customers to add further context to the impact of such metrics on your revenue growth.

FRSH answered
In response to the Staff’s comment, in future filings, the Company will also include the percentage or dollar amount of change in revenue attributable to both new and existing customers.

* * * * *

Please advise us if we can provide any further information or assistance to facilitate your review. Please direct any questions or further comments regarding this response letter to the undersigned at [email protected], with a copy to Pam Sergeeff, our Chief Legal Officer, at [email protected].
Read in the reply
In its next report

First report after the company's reply of Dec 15, 2022: 10-K filed Feb 23, 2023 ↗, against the 10-K filed Feb 23, 2022 ↗.

Tickdelta does not hold the text of both reports, so they are not compared here.

Also in this review: closing letter, 2022-12-16
Form S-1

2021-06-10 to 2021-09-17 · 37 questions · 4 letters from the SEC, 2 from the company
No closing letter
Risk factorsRevenueResults discussion (MD&A)Liquidity and cashLegal and contingenciesNon-GAAP measures
SEC letter of Jun 10, 2021 ↗ no reply letter on EDGAR (the company may have answered in an amended filing)
Draft Registration Statement Submitted on Form S-1 · The Offering, page 9
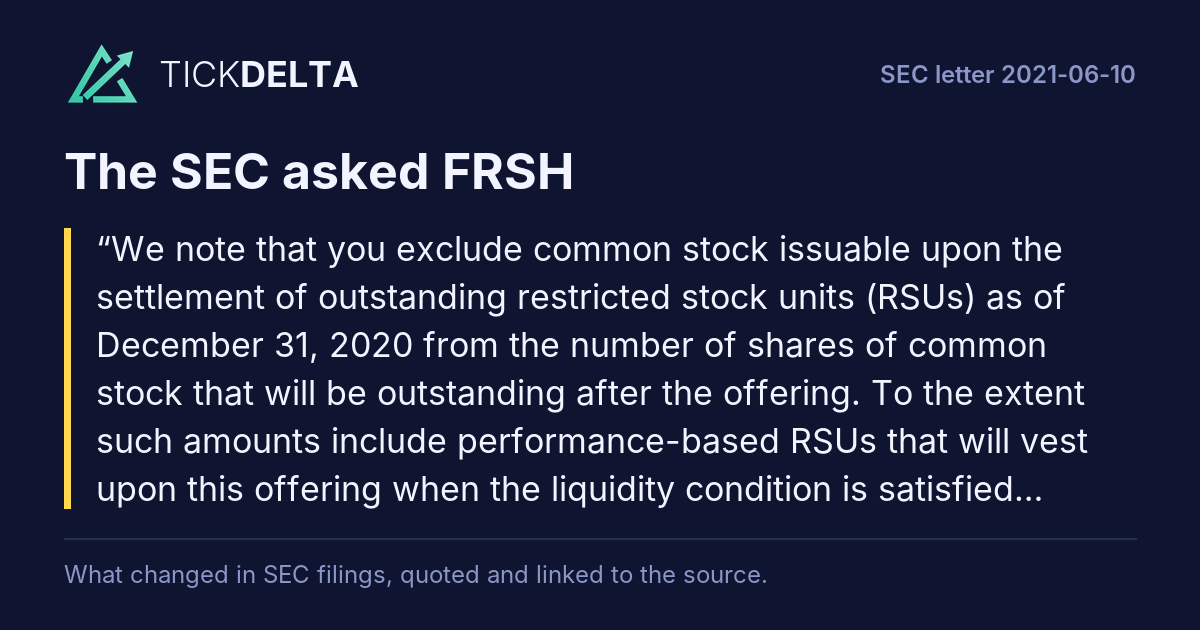
SEC asked (1)
We note that you exclude common stock issuable upon the settlement of outstanding restricted stock units (RSUs) as of December 31, 2020 from the number of shares of common stock that will be outstanding after the offering.
Rest of the question

To the extent such amounts include performance-based RSUs that will vest upon this offering when the liquidity condition is satisfied, please revise to include such shares in your disclosure of common shares outstanding.

FRSH answered

No reply letter found.

Summary Consolidated Financial Data, page 11
SEC asked (2)
Please include a pro forma earnings per share measure to reflect the automatic conversion of preferred stock to common stock upon the closing of this offering. Also, to the extent that your RSUs have met the time based vesting provisions and are only subject to a liquidity condition that will be satisfied by your offering, please revise to include such shares, as well as the impact of recognizing any related
Rest of the question

stock-based compensation expense. Please also revise your pro forma capitalization and dilution disclosures accordingly. Refer to Article 11-01(a)(8) of Regulation S-X.

FRSH answered

No reply letter found.

Risk Factors · We track certain key business metrics..., page 15
SEC asked (3)
Please provide examples of the limitations of your internal tools and methodologies for tracking your metrics.
FRSH answered

No reply letter found.

If we fail to manage our technical operations infrastructure..., page 22
SEC asked (4)
We note your disclosure of the importance of Amazon Web Services to your business. Please disclose the material terms of your agreement with Amazon Web Services, including the term and any termination provisions.
FRSH answered

No reply letter found.

Sales efforts to large customers..., page 26
SEC asked (5)
Please disclose the average length of your sales cycle to large customers as compared to smaller customers.
FRSH answered

No reply letter found.

We derive, and expect to continue to derive..., page 26
SEC asked (6)
Please disclose the percentage of your revenue generated from the four products listed in this risk factor for the periods presented.
FRSH answered

No reply letter found.

Risks Related to Ownership of Our Common Stock, page 41
SEC asked (7)
Please add a risk factor that addresses the concentration of ownership among your directors, officers and principal stockholders.
FRSH answered

No reply letter found.

Key Factors Affecting Our Performance, page 64
SEC asked (8)
You disclose that you have over 48,000 total customers as of December 31, 2020. However, you also disclose a total customer base of over 50,000 organizations elsewhere throughout the filing. Please revise to address this apparent inconsistency.
Rest of the question

Disclose the actual number of customers for each period presented and clarify whether such amounts include customers currently in the free forever tier of Freshsales or in a free trial period as customers. With regards to your disclosure of customers for each of your three main products, clarify whether you include a customer using more than one product as a customer for each product. Also, please revise to disclose the actual number of customers per product for each period presented and if applicable, quantify the number of customers in each count that are included as customers for more than one product.

FRSH answered

No reply letter found.

Key Factors Affecting Our Performance, page 64
SEC asked (9)
Please explain whether, and if so how, cancellations are factored into your annual recurring revenue (ARR) calculations for the purposes of your cohort chart presentation. For example, tell us whether the 2012-2019 cohort groups exclude customers that cancelled their subscriptions and if so, explain further how this measure represents your ability to retain and expand your customer relationships.
FRSH answered

No reply letter found.

Key Factors Affecting Our Performance, page 64
SEC asked (10)
You disclose that you define ARR as the sum total of the subscription revenue you would contractually expect to recognize over the next 12 months from all customers at a point in time, assuming no increases or reductions in their subscriptions. Please tell us whether your ARR calculations include the annualized value of monthly contracts, and if so, explain your basis for annualizing revenue from such customers.
Rest of the question

In your response, please provide us with cancellation/attrition rates or, alternatively, renewal rates for your monthly subscribers as well as the percentage of revenue generated from monthly contracts for each period presented. Also, revise your disclosures related to the ARR calculations to address the inclusion of monthly subscriptions, to the extent material. Key Business Metrics, page 66

FRSH answered

No reply letter found.

Key Factors Affecting Our Performance, page 64
SEC asked (11)
We note that you present an ARR by cohort graph, the number of customers with ARR greater than $5,000 and a dollar net retention rate that compares ARR from customers in one period to ARR in a prior period. Elsewhere you disclose the number of customers with ARR greater than $50,000.
Rest of the question

Please tell us whether management uses the ARR metric itself to manage the business and if so, tell us what consideration you have given to including a quantified discussion of this metric for each period presented. Refer to SEC Release No. 33-10751.

FRSH answered

No reply letter found.

Key Factors Affecting Our Performance, page 64
SEC asked (12)
To provide context to your metric, please revise to disclose the percentage or amount of revenue attributable to customers with ARR greater than $5,000 for each period presented. Discuss any limitations present, such as the number of customers with monthly contracts that may not have annual contractual revenue associated with them. Business
FRSH answered

No reply letter found.

Our Business Model, page 86
SEC asked (13)
Please disclose the number of small-and mid-sized business, mid-market and enterprise customers for the periods presented.
FRSH answered

No reply letter found.

Consolidated Financial Statements · Note 12. Common Stock and Stock Based Compensation, page F-28
SEC asked (14)
Please revise to separately disclose the number of performance-based RSUs and related unrecognized compensation expense that will vest upon this offering. Refer to ASC 71810-50-2(g).
FRSH answered

No reply letter found.

Note 16. Subsequent Events, page F-35
SEC asked (15)
Please provide a breakdown of the 326,740 RSUs granted through May 14, 2021, as well as for any other issuances through the date of your response, and include the fair value of the underlying ordinary shares used to value such grants.
Rest of the question

If there were any significant fluctuations in the fair values between grant dates, describe for us the factors that contributed to these fluctuations, including any intervening events within the company or changes in your valuation assumptions or methodologies.

FRSH answered

No reply letter found.

Note 16. Subsequent Events, page F-35
SEC asked (16)
Please disclose the estimated unrecognized compensation expense associated with your equity awards issued subsequent to December 31, 2020, if material, and the periods over which it will be recognized. Also, clarify whether these are time-based or performancebased awards. Refer to ASC 855-10-50-2(b).
FRSH answered

No reply letter found.

General
SEC asked (17)
Please provide a detailed legal analysis analyzing whether the registrant meets the definition of “investment company” under the Investment Company Act of 1940. Please include relevant unconsolidated financial information to support your determination.
Rest of the question

Among other things, your analysis should indicate the value of your investment securities and total assets, exclusive of cash items and Government securities, on an unconsolidated basis. If the registrant is an investment company, provide a complete and detailed explanation of the basis for reliance upon any exemption or exclusion from the definition of investment company under the Investment Company Act of 1940.

FRSH answered

No reply letter found.

General
SEC asked (18)
Please supplementally provide us with copies of all written communications, as defined in Rule 405 under the Securities Act, that you, or anyone authorized to do so on your behalf, present to potential investors in reliance on Section 5(d) of the Securities Act, whether or not they retain copies of the communications.
FRSH answered

No reply letter found.

SEC letter of Jul 12, 2021 ↗ no reply letter on EDGAR (the company may have answered in an amended filing)
Prospectus Summary · Overview, page 1
SEC asked (1)
We note from your response to prior comment 12, that 12,332 customers who each contributed more than $5,000 in ARR for the first quarter of fiscal 2021 represented approximately 83% of your total ARR. You also state in response to comment 11 that customers of a smaller size do not meaningfully contribute to your financial success.
Rest of the question

To add context to the 50,000 customers that you disclose throughout the filing, please revise your prospectus summary to also disclose the number of customers with over $5,000 in ARR along with their contribution to total ARR for each period presented.

FRSH answered

No reply letter found.

Summary Consolidated Financial Data, page 11
SEC asked (2)
We note your pro forma earnings per share measure added in response to prior comment 2. Please revise to also include the number of RSU shares that will vest as a result of your offering, as well as the related compensation expense, as previously requested. Risk Factors, page 15
FRSH answered

No reply letter found.

Summary Consolidated Financial Data, page 11
SEC asked (3)
Please include a risk factor relating to the requirements of the Investment Company Act of 1940, including a discussion regarding the possibility that you could be required to register under the Act and the possible risks to shareholders if you were deemed an investment company.
FRSH answered

No reply letter found.

Management's Discussion and Analysis of Financial Condition and Results of Operations · Key Factors Affecting Our Performance, page 64
SEC asked (4)
We note your response to prior comment 8. Please revise this section to provide the actual number of customers as previously requested rather than providing a general statement that, for example, you have "over 48,000 customers." Provide this information within this section for each reported period so a reader may understand how trends in these numbers relate to your performance in the reported periods.
Rest of the question

Also, as previously requested, disclose the actual number of customers for each of your products. To provide appropriate context, revise to disclose the reasons why prior or interim period customer counts are not included for each of your products.

FRSH answered

No reply letter found.

Management's Discussion and Analysis of Financial Condition and Results of Operations · Key Factors Affecting Our Performance, page 64
SEC asked (5)
You state in your response to prior comment 8 that approximately 7% of your customers are customers for more than one product and are therefore counted as a customer for each of your three main product lines. Tell us the number of customers that were counted more than once in your total customer count.
Rest of the question

To the extent this amount is material to your total customer count, please explain further why you believe highlighting a customer count over 50,000 is appropriate. Lastly, where you first present your customer count, ensure that this measure is appropriately defined. In this regard, it is unclear from the disclosures on page 109 that customers can be counted more than once if they purchase multiple products.

FRSH answered

No reply letter found.

Key business metrics, page 72
SEC asked (6)
We note your response to prior comment 11. We further note a number of announcements and public statements on your website regarding the company reaching certain ARR milestones when discussing operating performance. For example, you disclosed on February 21, 2021 that you surpassed $300 million in ARR and experienced 40% year over year ARR growth.
Rest of the question

You also announced on May 5, 2020 that you reached $200 million ARR and the time frame over which you doubled that from $100 million ARR. This was again highlighted in your August 6, 2020 press release discussing your performance for the first half of fiscal year 2020. Thus, it appears that you consider this information material to evaluating your performance. As such, please revise your filing to include a quantified discussion of this metric for each period presented. Refer to SEC Release Nos. 33-10751 and 33-8350.

FRSH answered

No reply letter found.

Key business metrics, page 72
SEC asked (7)
We note your response to our prior comment 12. While a net dollar retention rate for customers on monthly contracts of 100% or more may support the inclusion of your monthly contracts in your annualized revenue based metrics, these contracts nevertheless have no contractual annual recurring revenue associated with them. Thus, this appears to be a known limitation associated with your metric.
Rest of the question

Please revise to disclose this and any other known limitations. Also, revise to disclose the percentage of ARR from monthly contracts for each period presented and explain that the net dollar retention rate for such contracts has historically been lower than the total amounts presented. To the extent you believe that the net dollar retention metric provides relevant context to this limitation, revise to provide the net dollar retention rate for your monthly contracts as included in your response to prior comment 10.

FRSH answered

No reply letter found.

Index to Consolidated Financial Statements, page F-1
SEC asked (8)
Please update the index to indicate that your financial statements also include the unaudited quarterly period ended March 31, 2021.
FRSH answered

No reply letter found.

Note 12. Common Stock and Stock Based Compensation, page F-33
SEC asked (9)
Please refer to prior comment 14. As previously requested, please revise to separately disclose the number of performance-based RSUs and related unrecognized compensation expense that will vest upon this offering.
FRSH answered

No reply letter found.

Note 17. Subsequent Events (unaudited), page F-41
SEC asked (10)
We note that the 174,713 RSUs granted in April 2021, and the related unrecognized compensation expense, are included in the total RSU grants for both your audited and unaudited subsequent events disclosures. Please revise to clarify.
FRSH answered

No reply letter found.

Note 17. Subsequent Events (unaudited), page F-41
SEC asked (11)
We note that in April of 2021, you became aware that a malicious third party gained unauthorized access to your third party vendor, Codecov that affected hundreds of Codecov’s customers, including you. We further note that you disclose a variety of impacts and actions taken as a result of the incident, including engaging a third-party forensics firm to assist in your investigation, response, and impact mitigation.
Rest of the question

Please tell us how you evaluated and assessed any contingent liabilities associated with the Codecov incident. Refer to ASC 450-20-55-14. Also, explain your consideration of disclosing the Codecov incident as a subsequent event pursuant to ASC 855-10-50.

FRSH answered

No reply letter found.

General
SEC asked (12)
Please provide us with a detailed analysis of the exemption (if any) under the Investment Company Act of 1940 that your subsidiaries intend to rely on and how their investment strategies will support that exemption.
FRSH answered

No reply letter found.

General
SEC asked (13)
You state in your response to prior comment 17 that you are not an investment company by virtue of Section 3(b)(1) of the Investment Company Act of 1940. You also state that “while it does not currently appear to be eligible for Rule 3a-1 or Rule 3a-8 under the ICA, it is possible it could be based on its June 30, 2021.” Please provide a detailed analysis supporting your reliance on such Section and Rules.
Rest of the question

In your response, provide us with sufficient detail to assess your analysis.

FRSH answered

No reply letter found.

General
SEC asked (14)
Your response also indicates that the company "intends to divest a portion of the investment securities held by it to reduce the percentage of investment securities to total assets (less Government securities and cash items) to less than 40% of its total assets determined on an unconsolidated basis,” and “that as a result of such divestiture, the relevant percentage of investment securities will be less than 40% of
Rest of the question

total assets as of June 30, 2021.” Please confirm whether you have divested such investment securities (including the divestiture amount) or indicate whether you have set an alternative date for when you will no longer be an investment company as defined under the Investment Company Act of 1940.

FRSH answered

No reply letter found.

General
SEC asked (15)
Please revise the graphics at the forefront of the registration statement to disclose your GAAP cash flow more prominently than your measure of free cash flow. Also, provide footnote disclosure referring a reader to your non-GAAP reconciliation. Refer to Question 102.10 of the Non-GAAP C&DIs and Question 101.02 of the Securities Act Forms C&DIs.
FRSH answered

No reply letter found.

Prospectus Summary · Overview, page 1
SEC asked (1)
Please refer to prior comment 1. To avoid giving undue prominence to a total customer population that contains customers you are not focused on growing and who you have stated do not meaningfully contribute to your financial success, please revise your prospectus summary to also disclose the number of customers with over $5,000 in ARR along with their contribution to total ARR for each period presented, as
Rest of the question

previously requested.

FRSH answered
On behalf of Freshworks Inc. (the “Company”), we are submitting this letter in response to verbal comments received from the staff (the “Staff”) of the Securities and Exchange Commission (the “Commission”) to provide a supplemental analysis of the Company’s stock-based compensation relating to the above referenced Registration Statement on Form S-1 (the “Registration Statement”), filed with the Commission on August 27, 2021. Because of the commercially sensitive nature of information contained herein, this submission is accompanied by the Company’s request for confidential treatment for selected portions of this letter.
Rest of the letter

The Company has filed a separate letter with the Office of Freedom of Information and Privacy Act Operations in connection with the confidential treatment request, pursuant to Rule 83 of the Commission’s Rules on Information and Requests, 17 C.F.R. § 200.83. For the Staff’s reference, we have enclosed a copy of the Company’s letter to the Office of Freedom of Information and Privacy Act Operations, as well as a copy of this correspondence, marked to show the portions redacted from the version filed via EDGAR and for which the Company is requesting confidential treatment. The Company supplementally advises the Staff that it currently estimates a preliminary price range of [***] per share (the “Preliminary Price Range”) for the initial public offering (“IPO”) of its Class A common stock, resulting in a midpoint of [***] per share (the “Midpoint Price”). The Preliminary Price Range was determined by discussions between the Company and Morgan Stanley & Co LLC, J.P. Morgan Securities LLC, and BofA Securities, Inc., the lead underwriters for the Company’s IPO, on behalf of the underwriters (the “Underwriters”), that took place on August 31, 2021. The Preliminary Price Range does not reflect a 10-for-1 forward stock split that is expected to be approved by the Company’s board of directors (the “Board”) and its stockholders, which will be reflected in the next amendment to the Registration Statement. Cooley LLP 3175 Hanover Street Palo Alto, CA 94304-1130 t: (650) 843-5000 f: (650) 849-7400 cooley.com Freshworks Inc. requests that the information contained in this letter, marked by brackets, be treated as confidential information pursuant to 17 C.F.R. §200.83. The Preliminary Price Range has been determined based on a number of factors, including input received from the Company’s “testing the waters meetings” and current conditions in the U.S. equity markets, including the robust reception to the recent initial public offerings of technology companies. In particular, in recent months, there has been a number of high-profile IPOs, including companies that are considered as comparable to the Company. The Price Range does not consider any discount for the current lack of liquidity for both classes of the Company’s common stock and assumes a successful IPO with no weighting attributed to any other outcome for the Company’s business, such as remaining a privately held company or being sold in an acquisition transaction. As described in the Company’s letter dated June 25, 2021, responding to the Staff’s comments received by letter dated June 10, 2021 (the “Initial Comment Letter”), for financial reporting purposes, the Company reassessed the Board-determined fair value of the common stock underlying restricted stock units (“RSUs”) granted on April 12, 2021 and May 17, 2021 (collectively, the “Q2 Grants”), taking into account a contemporaneous independent common stock valuation reports (each, a “Valuation Report”) from the specialist valuation practice of a professional third-party valuation firm commissioned by the Board. As such, the fair value of the Company’s common stock on the dates the Q2 Grants were granted was calculated by linearly interpolating on a daily basis the increase between the Valuation Reports performed immediately prior to (the Valuation Report dated as of March 31, 2021) and immediately after the date of grant (the Valuation Report dated as of June 30, 2021). The Company believes that this straight-line methodology provides the most reasonable basis for the valuation of its Class A common stock because the Company did not identify any single event that occurred during periods between valuation dates that would have caused a material change in fair value. With respect to the RSUs granted on July 7, 2021, August 5, 2021, August 9, 2021 and August 25, 2021 (collectively, the “Q3 Grants”), the Company similarly reassessed the fair value of the common stock by linearly interpolating on a daily basis the increase between the June 30, 2021 Valuation Report and the Midpoint Price. The Company has included the following chart which reflects the date of the RSU grants, the total number of RSUs granted, and the per share fair value of the Company’s Class A common stock on the date of such RSU grants for accounting purposes. The table below does not reflect the 10-for-1 forward stock split to be approved by the Board and the Company’s stockholders. Date of Grant RSUs Granted (pre-stock split basis) Fair Value Per Share of Underlying Common Stock for Financial Reporting The Company will update in the next amendment to the Registration Statement the fair values of the Q3 Grants. Upon the completion of the IPO, outstanding RSUs and performance-based RSUs that have otherwise met the service and other performance conditions will vest, and the Company expects to recognize $65.7 million of related stock-based compensation expense, related to such vested stock, in the quarter ending September 30, 2021. The Company expects the remaining $325.8 million of stock-based compensation expense, related to all outstanding grants as of June 30, 2021, to be amortized over the relevant service period. Freshworks Inc. requests that the information contained in this letter, marked by brackets, be treated as confidential information pursuant to 17 C.F.R. §200.83. Comparison of the July and August 2021 Grant Prices to the Midpoint Price The Company believes that the primary factors that explain the difference between the Midpoint Price and the fair value of the Company’s Class A common stock used for purposes of measuring the grant date fair value of the Q3 Grants are as follows: The valuation considerations for estimating the Midpoint Price information of current conditions in the U.S. equity markets, including increased activity levels for initial public offerings of technology companies despite the relative volatility in the equity markets due to the COVID-19 pandemic and other macroeconomic risks. In particular, the Dow Jones and NASDAQ indices both increased from June 30, 2021 to August 31, 2021 in excess of 700 points and continue to show improvement, and the volume of U.S. technology initial public offerings in 2021 is on pace to set historic records, suggesting a favorable market for companies similar to the Company in executing and completing initial public offerings. Furthermore, the valuations for recent initial public offerings for software companies have increased significantly due to favorable market tailwinds, strong growth, and durable business models. Of note, since September 2020, a number of high-growth technology companies similar to the Company have completed initial public offerings and have realized over 100% increases in trading prices at three months following the applicable initial public offering date relative to their respective initial public offering prices. The Midpoint Price assumes with 100% probability that the Company completes an IPO, and all of the Company’s convertible preferred stock will be converted into common stock. This factor is significant because the holders of the Company’s convertible preferred stock currently enjoy substantial economic rights and preferences over the holders of the Company’s common stock, including the right to receive dividends prior to any dividends declared or paid on any shares of the Company’s common stock and liquidation payments in preference to holders of the Company’s common stock. The corresponding elimination of the preferences and rights enjoyed by the holders of such convertible preferred stock results in a higher valuation of the common stock. The Midpoint Price represents a future price for shares of the Company’s Class A common stock that, if issued in the IPO, will be immediately freely tradable in a public market. In contrast, the June 30, 2021 Valuation Report valued the common stock using a combination of the probability-weighted expected return method (“PWERM”) and Option-Pricing Method (“OPM”) to allocate equity value under two scenarios: (1) a scenario where the Company successfully completes an initial public offering in the near term (weighted at 75%) and (2) remaining a privately held company (weighted at 25%). Then, a discount for lack of marketability of 9.5% was applied, as the shares were then illiquid and might never become liquid. This illiquidity factor is the primary reason for the difference between the estimated fair values of the Q3 Grants and the Midpoint Price. In conclusion, the Company respectfully submits that the differences between the Midpoint Price and the grant date fair values of the Q3 Grants are reasonable and that the deemed per share fair values used as the basis for determining stock-based compensation expense in connection with the RSU grants are reasonable and appropriate in light of the considerations outlined above. Freshworks Inc. requests that the information contained in this letter, marked by brackets, be treated as confidential information pursuant to 17 C.F.R. §200.83.

One letter for all the questions, without numbered answers. Read the reply
Management's Discussion and Analysis of Financial Condition and Results of Operations · Key Factors Affecting Our Performance, page 70
SEC asked (2)
Refer to prior comment 4. Since acquiring new customers is a key factor affecting your business, as previously requested, please revise here in MD&A to provide your customer count for each reported period.
FRSH answered

See the reply above.

Pro Forma Net Loss Per Share Attributable to Common Stockholders, page 14
SEC asked (1)
We note that you reflect the number of RSUs and related compensation expense that will vest as of June 30, 2021 in your pro forma earnings per share. Please revise this adjustment throughout to include the expense and related shares for all RSUs that will vest at the effective date of your IPO, or the most recent practicable date prior to the effectiveness of your registration statement, including those that will
Rest of the question

vest subsequent to June 30, 2021. Please also disclose the date used to determine these amounts. Refer to Article 11-02(a)(6) of Regulation S-X.

FRSH answered
In response to the Staff’s comment, the Company has updated its disclosures on pages 10-12, 14-15, 62-63, 69, 153, and 155 of the Amended Draft Registration Statement to include the expense and related shares for all RSUs that will vest at September 21, 2021, (the currently-anticipated date of the effectiveness of the Company’s registration statement).
Read in the reply
Dilution, page 65
SEC asked (2)
Your pro forma dilution disclosures appear to add the pro forma stock based compensation expense to net tangible assets. Please revise to remove this adjustment from pro forma net tangible assets. In this regard, the expense related to RSUs that vest at effectiveness of your IPO would not be recorded as an asset or liability.
Rest of the question

Further, there is no pro forma impact on total stockholder's equity from this expense as it impacts additional paid-in-capital and accumulated deficit in an equal and offsetting amount, as reflected in your pro forma disclosures on page 15.

FRSH answered
In response to the Staff’s comment, the Company has updated its disclosure on pages 65-67 and 69 of the Amended Draft Registration Statement to remove the adjustment for pro forma stock based compensation expense from pro forma net tangible assets.
Read in the reply

Letters without questions

Other letters

UPLOAD and CORRESP
2 other letters: notices that a filing will not be reviewed, requests to declare a registration effective, and the like

From the SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), 13 letters filed since 2021-06-10. Questions and answers are matched by their numbers; topics come from words in each question. The reports are compared word for word (same form, before the first SEC letter against the first report after the company's reply). No AI.

Sources

The SEC's correspondence on EDGAR: staff letters (form UPLOAD) and company letters (form CORRESP), matched question by question. No AI.

Also

Filings: the letters in the filing list.

Work with it

Excel workbook · CSV. Google Sheet that stays up to date: paste =IMPORTDATA("https://tickdelta.com/company/FRSH/export.csv") into a cell.

Next in Owners and insiders:Insider trades
Esc

Type a ticker such as AAPL, a name, an investor such as Buffett, or a topic such as tariffs. ↑ ↓ to move, Enter to open.