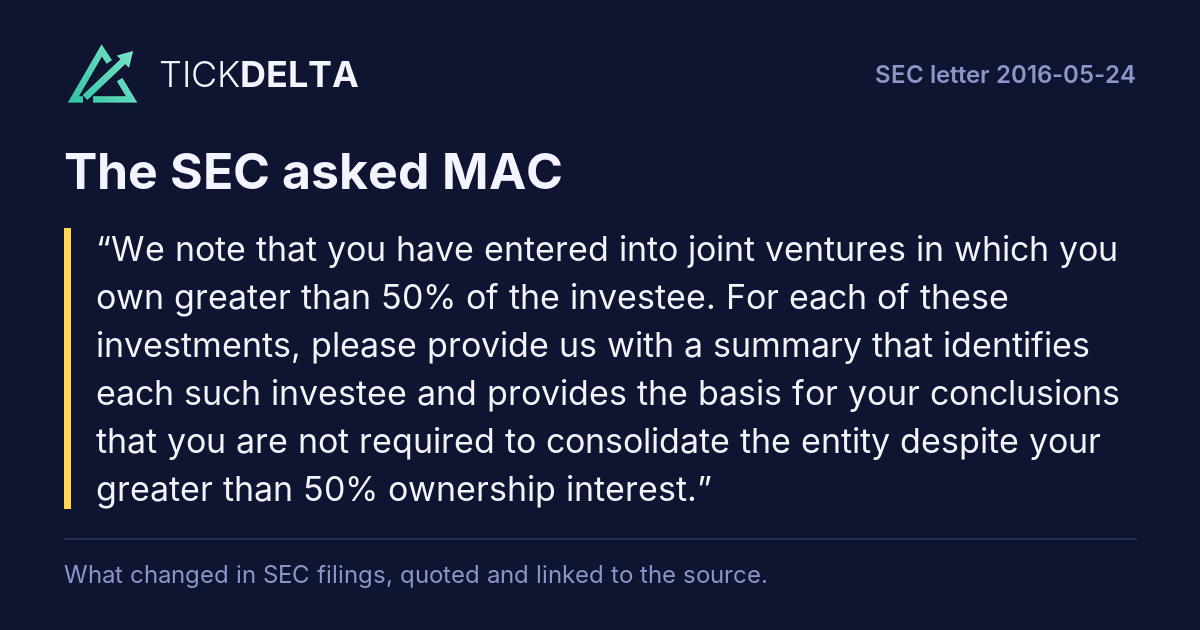
The Company determined Pacific Premier Retail LP (“PPRLP”) was not significant as defined in Rule 3-09 of Regulation S-X during the three year period ended December 31, 2013. The stand-alone financial statements for PPRLP were included in the Company’s Annual Report on Form
for the year ended December 31, 2012 (the “2012 10-K”) as PPRLP was significant for the year ended December 31, 2010. While not required, the Company elected to include audited financial statements of PPRLP for 2012 and 2011 in lieu of unaudited financial statements in the 2012 10-K.
Rest of the answer
During the year ended December 31, 2013, PPRLP sold Redmond Town Center-Office, Kitsap Mall and Redmond Town Center (See Note 4 – Investments in Unconsolidated Joint Ventures of the Company’s Consolidated Financial Statements in the 2013 10-K).
Accordingly, PPRLP classified the results of these dispositions as discontinued operations in its stand-alone financial statements as follows (dollars in thousands):
For the years ended December 31,
Revenues:
2013
2012
2011
Minimum rents
$
103,957
100,848
98,772
Percentage rents
4,019
4,202
4,132
Tenant recoveries
46,939
45,881
44,508
Other
5,357
4,605
4,187
Total revenues
160,272
155,536
151,599
Expenses:
Shopping center and operating expenses
45,152
44,876
45,445
Interest expense
43,445
47,796
45,737
Depreciation and amortization
34,599
32,691
31,535
Total expenses
123,196
125,363
122,717
Income from continuing operations
37,076
30,173
28,882
Discontinued operations:
Gain on sale of assets
182,754
-
Income from discontinued operations
7,926
15,012
19,424
Total income from discontinued operations
190,680
15,102
Net income
227,756
45,275
48,306
Company’s equity from net income:
Continuing operations
15,954
15,345
14,689
Discontinued operations
94,844
7,681
9,879
Total Company’s equity in net income
110,798
23,026
24,568
The Company did not separately present income from continuing and discontinued operations in the Combined and Condensed Statements of Operations of Unconsolidated Joint Ventures in Note 4 of the 2013 10-K. In accordance with Rule 1-02(w) of Regulation S-X, the computation of the numerator in the calculation of significance is based on the registrant’s proportionate share of the pre-tax income from continuing operations reflected in the separate financial statements of the investee. Accordingly, the Company used its proportionate share of PPRLP’s income from continuing operations in the numerator. For purposes of calculating the denominator, in accordance with Rule 1-02(w) of Regulation S-X, the Company used its average income from continuing operations for the past five years since income from continuing operations for 2013 was more than 10% less than the five year average income.
The following table sets forth the Company’s significance test for PPRLP in accordance with Rule 3-09 of Regulation S-X for the year ended December 31, 2013:
The Macerich Company (“Registrant”)
Test of Significant Subsidiaries (Rule 3-09 of Regulation S-X)
December 31, 2013
(Dollars in thousands)
Registrant
Adjustments
Income from for Discontinued
Operations, Income
Taxes and
Adjusted
Continuing
Noncontrolling
For the Years Ended December 31
Operations
Interests
159,023
(99,937
)
59,086
303,166
(35,173
267,993
239,442
(32,364
207,078
2010
29,191
(19,573
9,618
2009
201,786
(36,005
165,781
5-Year Average
141,911
Current Year compared to 5-Year Average
41.6%
Income used for Registrant (1)
Subsidiary - PPRLP
Investment Test
Total Investment in Subsidiary
(59,632
Total Assets - Registrant
9,075,250
-1%
Income Test
Pre-tax income - Subsidiary pro rata
Pre-tax income - Registrant
11%
(1) In accordance with Rule 1-02(w) of Regulation S-X, the denominator in the pretax income test may be replaced by the registrant’s average pretax income over the last five fiscal years when the registrant’s current year pretax income is at least 10% lower than that average.
As provided above, PPRLP’s income from continuing operations was below 20% of the Company’s income from continuing operations for the year ended December 31, 2013. Accordingly, separate stand-alone financial statements of PPRLP were not required to be filed in the 2013 10-K.
In making this response, the Company acknowledges that: the Company is responsible for the adequacy and accuracy of the disclosure in the filing; Staff comments or changes to disclosure in response to Staff comments do not foreclose the Commission from taking any action with respect to the filing; and the Company may not assert Staff comments as a defense in any proceeding initiated by the Commission or any person under the federal securities laws of the United States.